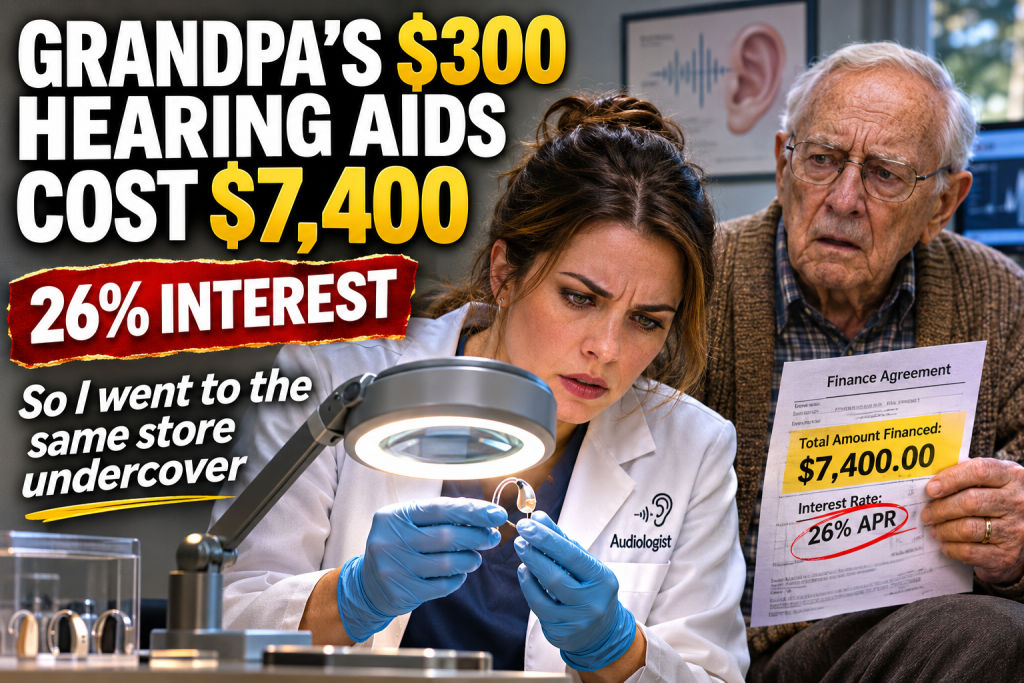
Grandpa signed what he thought was an insurance form after a free hearing screening. Six months later, a finance company said he owed $7,400 at 26% interest. I am an audiologist, so I looked up the model numbers. They were basic devices that sell for about $300 at any pharmacy. So the next week, I booked my own appointment at that store under my married name.
PART 1 — A LITTLE HARD OF HEARING
My grandfather, Walter Brennan, is eighty-four years old and lives in a small brick house in south St. Louis, three blocks from the church where he has sung in the choir since 1962. He was a mail sorter for the post office for thirty-six years. He’s a gentle, funny, stubborn man who still wears a tie to Sunday dinner and still calls my grandmother “Sweetheart” after sixty-one years of marriage.
For the past few years, he has been a little hard of hearing. He turns the television up loud enough to rattle the windows. He nods at things he didn’t actually catch. At family dinners, he sits at the end of the table, smiling, and I can tell he’s missing half the conversation. It breaks my heart a little, because he used to be the one telling all the stories.
I’m an audiologist. That’s my job. I diagnose hearing loss and fit people with hearing aids for a living. For years, I begged Grandpa to let me test his hearing properly. He always said he was fine. “I hear what I need to hear,” he’d say, and wink at my grandmother.
So I was surprised, last spring, when he called to tell me he’d “taken care of it.”
He’d seen a sign in the window of a hearing store in a strip mall near his house. FREE HEARING SCREENING. He went in on a whim. A friendly salesman tested him, told him he had “significant hearing loss,” and fit him with two hearing aids that same afternoon.
“They’re very advanced,” Grandpa told me proudly. “Top of the line. And the young man said Medicare would cover almost all of it.”
I hesitated. Traditional Medicare generally doesn’t cover hearing aids. Some Medicare Advantage plans offer a hearing benefit, but Grandpa has traditional Medicare with a supplement. But I didn’t want to spoil his good mood. He sounded so happy. He said he could hear the birds in the morning again.
“That’s wonderful, Grandpa,” I said. And I let it go.
I hear what I need to hear, he’d say, and wink at my grandmother.
PART 2 — THE BILL
Six months later, Grandpa called me again. This time, he sounded confused and a little frightened.
He had received a letter from a finance company he’d never heard of. It said he owed seven thousand, four hundred dollars for “hearing instruments,” on a credit plan with an interest rate of twenty-six percent. His first payment was overdue. If he didn’t pay, they would send the account to collections.
“I don’t understand,” he said. “The man said Medicare would pay. I only signed something to start the insurance claim.”
I drove over that evening. My grandmother had the letter on the kitchen table, along with a folder from the hearing store. Inside the folder were the papers Grandpa had signed that day. He had signed five times. One of those signatures was on a retail installment contract with the finance company, for the full price of the hearing aids. The interest rate was printed in very small type on the back.
There was no insurance claim anywhere in the folder.
Grandpa sat down heavily at the table. “I should have read it,” he said. “I didn’t have my reading glasses. The young man said it was just the insurance paperwork. He said it so nicely.”
“It’s not your fault, Grandpa,” I said. And I meant it. I’ve worked with older patients for twelve years. I know how these conversations go. A friendly voice, a little bit of hurry, and a stack of papers. Nobody reads every page. Not even people half his age.
“Can I see the hearing aids?” I asked.
He took them out of his ears and set them on the table. They were small, beige, behind-the-ear devices, in a fancy black case with a silver logo. My grandmother brought me the magnifying lamp from her sewing room.
I picked one up and turned it over under the light. Then I looked at the tiny model number printed inside the battery door.
A friendly voice, a little bit of hurry, and a stack of papers. Nobody reads every page.
PART 3 — THE MODEL NUMBER
I knew the brand. I knew it immediately. And I felt my stomach drop.
These weren’t top-of-the-line prescription hearing aids. They weren’t even mid-range. They were basic over-the-counter hearing devices. Since 2022, people with mild to moderate hearing loss have been able to buy hearing aids over the counter, without seeing a professional. That’s a good thing. Many people benefit from them, and they’ve made hearing help much more affordable.
But this particular model sells for about three hundred dollars a pair at almost any pharmacy. I’ve seen them hanging on racks next to the reading glasses.
I looked it up on my phone to be sure. Three hundred and nine dollars, at the pharmacy two miles from Grandpa’s house.
The salesman had taken a three-hundred-dollar product, done a little basic programming, put it in an expensive-looking case with his store’s logo, and sold it to my grandfather for seven thousand, four hundred dollars. Twenty-four times what it was worth. Plus twenty-six percent interest.
And here’s the worst part, as an audiologist. Grandpa didn’t have mild hearing loss. I tested him properly that week in my clinic. He had moderately severe hearing loss in both ears, worse at high frequencies, the kind that makes it hard to understand speech in noisy places. Over-the-counter devices are designed for mild to moderate loss. For Grandpa, they were the wrong tool. They helped him hear the birds, but not the conversation at dinner.
So the store hadn’t just overcharged him. They had sold him the wrong product for his hearing, at an outrageous price, using a false promise about Medicare.
I sat at Grandma’s kitchen table that night and got angry in a way I don’t usually let myself get angry.
Then I had an idea.
They helped him hear the birds, but not the conversation at dinner.
PART 4 — UNDER MY MARRIED NAME
The store didn’t know me. I’m Dr. Rachel Brennan at my clinic, but I married last year, and my legal name is now Rachel Delgado. And I look younger than I am, people tell me.
I called the store and made an appointment for a free hearing screening. I said my hearing had gotten worse lately and I was worried. I gave my married name.
I’ll be honest: I thought hard about whether this was fair. I’m a professional. I don’t like deceiving anyone. But I wanted to know if what happened to Grandpa was one salesman’s bad day, or the way this store did business. I needed to see it for myself.
I talked to a lawyer friend first. She told me that Missouri is a one-party consent state, which means I could legally record a conversation that I was part of. She told me to keep the recording private, to not lie about anything that mattered legally, and to hand everything over to the authorities instead of trying to handle it myself.
On a Thursday afternoon, I walked into the strip-mall store with my phone recording in my purse.
The salesman’s name tag said Todd. He was in his thirties, very friendly, with a firm handshake and a lot of eye contact. He sat me in a little booth with headphones and ran a screening. It was quick, maybe five minutes. Not a real diagnostic hearing test. He didn’t look in my ears. He didn’t test how well I understood speech. He didn’t ask about my medical history.
My hearing, as I knew perfectly well, is normal. Better than normal.
Todd looked at his computer screen and frowned in a concerned way. Then he looked up at me with a sympathetic smile.
“Mrs. Delgado,” he said, “I’m afraid you have some significant hearing loss.”
He didn’t look in my ears. He didn’t test how well I understood speech. My hearing is normal.
PART 5 — THE SAME BOX
Todd showed me a colorful chart on his screen that didn’t look like any audiogram I’ve ever seen. He told me my hearing loss could lead to “cognitive decline” if I didn’t treat it quickly. That was a scare tactic. Untreated hearing loss is linked to cognitive decline in research, but he was using it to frighten someone with perfectly normal hearing.
Then he said, “Good news, though. I have exactly the right device for you. Our most advanced model.”
He got up, went to a cabinet in the back, and came back carrying a black case with a silver logo.
I knew what was in it before he opened it. He picked up the exact same box.
He opened it. The same beige over-the-counter devices Grandpa had. He put them in my ears, plugged them into a laptop, clicked a few things, and asked me how they sounded.
“Very clear,” I said. My hearing is normal. Of course it was clear.
Then came the price. “Normally these are eighty-nine hundred,” Todd said, “but we’re running a special this month. Seven thousand four hundred.” And then, without me even asking, he said the magic words. “And of course, Medicare will cover most of that.”
I’m thirty-five years old. I’m not on Medicare.
“I’m not sure I’m on Medicare,” I said carefully.
He waved his hand. “Don’t worry about the paperwork. We’ll handle all the insurance. You just sign a few forms to get the claim started, and we can get you set up today with zero down.”
He slid a stack of papers across the desk. Five signature lines, marked with little yellow sticky arrows. The top page said “Patient Information.” The third page, half hidden under the others, was a retail installment contract with the same finance company that sent Grandpa the letter.
I told Todd I needed to think about it and would come back. He gave me his card and told me the special ended Saturday.
I sat in my car in the parking lot for twenty minutes, shaking.
Don’t worry about the paperwork. You just sign a few forms to get the claim started.
PART 6 — MAKING THE CALLS
That night, I typed up everything. My grandfather’s papers. The model numbers and pharmacy prices. My own test results from my clinic showing my normal hearing. A summary of what Todd said, with times from the recording.
Then I filed complaints with three places.
The first was the Missouri board that licenses hearing instrument specialists. In most states, people who sell and fit hearing aids have to be licensed, and they’re required to follow rules about testing, fitting, and honest advertising. Todd’s license number was printed on his business card.
The second was the Missouri Attorney General’s consumer protection office.
The third was the Federal Trade Commission, which oversees deceptive sales practices nationwide.
I also called the finance company and disputed Grandpa’s debt. I explained that the loan was obtained through false claims about Medicare coverage. And I learned something important. Under a federal rule called the FTC Holder Rule, when a store arranges financing for a customer, the customer can generally raise the same complaints against the lender that they could raise against the store. In other words, the finance company couldn’t simply say, “That’s between you and the store. Pay up.”
The finance company put the account on hold while it investigated.
A week later, an investigator from the Attorney General’s office called me. Her name was Monica Shaw. She asked if I would be willing to share the recording.
“We’ve had complaints about this store before,” she said. “Four of them. All from seniors. All with the same story about Medicare. But it was always their word against the salesman’s. This is the first time anyone has brought us something we can actually hear.”
We’ve had complaints about this store before. All from seniors. All with the same story about Medicare.
PART 7 — SIXTY-THREE
The investigation took several months. When the Attorney General’s office subpoenaed the store’s sales records, the picture became clear.
Over three years, the store had sold over-the-counter devices costing about three hundred dollars to sixty-three customers for prices between five thousand and nine thousand dollars. Almost every customer was over seventy. Almost every sale was financed through the same finance company, at twenty-four to twenty-nine percent interest. In dozens of the customer files, there were handwritten notes from salespeople: “Medicare discussed.”
Todd wasn’t the only salesman, but he was the top seller. He earned a commission on every financed sale.
Some of the customers had already paid off their loans in full, with interest. One widow had paid more than ten thousand dollars over two years for a pair of devices she kept in a drawer because they whistled. A retired factory worker had taken money from his emergency savings to pay off his loan early, because the interest scared him.
The store’s owner claimed the salesmen were “independent contractors” and he didn’t know what they were saying. But the investigators found a training binder in the back office. One page was titled “Overcoming Objections.” Under the objection “I can’t afford it,” the scripted answer was: “Most of our patients find that their insurance covers the majority of the cost.”
It wasn’t one bad salesman. It was a script.
Monica Shaw called to tell me before it was public. “I want you to know,” she said, “that your grandfather’s folder and your recording are the reason sixty-two other people are getting their money back.”
I cried at my desk at work. My next patient, an eighty-year-old retired nurse, handed me a tissue and asked what was wrong. When I told her, she said, “Good for you, honey. Good for you.”
It wasn’t one bad salesman. It was a script.
PART 8 — THE SETTLEMENT
The case ended with a settlement between the Attorney General’s office, the store’s owner, and the finance company.
Every one of the sixty-three customers had their loan cancelled. Anyone who had already made payments got a full refund of everything they paid, including interest. The finance company agreed to correct the credit reports of every customer whose account had been sent to collections. Grandpa’s account was cancelled, and his credit report was cleaned up.
The store’s owner paid a large civil penalty and agreed to close all three of his locations. The state licensing board suspended Todd’s license and the licenses of two other salesmen. Todd’s was later revoked.
The finance company also agreed to stop working with hearing aid retailers in Missouri unless they followed strict new rules, including giving customers a plain-language summary of the loan, in large print, before they sign anything.
When the refund check came for one of the store’s other victims, the widow with the devices in her drawer, she sent a thank-you card to the Attorney General’s office. Monica Shaw forwarded a copy to me. In shaky handwriting, it said: “I thought I was just a silly old woman who got fooled. Thank you for showing me I was not the only one.”
That’s what these schemes really take from people. Not just money. They make people feel foolish, so they stay quiet. Most of those sixty-three seniors never complained to anyone because they were embarrassed.
Grandpa wasn’t embarrassed anymore. He told the whole story to his choir. Then to his barber. Then to the man at the hardware store. By the end of the summer, I think half of south St. Louis knew about the hearing store.
They make people feel foolish, so they stay quiet.
PART 9 — THE RIGHT HEARING AIDS
Here’s my favorite part.
Once everything was settled, I finally got to do what I’d been wanting to do for years. I gave my grandfather a complete hearing evaluation at my clinic. A real one. A full diagnostic test in a soundproof booth. A look inside his ears. A speech test in quiet and in noise. A long conversation about what was hard for him and what he wanted to hear.
Then I fit him with a pair of prescription hearing aids matched to his actual hearing loss. With his supplement and a discount program, they cost a fraction of what the store had charged, for a product that was right for him.
I programmed them carefully. I adjusted them over three follow-up visits. I taught him how to use the settings for restaurants and church.
The first Sunday he wore them, I sat next to him in the pew. When the choir started the opening hymn, he froze. Then he turned and looked at me with his eyes wide.
“I can hear the altos,” he whispered. “Rachel, I haven’t heard the altos in ten years.”
He sang the whole hymn with tears running down his face. My grandmother held his hand.
That night at Sunday dinner, he sat in the middle of the table instead of at the end. He heard every word. He told stories. He interrupted people. He laughed at my brother’s terrible jokes, and then told some terrible jokes of his own. He was himself again.
At one point, my grandmother leaned over to me and said quietly, “I forgot how much he talks.”
Then she smiled. “I missed it.”
I can hear the altos. I haven’t heard the altos in ten years.
PART 10 — WHAT I TELL MY PATIENTS NOW
I’ve told this story to dozens of my patients since then, and to their families. Here’s what I want everyone to know.
Over-the-counter hearing aids are a good thing. For people with mild to moderate hearing loss, they can be a wonderful, affordable option. But they should cost hundreds of dollars, not thousands. If someone tries to sell you an over-the-counter device for thousands of dollars, walk away.
Traditional Medicare generally does not cover hearing aids. Some Medicare Advantage plans do offer hearing benefits. If someone tells you “Medicare will cover it,” call Medicare or your plan directly and ask before you sign anything.
A free “screening” is not the same as a full hearing evaluation. A real evaluation includes looking in your ears, testing your hearing at many frequencies, and testing how well you understand speech. It usually takes thirty minutes to an hour.
Never sign anything you haven’t read. Ask to take the papers home. A legitimate business will let you. If they say the deal ends Saturday, that’s a sales tactic, not a reason to rush.
Ask about the trial period and the return policy, in writing. Many states require hearing aid sellers to offer a trial period. Grandpa’s store never told him about his.
And if you have an older parent or grandparent who suddenly comes home with something expensive, ask to see the paperwork. Not to embarrass them. To protect them.
Last Christmas, the choir did a special concert. Grandpa had a solo. He was nervous for weeks. When it was his turn, he stood up straight in his tie, and he sang “O Holy Night,” and he hit every note, because for the first time in ten years, he could hear himself.
My grandmother cried. I cried. Half the church cried.
Afterward, he found me in the crowd and gave me a big hug. “Best investment I ever made,” he said. “And it didn’t cost me seven thousand dollars.”
Best investment I ever made. And it didn’t cost me seven thousand dollars.