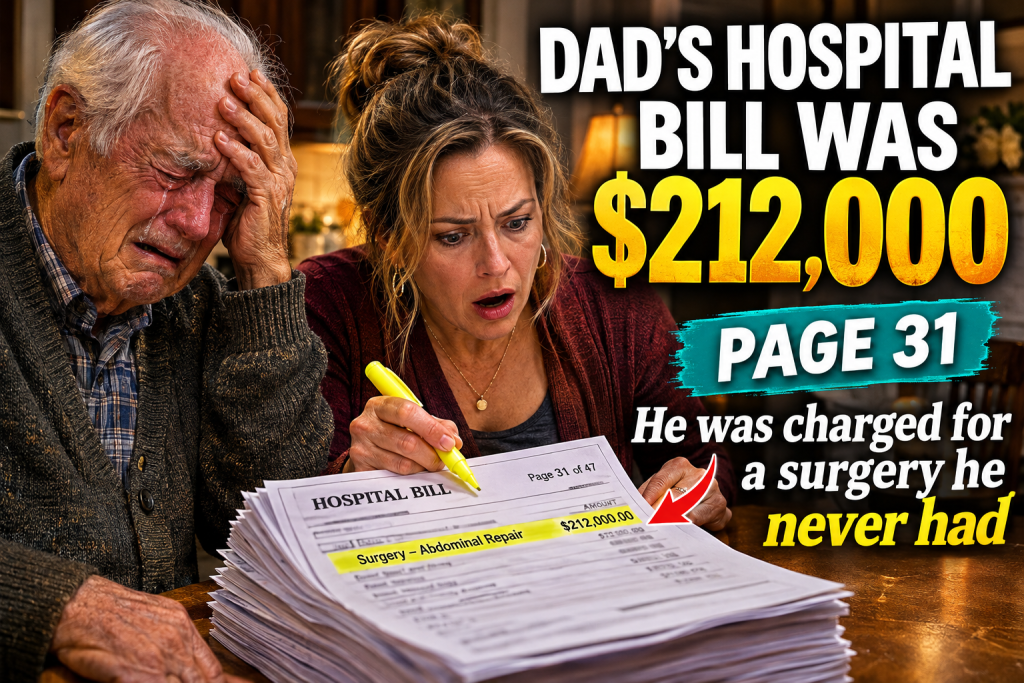
Dad lived through a heart attack and eleven days in the ICU, then a bill for $212,000 nearly finished what the heart attack started. He wept at his kitchen table and talked about selling the house. The billing office offered a payment plan bigger than his whole Social Security check. So I asked for the itemized bill, sat down with a highlighter, and on page 31 I stopped breathing.
PART 1 — ELEVEN DAYS
My father, Walter Brandt, is eighty-one years old. He spent thirty-eight years as a machinist at a plant outside Dayton, Ohio, and he has the hands to prove it: thick fingers, two crooked knuckles, and a scar across one palm from a lathe in 1974. He is not a man who complains. When he had his heart attack last February, he drove himself halfway to the hospital before he pulled over and called 911 from the shoulder of the road.
I’m Linda. I’m fifty-four, and I’ve worked as a pharmacy technician at a hospital in Dayton for twenty-two years. I live fifteen minutes from Dad. My mother passed in 2017, and since then I’ve been the one who takes him to his appointments, sorts his pills into the little plastic box with the days of the week, and calls every night at seven.
The paramedics found him slumped in his Buick with the hazard lights blinking. He spent eleven days in the ICU. There were two nights when the doctors called me into the family room and used words like “prepare yourself.” I slept in a chair beside his bed with my coat over my knees. I watched the numbers on the monitors like they were stock prices.
He survived. Thank God, he survived.
By the end of the second week, he was sitting up and grumbling about the food. By the end of the third, he was home in his recliner, watching the Reds spring training games and pretending not to need his cane.
I thought the worst was over. I had been so focused on keeping him alive that I never once thought about what it would cost.
When your father is fighting for his life, you don’t think about money. That’s exactly why the money part can hurt you so badly afterward.
Dad has Medicare and a supplement plan he has paid for faithfully since he retired. He used to say, “That’s what insurance is for, Lindy. So nobody has to lose their house over a hospital stay.”
He believed that. So did I.
PART 2 — THE ENVELOPE
The bill came three months later, on a Tuesday in May. Dad called me at work, which he never does.
“Lindy,” he said, “can you come over after your shift? I got something in the mail I don’t understand.”
I found him at his kitchen table, the same yellow Formica table he and Mom bought in 1971. He had his reading glasses on and a single sheet of paper in front of him. He slid it across to me without a word.
It was a statement from the hospital. At the bottom, in bold print, it said: Amount Due From Patient: $212,000.
I read it twice. I thought it had to be a mistake. A misprint. An extra zero.
“They say Medicare didn’t cover all of it,” Dad said quietly. “They say the rest is mine.”
Then my father, who drove himself toward the hospital in the middle of a heart attack, put his face in his big scarred hands and cried.
“I’ll have to sell the house,” he said. “Your mother’s house. There’s no other way.”
I had never seen him cry like that. Not even at Mom’s funeral. At the funeral he stood straight as a fence post and shook every hand. This was different. This was a proud man who had paid every bill on time for sixty years, suddenly feeling like a failure at his own kitchen table.
I put my hand on his back. “Dad, don’t do anything yet,” I said. “Let me look into this.”
“It’s the hospital, Lindy,” he said. “They know what they’re doing. Who are we to argue?”
I have worked inside a hospital for twenty-two years. I knew one thing for certain: hospitals are run by people, and people make mistakes. Sometimes worse than mistakes.
I took the statement home that night and put it on my own kitchen table. I didn’t sleep much.
PART 3 — THE PAYMENT PLAN
The next morning I called the hospital’s billing office. After forty minutes on hold, a young man named Tyler came on the line. He was polite, but he sounded like he was reading from a script.
I explained that my father was eighty-one, on Medicare with a supplement plan, and that a $212,000 balance made no sense.
“I understand, ma’am,” Tyler said. “I’m showing that Medicare denied a portion of the claim. The remaining balance is the patient’s responsibility.”
“Which portion? Denied for what?”
“I don’t have that detail in front of me,” he said. “But I can set up a payment plan. Based on the balance, we could do $1,800 a month.”
My father’s entire Social Security check is $1,900 a month. Plus a small pension from the plant that barely covers his property taxes and his electric bill.
“He would have a hundred dollars a month to live on,” I said. “For groceries. For his medicine. For heat in the winter.”
“I’m sorry, ma’am. That’s the lowest plan the system allows for that balance. If the account goes unpaid, it may be referred to collections.”
Collections. My father, who had never missed a payment in his life, in collections.
I asked the one question I knew to ask, because I had heard nurses and social workers say it a hundred times in the hallways where I work.
“I want an itemized bill,” I said. “Every charge. Every line. Every date.”
There was a pause. “That can take some time to process.”
“Then start processing it,” I said. “Today.”
In twenty-two years of working in a hospital pharmacy, I had learned that the summary page tells you what they want you to pay. The itemized bill tells you what actually happened.
Tyler said he would submit the request. He said it could take up to thirty days.
PART 4 — FORTY-SEVEN PAGES
It took six weeks.
In the meantime, two more statements arrived at Dad’s house, each one stamped PAST DUE in red. Then a phone call from a number he didn’t recognize, asking him to “make arrangements.” He hung up and called me, shaking.
I told him not to answer unknown numbers anymore. I told him to put every piece of mail from the hospital in a grocery bag and give it to me unopened. He did. It was the first time in his life he ever let anyone else handle his mail.
The itemized bill finally came in a thick manila envelope. It was forty-seven pages long.
I waited until Saturday morning. I made a pot of coffee, sat down at my own kitchen table, and took out a yellow highlighter, a red pen, and the little notebook where I had written down everything I remembered from Dad’s eleven days in the ICU. Every procedure. Every test. Every doctor who came by. I had kept that notebook out of habit, the way you do when someone you love is very sick and you need to feel like you’re doing something.
I read every line.
Most of it was what I expected. The ICU room charges, which were enormous. The cardiac catheterization on the first night. The stent. The medications, which I understood better than most people would, because I order and dispense those same drugs every day. The lab work. The imaging.
Some things I highlighted in yellow because they seemed high. Some things I circled in red because I wasn’t sure what they were. I made a list of questions in my notebook.
Then I turned to page 31.
And I stopped.
I read that one line four times. Then I set the highlighter down, because my hand was shaking too much to hold it.
PART 5 — PAGE 31
On page 31, there was a charge for a surgical procedure. A second cardiac surgery, with operating room time, anesthesia, a surgical team, and post-operative recovery. The total for that one line and the charges attached to it was more than $140,000.
It was dated day six of Dad’s stay.
Dad never had a second surgery.
I knew it the way you know your own name. On day six, I was sitting beside his bed. He was propped up on pillows, complaining that the Jell-O was the wrong color. I remember because he made me laugh for the first time in a week. He said, “Lindy, what kind of hospital serves green Jell-O to a man with a heart condition? Green is not a food color.”
I had written it in my notebook that day: Day 6. Sitting up. Ate Jell-O. Joked. Thank you, Lord.
There was no surgery. He never left that room except for a chest X-ray, which was also listed, correctly, on page 29.
Then I looked at the name of the surgeon listed on that line.
I didn’t recognize it. That alone was odd, because I had met every doctor who came into Dad’s room. I had written down their names.
That night, I went to the hospital’s website and looked at their list of cardiac surgeons. The name wasn’t there. I searched further and found an article from the hospital’s own newsletter, two years old, with a smiling photo: the surgeon’s retirement party. Thirty-one years of service. Cake and balloons.
He had retired two years before my father’s heart attack.
My father was charged $140,000 for a surgery he never had, performed by a doctor who no longer worked there, on a day he was eating Jell-O with me.
I sat at my kitchen table until two in the morning, going through the rest of the pages. I found smaller problems too. Medications charged twice. A day of ICU charges after Dad had already been moved to a regular room. But nothing like page 31.
PART 6 — CALLING THE RIGHT PEOPLE
On Monday morning, I didn’t call the billing office. I knew from experience that billing representatives can’t fix big errors. They can only read what’s on the screen.
Instead, I did three things.
First, I asked to speak with the hospital’s patient advocate. Most hospitals have one. Their job is to help patients and families with problems, including billing problems. Ours was a soft-spoken woman named Marisol Ortega who had been a nurse for twenty years before taking the job.
I brought her a copy of page 31, my notebook from day six, and a printout of the retirement article. She read them in silence. Then she took off her glasses.
“Mrs. Brandt,” she said, “this needs to go to our compliance department today.”
Second, I called Medicare directly, using the number on Dad’s card. I asked them for Dad’s Medicare Summary Notice for those dates, which shows exactly what the hospital billed to Medicare and what Medicare paid or denied. When it arrived, it showed that the hospital had billed Medicare for the same phantom surgery. Medicare had denied it, because the codes didn’t match the rest of the records. And the hospital had simply moved the whole denied amount over to Dad’s balance.
Third, I called Dad’s supplement insurance company and asked them to review the claim too.
Then I went to Dad’s house and sat with him at the yellow table.
“Dad,” I said, “you’re not selling the house.”
“How do you know?”
I showed him page 31. I showed him my notebook. Day 6. Ate Jell-O. Joked.
He read it, and then he read it again, and then he laughed, a little shaky.
“I knew that Jell-O was suspicious,” he said.
It was the first time he’d laughed since the envelope came. I’ll remember that sound for the rest of my life.
PART 7 — THE INVESTIGATION
The hospital’s compliance department opened a formal review. A compliance officer named Mr. Fenwick called me two weeks later. He was careful with his words, the way lawyers and compliance people always are.
He told me that the hospital had found the error. The charge on page 31 had been entered under the wrong patient account. It belonged to a different patient, a man who had actually had that surgery, years earlier, under the retired surgeon. Somehow, an old charge had been copied into Dad’s account during a billing system conversion.
That was the official explanation.
But I work in a hospital. I know how these systems work. And something about it bothered me. So did the duplicate medications, and the extra ICU day.
I asked Mr. Fenwick a question. “Is my father the only one?”
There was a long pause.
“We are reviewing other accounts from the same period,” he said finally.
Over the next several months, I learned, through a nurse friend and later through a story in the local newspaper, that the review had found hundreds of accounts with similar problems. Charges for procedures that never happened. Duplicate charges. Room charges for days patients weren’t in those rooms. Many of the patients were elderly. Many were on Medicare. Many, like Dad, had simply been told the balance was their responsibility and offered a payment plan.
The hospital hired an outside auditing firm. It reported itself to the government, as hospitals are required to do when they discover billing problems involving Medicare.
The newspaper story quoted a retired nurse who said, “Most people never ask for the itemized bill. They just pay. Or they lose their homes trying.”
I cut that article out and put it on my refrigerator.
PART 8 — THE LONG SUMMER
The review took most of the summer. Those were hard months.
The hospital had agreed to put Dad’s account on hold while compliance investigated, which meant no more collection calls. But the balance still showed on his online portal. Every time he logged in to check an appointment, there it was: $212,000. He stopped logging in. Then he stopped sleeping well. His cardiologist noticed his blood pressure creeping up and asked if he was under stress.
“My daughter says I’m not supposed to worry about it,” Dad told him. “But a man worries.”
I tried to keep his mind off it. I took him fishing at the reservoir on Sunday afternoons, the way he used to take me when I was little. We didn’t catch much. We didn’t talk much either. But he’d sit there in his folding chair with his line in the water, and for a few hours the deep crease between his eyebrows would ease.
One afternoon in July, out of nowhere, he said, “Lindy, if they don’t fix it, I want you to know I don’t blame you.”
“Blame me for what, Dad?”
“For pushing them. If it makes things worse.” He reeled in his line slowly. “Your mother always said I was too stubborn to ask questions. She’d have been the one at that table with the highlighter. Not me.”
I didn’t know what to say. So I baited his hook for him, the way he used to bait mine, and handed the rod back.
Sometimes the hardest part of fighting for someone you love is that they can’t help worrying while you fight. All you can do is keep showing up.
I called Marisol, the patient advocate, every two weeks. She always called back. Every time, she said the same thing. “We’re still working on it, Mrs. Brandt. Don’t let him pay anything.”
PART 9 — THE NEW BILL
In September, a new envelope arrived at Dad’s house. I opened it with him at the kitchen table.
It was a corrected statement. The phantom surgery was gone. The duplicate medications were gone. The extra ICU day was gone. Medicare had reprocessed the remaining legitimate charges, and Dad’s supplement plan had paid its share.
The new amount due from the patient was $1,140.
Not $212,000. One thousand, one hundred and forty dollars.
Dad stared at it for a long time. Then he took off his reading glasses, folded them, and set them on the table very carefully.
“Lindy,” he said, “I was going to sell your mother’s house.”
“I know, Dad.”
“I was going to call the real estate lady on Monday. I had her card on the refrigerator.”
I didn’t know that. I hadn’t known he was that close.
The hospital also sent a letter of apology, signed by its chief financial officer. It said the account had been corrected, that any collection activity had been withdrawn, and that Dad’s credit would not be affected. A few weeks later, the hospital’s patient financial assistance office called to say that, given Dad’s income, he qualified for their charity care program, which reduced even the $1,140 to $280.
Dad paid it the same day. In person. With a check. He insisted on driving himself.
When he came home, he took the real estate lady’s card off the refrigerator and threw it in the trash. Then he put my newspaper clipping in its place.
PART 10 — WHAT I WANT YOU TO KNOW
It’s been a year now. Dad is eighty-two. He walks a mile every morning with his cardiologist’s blessing. He still complains about green Jell-O whenever he gets the chance.
I’ve become, without meaning to, the person people call. Coworkers. Neighbors. Women from church. “Linda, can you look at my mother’s hospital bill?” I always say yes. I’ve found problems in about half of them. Small ones, mostly. A few big ones.
I’m sharing our story because I know there are thousands of older Americans sitting at kitchen tables right now with bills they don’t understand, thinking about selling their homes.
Here is what I want you to know.
Always ask for an itemized bill. Not the summary. The itemized bill, with every charge, date, and code. You have a right to it.
Compare it to what really happened. If you can, keep a notebook during a hospital stay. Write down the procedures, the tests, the doctors. It may become your most important evidence.
Check your Medicare Summary Notices, and call Medicare if something doesn’t match.
Ask for the hospital’s patient advocate, and ask about financial assistance or charity care. Many nonprofit hospitals are required to have these programs.
And never agree to a payment plan for a bill you don’t understand. Once you start paying, it can feel like you’ve admitted you owe it.
My father survived a heart attack. He almost didn’t survive the bill. What saved him was a highlighter, a notebook, and a memory of green Jell-O on day six.
Last week, Dad called me at seven o’clock, the way I usually call him.
“Lindy,” he said, “I just wanted to tell you something. Your mother always said you were the smart one.”
“She said that about everybody, Dad.”
“No,” he said. “Just you. And she was right.”