Twenty-six years on a factory floor bought me a plaque, a sheet cake, and a retirement I thought was safe. Three weeks later, most of my savings had vanished through loans I never asked for. The trail led to a coworker who cried at my farewell party. And when I asked whether anyone else had been hit, the silence on the phone told me this was much bigger than me.
PART 1 — The Balance
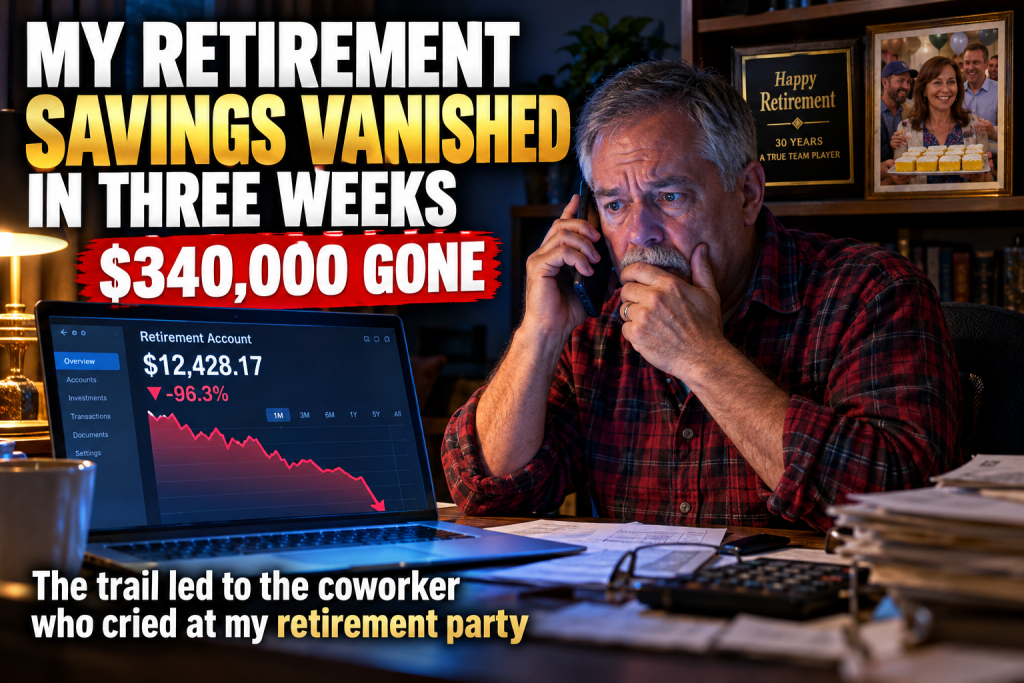
After twenty-six years at Lakeside Precision Castings in Fort Wayne, Indiana, I retired at sixty-three with a sheet cake, a brass plaque, and what I believed was about $340,000 in my 401(k).
The party was in the break room on a Friday afternoon. Someone hung a banner that said “Happy Retirement, Earl!” in red letters. My wife, Bonnie, came in her church dress. The guys from second shift signed a card with jokes I won’t repeat. Linda Okafor from the benefits office brought a tray of lemon bars, because she knew they were my favorite. She hugged me at the door on my way out and cried a little.
“You deserve every good thing, Earl,” she said.
I believed I had earned it. I had checked my statements every quarter for twenty-six years. I watched that number grow through the 2008 crash and the pandemic. I never took a loan against it. Never cashed out early. My father worked at a foundry his whole life and retired with a gold watch and almost nothing else. I promised myself I would do better.
Three weeks into retirement, I sat down at the kitchen table with my reading glasses and logged in to set up my first monthly withdrawal.
The balance was $61,000.
I took off my glasses, cleaned them on my shirt, and put them back on. It still said $61,000.
I called Bonnie in from the garden. She looked at the screen and sat down hard in the chair next to me.
“That’s a computer mistake,” she said. “It has to be.”
“Has to be,” I agreed.
I called the 401(k) plan administrator, a big national company that managed the plan for Lakeside. After twenty minutes on hold, I got a young woman named Brittany who was polite and patient.
“Mr. Whitfield, I see the account history,” she said. “It’s not a system error. There have been a series of hardship loans taken against your account, starting in 2019.”
“Hardship loans? I’ve never taken a loan in my life.”
“There are seven of them,” she said. “Each one approved, each one signed electronically, and each one deposited by direct deposit.”
“Deposited where?”
“Into a checking account ending in 4418.”
My checking account ended in 2207. I had never had an account ending in 4418.
PART 2 — Twenty-Six Years
I started at Lakeside Precision Castings in 1997, when I was thirty-seven. Before that, I’d bounced between three different factories that either closed or moved overseas. Lakeside felt different. It was family-owned back then, run by old Mr. Harlan Pierce and his son. They knew every employee’s name.
I worked the pour line for twelve years, then moved up to shift supervisor. My knees aren’t what they used to be, and I have a scar on my left forearm from 2003 that Bonnie calls my “tattoo.” But I was proud of that job. We made engine parts that went into trucks all over America.
In 2016, the Pierce family sold the company to a private equity group out of Chicago. Things changed. New managers. New software. More paperwork. A new controller named Brad Kessler came in to run the finance office. He was younger, sharp, always in a pressed shirt. He gave a presentation at a plant meeting about “modernizing our benefits administration.”
Linda Okafor had been in the benefits office since 2004. She was the one who walked every new hire through their 401(k) enrollment, explaining the company match on a whiteboard with colored markers. She remembered your kids’ names and asked about your mother’s surgery.
If you had asked me, the day of my retirement party, who I trusted most in that whole building, I would have said Linda.
So when Brittany at the plan administrator emailed me the loan documents that afternoon, I had to read the name three times.
Every one of the seven hardship loan requests had been processed and approved by the plan’s internal benefits coordinator.
Linda Okafor.
Each request listed a reason. “Medical expenses.” “Prevent eviction.” “Funeral costs.” Each one had an electronic signature that said “Earl R. Whitfield.” Each one listed an email address I had never seen before.
Bonnie read over my shoulder. “Earl, you don’t even use email except for the church newsletter.”
“I know,” I said.
I looked at the dates. The first loan was in March 2019. The last was eight months before my retirement. Seven loans. $279,000. Plus the taxes and penalties the system had withheld.
I thought about the lemon bars, and Linda crying at the door.
PART 3 — The Pause on the Line
That evening, I called the plan administrator back. This time I asked for a supervisor. A man named Gordon came on the line. He had obviously been briefed, because he spoke very carefully.
“Mr. Whitfield, we’ve flagged your account for investigation,” he said. “We’ll need you to sign an affidavit stating that you didn’t request these loans.”
“I’ll sign it tonight.”
“Thank you. We’ll also be notifying the plan sponsor, which is Lakeside.”
I asked him the question I had been thinking about all afternoon.
“Does Linda Okafor still work there?”
“I believe she’s still listed as the plan’s benefits contact, yes.”
“Gordon,” I said, “are there other employees with the same kind of loans? Hardship loans, deposited into accounts they don’t recognize?”
There was a long pause on the line. Long enough that I checked my phone to see if the call had dropped.
Then Gordon said, quietly and carefully, “Sir, I think you need to speak with someone above me.”
“Who?”
“Please hold.”
The hold music played for almost four minutes. Bonnie sat across from me at the kitchen table, twisting her wedding ring.
Then a different man came on the line. His voice was calm, deep, and professional.
“Mr. Whitfield, my name is Marcus Bell,” he said. “I’m a senior investigator with the U.S. Department of Labor, Employee Benefits Security Administration. I’ve been expecting your call.”
I didn’t understand. “Expecting me? I only found out today.”
“I know,” he said. “Your name has been on a list in my office for about four months.”
I put my hand over the phone and looked at Bonnie. “It’s the federal government,” I whispered.
“Mr. Whitfield,” Marcus Bell continued, “I’d like to meet with you in person. Tomorrow, if possible. And I’d ask you not to contact anyone at Lakeside about this until we’ve spoken. Including Linda Okafor.”
“Is Linda the one who did this?”
There was another pause.
“I’d rather talk about that in person,” he said.
PART 4 — The Federal Building
The Department of Labor’s office was in a federal building in downtown Indianapolis, two hours south of Fort Wayne. Bonnie insisted on coming. We left at six in the morning and stopped at a Cracker Barrel, though neither of us could eat much.
Marcus Bell was in his fifties, tall, with gray at his temples and a manner that made me think of the good teachers I had in high school. He brought us into a small conference room with two other people: a younger investigator named Alicia Romero and an attorney from the Labor Department.
He opened a binder and turned it toward me. It was a spreadsheet with about forty names. I recognized most of them. Every one of them was a long-time Lakeside employee within five years of retirement.
“Fourteen of these people have unauthorized hardship loans like yours,” he said. “Total losses are approximately $2.1 million, over five years.”
I sat there staring at the names. Pete Dombrowski from the cleaning room. Sharon Yates from shipping. Ray Teller, who worked next to me on the pour line for eleven years.
“How did you find out?” I asked.
Marcus closed the binder. “We received a confidential complaint last spring from someone inside Lakeside. The complaint came with documentation. Login records. Copies of loan requests. Deposit account numbers.”
“Who sent it?”
He looked at me for a long moment. “Mr. Whitfield, I’m going to tell you, because she has given us permission to, and because I think you deserve to know.”
He slid a single sheet of paper across the table. It was the cover page of the complaint. The signature at the bottom was neat and familiar.
Linda Okafor.
I read it twice. Then I looked up. “But her name is on all the loans.”
“Her name is on the approvals,” Marcus said. “Because someone was using her login credentials. Linda noticed last year that her approval queue had items she didn’t remember processing. She started keeping a private record. When she realized what it was, she came to us.”
Bonnie put her hand over her mouth.
“Then who?” I asked.
Marcus didn’t answer right away. He just turned to the next tab in the binder. It was an organizational chart for Lakeside Precision Castings. One box had been circled in red ink.
Controller: Bradley Kessler.
PART 5 — Lemon Bars
Marcus explained it carefully, the way you explain things to a man who has worked with his hands his whole life and never had a reason to understand fraud.
When Brad Kessler “modernized” the benefits system in 2018, he set himself up as an administrator with access to employee login credentials, including Linda’s. He created fake email addresses for employees close to retirement, people who rarely logged into their accounts. He submitted hardship loan requests in their names, approved them using Linda’s credentials late at night, and directed the money into checking accounts he had opened through a shell company.
“He picked people he thought wouldn’t notice,” Marcus said. “People who trusted the company and didn’t check online.”
“But I checked my statements every quarter,” I said.
“Paper statements?” Marcus asked.
“Yes.”
He nodded. “He changed the mailing address on the accounts to a P.O. box. You were receiving statements he created himself, printed to look exactly like the real ones.”
I felt sick. I had sat at my kitchen table every quarter for five years, proudly reading numbers that a man in a pressed shirt had typed up to fool me.
“Why didn’t Linda tell me?” I asked. “She was right there at my party.”
“Because we asked her not to,” Marcus said. “She came to us in February. We needed time to build the case, trace the money, and make sure Mr. Kessler didn’t destroy evidence or leave the country. She’s been going to work every day for eight months, sitting thirty feet from him, knowing what he did. Pretending everything was normal.”
I thought about Linda hugging me at the door. Crying a little. I had thought she was being sentimental about an old coworker retiring.
“She knew,” I said. “At my party. She knew my money was gone.”
“She knew,” Marcus said gently. “She told me afterward it was one of the hardest days of her life. She said she wanted to tell you so badly she had to leave early.”
Bonnie was crying quietly beside me. I didn’t trust my voice for a while.
“What happens now?” I finally asked.
“Now,” Marcus said, “we move.”
PART 6 — The Morning They Came
Two weeks later, on a Tuesday morning, federal agents arrived at Lakeside Precision Castings with a search warrant.
I wasn’t there, of course. But Ray Teller called me at ten o’clock, so excited he could hardly get the words out.
“Earl, the agents are here! Jackets and everything! They walked Kessler right out the front door past the time clock! Everybody stopped working and watched!”
“Was anybody hurt?” I asked.
“No, no, he went quiet as a lamb,” Ray said. “But here’s the thing. Linda Okafor walked out right behind them with one of the agents, carrying a box. People thought she was in trouble too, until the plant manager called a meeting.”
I learned later that the plant manager stood on a pallet in the middle of the shop floor and told everyone that Linda was the reason the scheme had been discovered. The whole plant gave her a standing ovation.
Later that afternoon, my phone rang. The caller ID said “L. Okafor.”
I answered. For a few seconds, neither of us said anything.
“Earl,” she finally said, and her voice broke. “I’m so sorry. I’m so sorry I couldn’t tell you.”
“Linda,” I said, “you don’t have anything to be sorry for. You did what nobody else had the courage to do.”
She cried, and I let her. She told me about finding the first strange loan in her queue, a hardship request for Sharon Yates for “funeral costs” when Sharon’s mother was very much alive and bowling on Thursdays. She told me about printing login records at five in the morning before anyone arrived. About driving to Indianapolis on a sick day to meet a federal investigator in a coffee shop.
“I was so scared, Earl,” she said. “I have two kids in college. If I was wrong, I’d lose my job. If I was right and didn’t say anything, I’d lose myself.”
“Well,” I said, “you were right.”
“I know,” she said softly. “But you still lost your money.”
“Not yet,” I said. “Marcus Bell says we might get it back.”
PART 7 — ERISA
I learned more about federal retirement law that fall than I ever wanted to know.
A lawyer from the Labor Department explained it to a group of us in the union hall, using a whiteboard and colored markers, the way Linda used to explain enrollment to new hires.
Most private company 401(k) plans are covered by a federal law called ERISA, the Employee Retirement Income Security Act. Under ERISA, people who manage a retirement plan are fiduciaries. They have a legal duty to act solely in the interest of the participants. And plans are generally required to carry a fidelity bond, a kind of insurance that protects the plan against theft or fraud by people who handle plan money.
“Mr. Kessler was a fiduciary,” the lawyer said. “He breached that duty in the worst possible way. But the company also had a duty to monitor him, and it failed. That gives us several paths to recovery.”
Pete Dombrowski raised his hand. “In plain English, ma’am. Are we getting our money back?”
The lawyer smiled. “In plain English, Mr. Dombrowski, we’re going to try very hard.”
The process took nine months. Federal agents traced and froze more than $900,000 in Kessler’s accounts, a vacation property in Michigan, and a boat. The plan’s fidelity bond insurer paid its maximum. And the private equity group that owned Lakeside, facing a federal lawsuit and terrible publicity, agreed to a settlement with the Labor Department.
Under the settlement, the company had to restore every affected participant’s account to what it would have been, including the investment earnings we would have made if the money had never been stolen. They also had to cover the taxes and penalties that had been wrongly withheld, and pay for an independent fiduciary to oversee the plan for five years.
I was at the kitchen table when the letter came. Bonnie read it out loud because my hands were shaking.
“Restored account balance as of the restoration date: $361,412.”
It was more than I had started with. The stolen money had been restored along with the growth it would have earned.
Bonnie set the letter down and kissed the top of my head. “Twenty-six years,” she said. “You earned every penny.”
PART 8 — The Hearing
Brad Kessler pleaded guilty in federal court to embezzlement from an employee benefit plan and wire fraud. The sentencing hearing was in May, in the same federal building in Indianapolis where I first met Marcus Bell.
The judge allowed victims to give statements. Six of us did. Sharon Yates. Pete Dombrowski. Ray Teller. Three others. And me.
I’m not a speaker. I wrote my statement on a legal pad and read it word for word, with my reading glasses sliding down my nose.
“My father retired from a foundry with a gold watch and nothing else,” I read. “I promised myself I would do better for my wife. For twenty-six years, I did everything right. You took that from me with a few clicks at midnight. You chose us because you thought we were too old and too trusting to notice. You were almost right.”
Kessler looked at the table the whole time. He didn’t turn around.
Then I said the part I had added at the last minute.
“But you didn’t count on Linda Okafor. You thought because her name was on the loans, she’d be blamed. Instead she risked her job, her family’s security, and her peace of mind to protect people she didn’t have to protect. You took our money. She gave us back our trust.”
Linda was sitting in the second row. She put her hand over her heart.
The judge sentenced Kessler to seven years in federal prison and ordered full restitution. Outside the courthouse, Marcus Bell shook my hand.
“Mr. Whitfield,” he said, “can I give you some advice for the rest of your retirement?”
“Please.”
“Log in online once a month. Set up text alerts for any withdrawal or loan. Make sure your mailing address is correct every year. And if anything ever looks off, call the plan administrator directly, not your employer.”
“I’ll do that,” I said. Then I added, “Marcus, thank you.”
He smiled. “Don’t thank me. Thank Linda. Every case I’ve ever won started with one brave person who refused to look away.”
PART 9 — The Second Retirement Party
That summer, Bonnie and I threw a party in our backyard. We invited everyone from Lakeside whose account had been hit, and their spouses, and a few people from the Labor Department who were allowed to come.
We called it the “Second Retirement Party.” Bonnie made a banner with red letters that said “Thank You, Linda!” and hung it across the back fence.
Linda didn’t know. Her husband told her they were going to a barbecue at “some friend of Earl’s.” When she walked through the side gate and saw the banner, she stopped so suddenly that her husband walked into her.
Forty people stood up and clapped. Linda stood frozen with her hand over her mouth.
Sharon Yates walked up to her first and hugged her. Then Pete. Then Ray. Then one by one, everyone in the yard.
When it was my turn, I handed her a tray covered in foil.
“Bonnie made these,” I said. “From your recipe. You gave it to her at my party, remember?”
Linda lifted the foil. Lemon bars. She laughed and cried at the same time.
“I almost didn’t bring any to your retirement party,” she said. “I thought, how can I hand that man lemon bars when I know what’s happened to his money? Then I thought, maybe it’s the only kind thing I’m allowed to do right now.”
“It was the right thing,” I told her. “It’s the only thing I remember clearly from that day.”
Later that evening, after most of the guests had gone home, Linda and I sat on the back porch while Bonnie and Linda’s husband argued good-naturedly about the Colts.
“What are you going to do now?” I asked her.
“Lakeside offered me a promotion,” she said. “Director of Benefits Compliance. I’ll report to the independent fiduciary, not to the finance office. Nobody will ever have access to my login again.”
“Good,” I said.
PART 10 — Still There
Linda looked out at the yard, at the banner sagging a little on the fence. “Earl, can I tell you something? When I came to Lakeside in 2004, I almost quit after the first month. I thought benefits work was just paperwork. Then you came into my office with your first grandson’s birth certificate and asked me how to add him as a beneficiary. You were so proud. I realized every one of those papers was somebody’s whole life.”
I didn’t know what to say to that, so I didn’t say anything. I just handed her another lemon bar.
Some people protect your money. A few people protect your faith that the world is still mostly decent. Linda did both.
In the months that followed, a lot changed at Lakeside. Every employee now receives an email and a text alert for any loan, withdrawal, or address change on their account. Paper statements are mailed only from the plan administrator, never from the company. Twice a year, Linda holds a free workshop in the break room called “Know Your Number,” where she teaches employees how to log in, read their statements, and set up alerts. Attendance is mandatory for anyone within ten years of retirement.
Ray Teller retired that fall with a fully restored account. Sharon Yates used part of her restored savings to take her eighty-four-year-old bowling mother on a cruise to Alaska. Pete Dombrowski bought a fishing boat and named it “The Fiduciary,” which he insists is funny.
As for me, I finally did what I planned to do three weeks after my first retirement party. I set up a modest monthly withdrawal, enough to cover our bills alongside Social Security, with the rest left alone to keep growing. Bonnie and I took our first real vacation in fifteen years, a week in the Smoky Mountains, where I sat on a cabin porch every morning and did absolutely nothing.
My advice to anyone reading this is simple. Don’t trust paper alone. Log in. Look at your actual account, on the official website, at least once a month. Set up alerts. Ask questions when something looks strange. And if you ever work somewhere and see something that isn’t right, remember Linda.
These days, I log in to my 401(k) on the first of every month. Bonnie sits beside me with her coffee. When the balance comes up on the screen, we both look at it for a moment in silence, and then she always says the same thing.
“Still there, Earl.”
And I always answer, “Thanks to Linda.”