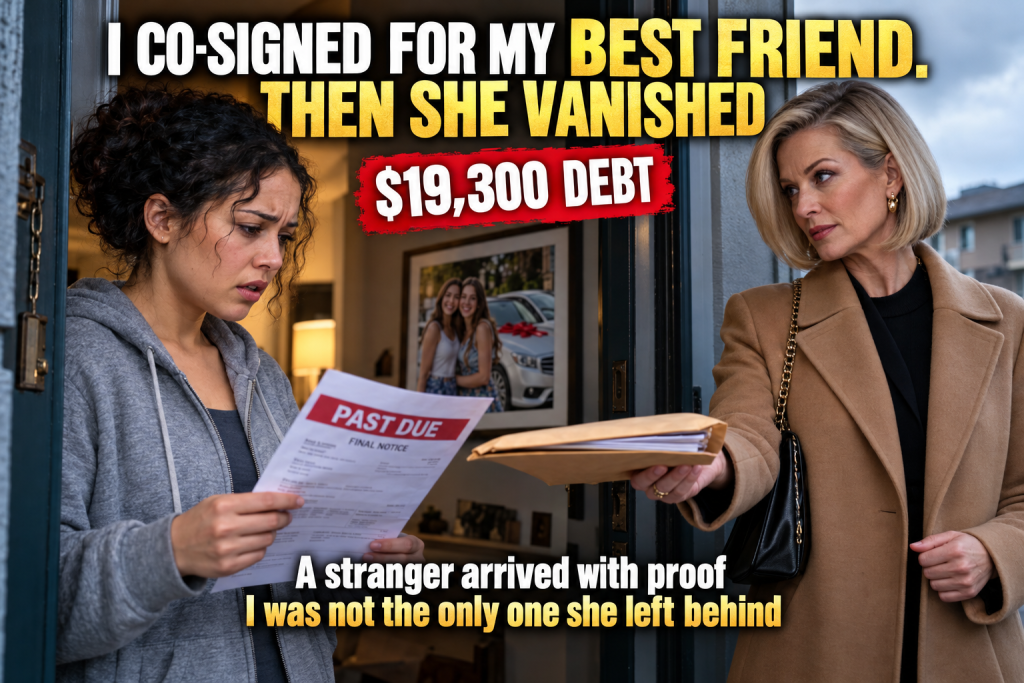
One signature for a lifelong friend seemed like the kindest favor I could give. Three years later it cost me my dream home, my credit, and a debt of nineteen thousand dollars I never spent. My friend vanished without a word. Then a polished stranger arrived on my porch with an envelope and proof that I was not the only person she had left holding the bill.
PART 1 — The Loan Officer’s Desk
The loan officer’s name was Gary, and he had the kind of gentle voice people use at funerals. He slid my credit report across his desk at the credit union on Oak Street and tapped a line halfway down the page with his pen.
“Ms. Calloway, this is the problem,” he said. “There’s an auto loan in collections. Nine months delinquent. You’re listed as co-borrower.”
I was thirty-two. I had saved for four years for a down payment on a two-bedroom house on Linden Avenue with a lemon tree in the backyard. I had brought my pay stubs, my tax returns, and a folder labeled “HOUSE” in purple marker. I had a credit score of 768 the last time I checked.
Now it was 628.
“That can’t be right,” I said. “I don’t have a car loan. I drive a 2014 Corolla that’s paid off.”
Gary turned the report so I could read it. Honda Civic. Original balance $27,500. Remaining balance $19,300. Primary borrower: Marisol Reyes. Co-signer: Jenna Calloway.
It took me a full five seconds to remember. Then the memory hit me so hard I put my hand flat on the desk.
Three years earlier, in the spring I turned twenty-nine, my best friend Marisol had just finished her dental hygiene program. She had a job offer at a practice forty minutes away. Her old car had died in the school parking lot. Her credit was thin because she had spent two years in school working part-time at a coffee shop. She asked me to co-sign.
I didn’t even hesitate. I signed the papers at a dealership on Route 9 while she bounced on her toes beside me. She cried and hugged me and said, “I will never, ever make you regret this.”
For three years I never thought about it again. I assumed she was making her payments, because Marisol had always kept her promises.
“The lender has already sent the account to a collection agency,” Gary said. “They are pursuing the co-signer for the full balance. Until this is resolved, I can’t approve the mortgage. I’m sorry.”
I walked out to my car with my purple folder and sat in the parking lot for almost an hour. I didn’t call my mother. I didn’t call my boyfriend. I called Marisol.
The call didn’t ring. A recorded voice said the number was no longer in service.
PART 2 — Friends Since Second Grade
Marisol Reyes and I met on the first day of second grade at Jefferson Elementary in Fresno, California. She was the new girl with two long braids and a Lisa Frank folder, and she sat down next to me at lunch and offered me half of her tamale. I gave her my pudding cup. That was the whole negotiation. We were best friends for the next twenty-two years.
We survived middle school together. We went to prom with each other when neither of our dates worked out. When my father passed away during my sophomore year of college, Marisol drove four hours in the rain and slept on the floor of my dorm for a week.
If you had asked me to list the people I trusted completely, Marisol would have been second, right after my mother.
That’s why co-signing had felt like nothing. It wasn’t a financial decision. It was a friendship decision.
After she got the Honda, life moved forward. She worked at a family dental practice in Clovis. I got promoted to office manager at an insurance agency. We met for tacos every other Friday. Then, about a year and a half after the car, things started to change in small ways.
She started canceling our Fridays. She said work was crazy. She got a new boyfriend, a man named Trent Waller who sold “financial wellness programs” and wore loafers without socks. I met him twice. Both times he talked about passive income and asked what my credit score was, like it was a normal question.
I told Marisol I didn’t like him. That was our first real argument in twenty years. She said I was jealous. I said I was worried. She said she was a grown woman.
After that, our texts got shorter. Then they got further apart. About eight months before my mortgage appointment, she texted me a photo of a sunset and the words, “Miss you. Things are complicated. I’ll explain soon.”
She never explained.
Sitting in the credit union parking lot, I scrolled back through our messages. The last one from her was five months old. A heart emoji under a picture of my birthday cake.
I called her mother, Mrs. Graciela Reyes, who had fed me dinner a thousand times. She answered on the third ring. When I said Marisol’s name, there was a long silence.
Then she said, very carefully, “Jenna, mija, I can’t talk about where Marisol is.”
PART 3 — Eleven Phone Calls
Over the next two weeks, I called Marisol’s old number eleven times. I don’t know why. Maybe I thought the recording would change.
I searched every social media account I knew she had. All of them were deleted. Her LinkedIn was gone. The dental practice in Clovis told me she had stopped working there “over a year ago” and that they couldn’t share anything else.
Meanwhile, the collection agency found me. They called my cell phone at eight in the morning and again at six at night. A man named Kurt explained that because I had co-signed, I was legally responsible for the full remaining balance and that if I didn’t set up payments, they would consider further action.
“I didn’t know she stopped paying,” I told him. “No one ever notified me.”
“Ma’am, the lender mailed notices to the address on file for the primary borrower,” Kurt said. “Co-signers aren’t always notified separately. That’s in the contract.”
I pulled out my copy of the contract that night. He was right. On page four, in small type, was a sentence I had never read. Something about the co-signer accepting full responsibility without requiring the lender to first pursue the borrower.
I had signed a promise I hadn’t read for a friend I thought I knew. That was the honest truth, and it stung.
My boyfriend, Daniel, sat with me at the kitchen table while I stared at the numbers. He’s a high school chemistry teacher and the calmest person I know.
“Okay,” he said. “So what do we actually know?”
“We know Marisol stopped paying nine months ago. We know her phone is disconnected. We know her mother is scared to talk about her.”
“Scared,” Daniel repeated. “Not angry. Not embarrassed. Scared.”
I hadn’t noticed that until he said it.
“And we know about Trent,” he added.
I pulled up Trent Waller’s name online. His “financial wellness” website was gone too. But I found an old Facebook post from a local community group, almost a year old, from a woman warning people about “a man named Trent who offers credit coaching and asks you to bring co-signers.” Several people had commented. One of them said, “He did this to my niece.”
I took a screenshot. Then I made a decision that felt silly at the time. I wrote down everything I knew in a notebook, with dates, like a detective. If I was going to pay for this mistake, I at least wanted to understand it.
PART 4 — The Woman With the Envelope
Six weeks after the loan officer, on a Saturday morning, someone knocked on my apartment door. I was in sweatpants, eating cereal out of the box.
The woman on the other side of the door was about fifty, with a sleek blonde bob, a camel wool coat, and the posture of someone who used to run meetings. She was holding a thick manila envelope against her chest.
“Are you Jenna Calloway?” she asked.
“Yes,” I said cautiously.
She looked at me for a moment, almost kindly. “You’re the one who signed for the Honda, aren’t you?”
I didn’t say anything. I didn’t need to. She nodded as if I had answered.
“My name is Diane Whitaker,” she said. “I’m a retired middle school principal from Visalia. And I signed for something too. For the same woman.”
“What did you sign for?” I asked. She held up the envelope. “A house,” she said. “A lot bigger than a car.”
I invited her in. I don’t know why I trusted her so quickly, except that she looked as tired as I felt.
Diane sat at my small kitchen table and opened the envelope. Inside were copies of mortgage documents, a deed, and bank letters. Two years earlier, she had co-signed a $212,000 mortgage on a small house in Fresno. The primary borrower was Marisol Reyes.
“How did you even know her?” I asked.
“I didn’t, really,” Diane said. “I met her through a financial seminar my sister dragged me to. The man running it was Trent Waller. He said he helped young professionals buy homes by pairing them with ‘mentors’ who had strong credit. He said Marisol was his best student. She was lovely. Sincere. She brought me banana bread.”
“And then she stopped paying.”
“Fourteen months ago,” Diane said. “The bank started foreclosure in the spring. I’ve been paying the mortgage myself to save my own credit. I’m on a fixed pension. I can’t keep doing it.”
I looked at the documents. The address of the house was one I knew. It was four blocks from where Marisol’s mother lived.
“How did you find me?” I asked.
Diane pulled out one last sheet of paper: a credit application Marisol had filled out for the mortgage. Under “existing debts,” she had listed the Honda. Under “co-signer on existing debt,” she had written my name and my old phone number.
“I found your address through the county records,” Diane said. “I thought you might know where she is.”
“I don’t,” I said. “I thought you might.”
PART 5 — The House Four Blocks Away
That afternoon, Diane and I drove to the house on the deed. It was a small yellow ranch with peeling trim and a dead lawn. A foreclosure notice was taped inside the front window. The driveway was empty.
“Nobody’s lived here for months,” Diane said.
We walked four blocks to Mrs. Reyes’s house. I had been there a hundred times as a kid. The porch still had the same blue flower pots. I rang the bell, and my heart was pounding so hard I could feel it in my throat.
Mrs. Reyes opened the door. When she saw me, her face crumpled. When she saw Diane, she went pale.
“I know who you are,” she said to Diane quietly. “Marisol told me about you.”
She let us in. The living room still had the same plastic-covered couch. Mrs. Reyes sat down heavily and folded her hands.
“She’s not hiding from you because she doesn’t love you,” she said to me. “She’s hiding because she’s ashamed. She thinks you’ll never forgive her.”
“Where is she?” I asked.
Mrs. Reyes looked at the floor. “Sacramento. She’s working at a dental office under her middle name. She sends me money every month. She told me if you ever came, I should give you this.”
She went to the kitchen and came back with a sealed envelope with my name on it, in Marisol’s round, bubbly handwriting that hadn’t changed since middle school.
I opened it right there on the plastic couch, with Diane watching.
It was a letter, three pages long. Marisol wrote that Trent had convinced her to let him “manage” her finances to build wealth. He set up an online account where her paychecks were deposited and her bills were supposedly paid. He told her the car and the house were investments. He told her the mortgage would be refinanced, that Diane would be “released” within a year.
Instead, he had been moving the money out. By the time Marisol realized the car payments had stopped and the mortgage was behind, there was almost nothing left in the account. Trent had moved to Arizona. He had also taken the Honda.
“I didn’t know how to tell you,” Marisol wrote. “I signed your name into this mess. I couldn’t face you. Every day I meant to call. Every day I was more ashamed than the day before.”
At the bottom of the last page, she had written a phone number.
PART 6 — The Call to Sacramento
I didn’t call that night. I needed to be sure that when I heard her voice, I wouldn’t say something I couldn’t take back.
Diane and I sat in her car outside Mrs. Reyes’s house and talked for an hour. She told me she had been married thirty years and widowed four. She told me she had co-signed for Marisol because she had always wanted to help a young woman the way someone once helped her.
“I’m angry,” Diane said. “But I’m angrier at that man. Marisol made terrible choices. He made a plan.”
The next morning, with Daniel sitting beside me, I called the number.
It rang twice. Then I heard her. “Hello?”
I said, “Mari. It’s me.”
There was a sound like someone sitting down hard. Then she started crying, and I started crying, and for a full minute neither of us said a single word.
When she could finally speak, the first thing she said was, “I’m so sorry, Jenna.” The second thing was, “Please don’t hang up.”
I didn’t hang up. I listened. She told me about Trent, about the account, about the morning she logged in and saw a balance of $63. She told me she had moved into a rented room in Sacramento, gone back to work under her middle name so Trent couldn’t find her easily, and started sending what she could to her mother to hold.
“How much do you have?” I asked.
She hesitated. “About nine thousand. I was saving it to pay you back first. I just didn’t know how to start.”
“Did you report Trent?”
“No,” she whispered. “I didn’t think anyone would believe me. I signed everything myself.”
Daniel slid a piece of paper across the table to me. He had written, in his neat teacher handwriting: “Ask her if she’ll come here and fix it together.”
“Mari,” I said, “Diane Whitaker is sitting in a house she can’t afford to save, and I’m sitting here with a credit score that cost me a home. You can’t fix this alone, and neither can we. Will you come home next weekend and face it with us?”
There was a long pause.
“Yes,” she said. “I’ll come.”
PART 7 — Three Women and a Kitchen Table
Marisol drove down the following Saturday. When she knocked on my door, she looked thinner and older than thirty-two. She was holding a box of conchas from the panadería we used to go to after school.
I didn’t hug her right away. I wanted to. But I needed her to see that this was serious.
Diane came over an hour later with her envelope. The three of us sat at my kitchen table with Daniel making coffee and pretending not to listen.
Marisol didn’t make excuses. She told Diane everything she had told me, and then she said something I didn’t expect.
“I kept every email from Trent,” she said. “I didn’t delete anything. I was too scared to read them again, but I kept them.”
She opened her laptop. There were hundreds of messages. Instructions to bring “mentors” to seminars. Templates for co-signer pitches. A spreadsheet that listed people’s credit scores. Diane’s name was on it. So was mine. So were nine other names.
Diane put on her reading glasses and leaned in. “This,” she said slowly, “is not a love story gone wrong. This is a business.”
We spent the whole day making a plan.
First, Marisol would file a police report and a complaint with the state attorney general’s consumer protection office about Trent’s “mentoring program,” and include the spreadsheet. Diane knew a retired attorney from her church who agreed to help for free.
Second, Marisol would contact the auto lender herself, as the primary borrower, and report the car as taken by Trent. She would offer her $9,000 in savings as a lump-sum settlement toward the balance and ask the lender to release me as co-signer once it was paid.
Third, for Diane’s mortgage, Marisol would sign a deed-in-lieu agreement, giving the house back to the bank in exchange for the bank stopping the foreclosure and not pursuing Diane for the rest of the debt.
“It won’t erase everything,” Diane said. “But it stops the bleeding.”
Marisol looked at me across the table. “What do you need from me, Jenna? Not the bank. You.”
I thought about the twenty-two years. The tamale and the pudding cup. The week she slept on my dorm room floor.
“I need you to stop disappearing,” I said. “Whatever happens next, you answer when I call.”
“I will,” she said. “I promise.” And for the first time in three years, I believed her.
PART 8 — Paper Trails
Paperwork is slow, and for the next four months it ruled my life.
The auto lender’s recovery department was skeptical at first. But Marisol sent them Trent’s emails and a copy of the police report. They located the Honda through its registration; Trent had sold it to a used car lot in Phoenix for cash. The lender couldn’t get the car back, but the report mattered.
In the end, the lender accepted $11,500 as a full settlement of the $19,300 balance. Marisol paid $9,000. I paid the remaining $2,500 from my house fund. It hurt, but it was much less than nineteen thousand. The lender agreed to report the account as “settled” and to update my status.
Diane’s case took longer. The bank’s first answer was no. Her attorney friend, a soft-spoken man named Howard Pell, wrote a letter on paper so thick it looked like a wedding invitation. The second answer was “under review.” The third answer, in early spring, was yes. The bank accepted the deed-in-lieu and released Diane from further liability.
When Diane got the letter, she drove straight to my apartment and read it to me out loud on the sidewalk, like a principal announcing the honor roll.
Meanwhile, the attorney general’s office called. It turned out Marisol’s spreadsheet matched two other complaints they had already received. Trent Waller’s seminar business had been operating under three different names in two states.
In June, an investigator called Marisol and asked her to give a formal statement. She did it on a Tuesday, sitting in a gray office for four hours. She called me afterward from her car.
“They asked me why I didn’t come forward sooner,” she said. “I told them the truth. I was too ashamed to admit I’d been fooled.”
“What did they say?”
“They said that’s exactly what people like Trent count on.”
That night, I pulled my credit report again. The auto loan now showed as settled. My score had already climbed back to 701. Not 768. But moving in the right direction.
Daniel put a sticky note on the refrigerator with the number on it, and every month after that he crossed it out and wrote the new one.
PART 9 — The Hearing in Phoenix
In October, nearly a year after the loan officer’s desk, the state of Arizona brought a civil consumer fraud case against Trent Waller and his companies. Marisol, Diane, and I were all asked to submit declarations. Marisol and Diane were asked to appear.
I took two days off work and drove with them.
The hearing room was smaller than I expected. Trent sat at a table with his attorney, wearing his loafers without socks. He didn’t look at any of us.
When it was Marisol’s turn, she walked to the front of the room with her shoulders back. She told the judge about the seminars, the “mentors,” the managed account, and the morning she found $63 in it. Her voice shook once, and then it steadied.
“I trusted the wrong person,” she said. “And because I did, two people who trusted me paid for it. I can’t undo that. But I can tell the truth now.”
Diane went next. She talked about her pension, her late husband, and the banana bread. She held up the spreadsheet with her name on it and said, “He didn’t see a person. He saw a credit score.”
The judge’s decision came three weeks later. Trent’s companies were ordered to pay restitution to the identified victims and were banned from offering credit or financial coaching services in Arizona. His attorney filed an appeal on paperwork grounds, and it was dismissed in the spring.
The restitution was not huge, because Trent had spent or hidden most of what he took. But in February, a check arrived in my mailbox from the state’s restitution fund for $2,480. Almost exactly what I had paid from my house fund.
I stood at the mailbox and laughed until I cried.
Diane received a larger check, enough to cover most of the mortgage payments she had made while trying to save her credit. She called me and said, “I’m buying myself a new mattress, and I am not apologizing to anyone.”
Marisol received nothing, because she had been the primary borrower. But when I called to tell her about my check, she didn’t sound disappointed.
“Good,” she said. “That money was always yours.”
PART 10 — The Lemon Tree
Eighteen months after the day Gary slid that credit report across his desk, I sat in the same credit union office with the same purple folder. My credit score was 742. Daniel sat next to me holding my hand under the desk.
Gary smiled at me, the first real smile I had seen from him. “Ms. Calloway, you’re approved.”
The house on Linden Avenue had sold to someone else long ago. But there was another one three streets over, with a smaller kitchen and a bigger backyard. And in the corner of that backyard, there was a lemon tree.
Sometimes the universe gives you the same thing, just a little later, after you’ve learned what it cost.
We closed in April. Diane came to the housewarming with a potted rosemary plant and a laminated copy of her bank’s release letter, which she said she was framing for her own living room. She and I have lunch once a month now. She calls me “my fellow co-signer,” and we both laugh.
Marisol came too. She had moved back to Fresno and taken a job at a pediatric dental office under her own full name. She rents a small apartment near her mother and is rebuilding her credit one secured card payment at a time. She showed me her score on her phone like it was a report card. It was 612. Two years ago it had been 498.
“Not bad for a fool,” she said.
“You weren’t a fool,” I said. “You were lied to by a professional. There’s a difference.”
We still meet for tacos every other Friday. She is always early now. She told me once that being early is her way of saying she will never disappear again.
I have thought a lot about whether I would co-sign for someone again. The honest answer is no, not the way I did it. If someone I love needs help, I’ll sit down with them and read every page. I’ll ask to be notified directly about missed payments. And I’ll ask myself whether I could afford to pay the full amount if everything went wrong. Because that is what co-signing really means.
But I learned something more important than a financial rule. Trust doesn’t break all at once. It breaks quietly, through shame and silence. And sometimes it can be rebuilt the same way, quietly, one honest conversation at a time.
On the first Friday in our new house, Marisol brought conchas from the panadería, and we sat under the lemon tree and split one in half. She took the bigger piece. I let her.
Some things haven’t changed since second grade.