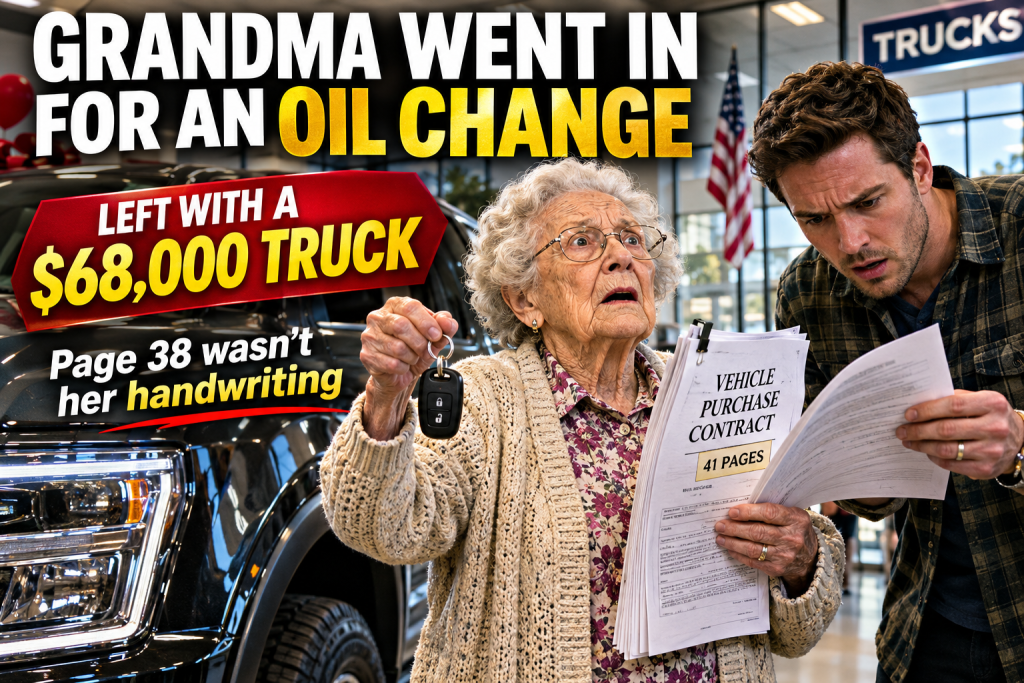
Grandma is 88 and five foot one. She went in for an oil change, and a salesman kept bringing her coffee for six hours. She came home with a $68,000 truck on a seven-year loan at 14% interest, with a $1,240 payment from a $1,680 Social Security check. I teach economics, so I read all forty-one pages. Page thirty-eight stopped me cold right at her kitchen table.
PART 1 — AN OIL CHANGE
My grandmother, Ruth Ann Dobbins, is eighty-eight years old and five foot one in her church shoes. She lives alone in a little yellow house in Knoxville, Tennessee, where she raised four children. She drives a 2011 Buick LeSabre that she bought new and has kept spotless for thirteen years. It has forty-one thousand miles on it.
Grandma takes very good care of that car. She gets the oil changed every three months, on the dot, at the same dealership where she bought it. She likes going there. The waiting room has free coffee and doughnuts, and the service manager used to call her “Miss Ruth” and ask about her grandkids.
Last fall, on a Tuesday morning in October, she drove to the dealership for her regular oil change.
She came home that evening driving a brand-new pickup truck.
A giant, shiny, black, four-door pickup truck. With chrome wheels, a lifted suspension, and running boards that came up past her knees.
Her next-door neighbor, Mr. Haskins, watched her pull into her driveway. He told me later that it took her almost five minutes to climb down out of the driver’s seat. She had to use the door handle and the steering wheel and finally just slide down sideways onto the running board.
He called me right away. “Jessica,” he said, “your grandma just came home in a truck that’s bigger than my garage.”
I’m Grandma’s granddaughter. I’m thirty-six. I teach economics at a public high school in Knoxville. I teach teenagers about interest rates, loans, and contracts every day.
I drove over that night. Grandma was sitting at her kitchen table with a cup of tea and a thick folder of papers, looking exhausted and confused.
“I just wanted an oil change,” she said. “I don’t know how this happened.”
I sat down across from her and looked at her hands. They were trembling a little around the teacup. She looked smaller than I’d ever seen her, sitting there with that folder of papers she couldn’t make sense of. My grandmother raised four children through two recessions on a cafeteria worker’s salary. She doesn’t get confused about money. Something had happened at that dealership.
I just wanted an oil change. I don’t know how this happened.
PART 2 — SIX HOURS
I sat down next to her and asked her to tell me everything, from the beginning.
She said she arrived at the dealership at nine in the morning. She checked in for her oil change and went to sit in the waiting room. While she was waiting, a young salesman came over and introduced himself. His name was Brandon. He was very friendly. He brought her a coffee and a doughnut.
He asked about her Buick. He told her it was getting old and might not be safe much longer. He said the dealership was running a special trade-in event, and they could give her a great price for her car. He asked if she’d like to “just look” at some newer models while she waited.
Grandma said no, thank you. She was happy with her Buick.
Brandon kept talking. He brought her another coffee. He told her about safety features and backup cameras. He said her grandchildren would feel better knowing she was in something safer. He said she deserved something nice after all these years.
Somewhere along the way, her oil change was finished. But Brandon told her they were “running some numbers” and asked her to wait a few more minutes. Then a few more. Then a manager came over and talked to her. Then a man from the finance office.
She was at the dealership for six hours.
She hadn’t eaten lunch, except for the doughnuts. She’d had three cups of coffee. She was tired. Her back hurt from the waiting room chairs. She said she kept asking for her keys, and they kept saying, “Just a few more minutes, Miss Ruth.”
“Finally I just wanted to go home,” she said. “They kept putting papers in front of me. I signed whatever they pointed to. I just wanted to go home.”
I signed whatever they pointed to. I just wanted to go home.
PART 3 — THE NUMBERS
I opened the folder and started reading. I teach this for a living. I know what these documents are supposed to look like. And I felt sicker with every page.
The truck’s price was sixty-eight thousand dollars.
The loan was for eighty-four months. That’s seven years. Grandma will be ninety-five when it’s paid off, if she lives that long.
The interest rate was fourteen percent. Grandma has an excellent credit score. She’s never missed a payment in her life. With her credit, she could have gotten a much lower rate.
Then the add-ons. A three thousand nine hundred dollar extended warranty. Two thousand four hundred dollars of “paint and fabric protection.” Eighteen hundred dollars of “theft deterrent window etching,” where they engrave the vehicle identification number on the windows. GAP insurance. A tire and wheel protection plan. A key replacement plan.
All of it rolled into the loan, with fourteen percent interest on top.
And her Buick, which was worth around eight thousand dollars in good condition, had been taken as a trade-in for three thousand dollars.
The monthly payment was one thousand two hundred forty dollars.
I knew Grandma’s finances. I help her with her taxes every spring. Her Social Security is sixteen hundred eighty dollars a month. She has a small pension from her years as a school cafeteria worker, and a modest savings account.
After her truck payment, she’d have about four hundred dollars a month left for everything else. Her food. Her medicine. Her electric bill. Her property taxes. Her homeowner’s insurance.
“Grandma,” I said carefully, “do you know how much your monthly payment is?”
She shook her head. “Brandon said it was very affordable,” she said.
The monthly payment was one thousand two hundred forty dollars. Her Social Security is sixteen hundred eighty.
PART 4 — FORTY-ONE PAGES
I counted the pages in the folder. There were forty-one.
Forty-one pages for an eighty-eight-year-old woman to sign after six hours in a dealership waiting room.
I went through them one by one. The buyer’s order. The retail installment sales contract. The odometer statement. The title application. The warranty contracts. The add-on agreements. The privacy notices. The credit application.
Grandma’s signature was on every one. Shakier and shakier as the pages went on.
The credit application listed her income. It said she made four thousand two hundred dollars a month. Grandma makes about two thousand, total, from Social Security and her pension. Someone had more than doubled her income on the form.
“Grandma, did you tell them you make four thousand dollars a month?”
“No,” she said. “Nobody asked me how much I make.”
I kept going. Page thirty-six. Page thirty-seven.
On page thirty-eight, there was a form I’d never seen before in a car deal. It was a one-page document titled “Customer Acknowledgment.” It said that the dealership had offered the customer the opportunity to have a family member or trusted advisor review the purchase documents before signing, and that the customer had declined.
At the bottom, in handwriting, someone had written: “I decline. I understand all terms. Ruth A. Dobbins.”
I looked at it for a long time. Then I took out Grandma’s checkbook register from her kitchen drawer and compared the handwriting.
Grandma writes in careful, old-fashioned cursive, the kind they taught in the 1940s. The handwriting on page thirty-eight was print. Neat, fast, and slanted. It wasn’t her handwriting.
On page thirty-eight, someone had written: I decline. I understand all terms.
PART 5 — WHAT GRANDMA REMEMBERED
“Grandma,” I asked, “did you write this?”
She put on her reading glasses and looked at it. She frowned. “No,” she said. “I signed my name. But I didn’t write that.”
“Did anyone ask you if you wanted to call a family member?”
She thought about it. Then her face changed.
“Yes,” she said slowly. “The finance man asked if I wanted to call someone. I said yes. I said I wanted to call you. He said that was fine, but it would take a long time to redo all the paperwork, and the special pricing would be gone by tomorrow. He said I’d have to come back and start over.” She paused. “I was so tired, Jessica. I just said never mind.”
She had said yes. She had asked to call me. And somebody had written on a form that she declined.
I sat at Grandma’s kitchen table that night and made a list.
A truck she didn’t need and could barely climb into. A seven-year loan for an eighty-eight-year-old woman. An inflated interest rate. Thousands of dollars in add-ons. A trade-in value far below what her car was worth. An income on the credit application that wasn’t true. A form saying she declined to call her family, in handwriting that wasn’t hers.
And six hours in a waiting room.
I teach my students about predatory lending. I never imagined I’d have to explain it to my own grandmother.
The next morning was Wednesday. I called in a substitute for my classes. Then I put Grandma’s folder in my bag, drove her to the dealership in her new truck, and asked to see the general manager.
I said I wanted to call you. He said the special pricing would be gone by tomorrow.
PART 6 — THE GENERAL MANAGER
It took Grandma almost two minutes to climb down from the truck in the dealership parking lot. I helped her. A few salesmen watched from the showroom window.
The general manager was a man in his fifties named Rick Haynes. He came out of his office, saw Grandma, and immediately put on a big smile. “Miss Ruth! How are you enjoying your new truck?”
“I can’t get in it, Rick,” Grandma said. “I’m five foot one.”
I introduced myself and explained, politely, that we wanted to return the truck and cancel the contract.
His smile got a little smaller. He explained that in Tennessee, there’s no “cooling off” period for car purchases. Once you sign the contract and drive the car off the lot, the sale is generally final. He said he was sorry, but there was nothing he could do.
That’s true, as far as it goes. Many people believe they have three days to return a car. In most states, including Tennessee, that isn’t the law.
But I had more to say.
I took out the credit application and laid it on his desk. I pointed to the income: four thousand two hundred dollars a month. I laid her Social Security statement next to it. Sixteen hundred eighty dollars.
Then I took out page thirty-eight. I laid it next to Grandma’s checkbook register. Her cursive. And the printed words, “I decline. I understand all terms.”
“My grandmother asked to call me,” I said. “Your finance manager told her she’d lose the deal. Then someone wrote on this form that she declined. This isn’t her handwriting. And this isn’t her income.”
Rick Haynes looked at the papers for a long time. He stopped smiling.
“Let me look into this,” he said. “Can you give me until Friday?”
Rick Haynes’s office had a big window that looked out over the lot. While he talked, I could see the truck sitting right outside, gleaming in the sun, with the running boards that came up past Grandma’s knees.
My grandmother asked to call me. Then someone wrote on this form that she declined.
PART 7 — FRIDAY
On Friday, I didn’t wait for Rick Haynes to call. I’d spent two evenings doing my homework.
I’d filed a complaint with the Tennessee Attorney General’s Division of Consumer Affairs. I’d filed a complaint with the federal Consumer Financial Protection Bureau about the loan. And I’d called a consumer protection lawyer, a woman named Teresa Blankenship, who had handled cases against car dealers before.
Teresa explained that while there’s usually no cooling-off period for car purchases, a contract based on false information or deceptive practices can be challenged. Inflating a buyer’s income on a credit application can be a serious problem, especially if the buyer didn’t provide that information. Misrepresenting what a customer agreed to can be a problem too. And when the customer is elderly, states often take these issues even more seriously.
She also pointed out something I hadn’t thought of. The loan had been sold to a finance company. Under a federal rule, consumers can often raise the same claims against the finance company that they could raise against the dealer.
“Let the dealer know you have a lawyer,” she said. “And let them know you’ve filed complaints. Dealers care very much about their relationships with lenders and regulators.”
On Friday morning, I emailed Rick Haynes a short letter. It said that we had retained counsel, that we had filed complaints with the Attorney General and the CFPB, and that we were requesting that the contract be canceled and the transaction reversed.
He called me forty minutes later.
“Ms. Dobbins,” he said, “we’ve reviewed your grandmother’s file. We’d like to make this right.”
Let the dealer know you have a lawyer. Dealers care very much about their relationships with lenders and regulators.
PART 8 — MAKING IT RIGHT
The next week, Grandma and I went back to the dealership. Teresa came with us.
The dealership agreed to cancel the entire transaction. They took the truck back. They canceled the loan with the finance company. They canceled every add-on. And they returned Grandma’s Buick to her, with a fresh oil change, a full tank of gas, and a new set of floor mats. She was so happy to see it that she patted the hood.
They also gave her a written letter confirming that the loan had been canceled and would not appear on her credit report.
Rick Haynes told us that the salesman, Brandon, and the finance manager no longer worked at the dealership. He said an internal review had found “irregularities” in several other files involving elderly customers. He wouldn’t say how many.
The Tennessee Attorney General’s office later contacted me. They had received other complaints about the same dealership. Their investigation found a pattern of inflated income on credit applications and pressure tactics used on older customers, many of whom came in for routine service. The dealership eventually entered into an agreement with the state, paid a civil penalty, refunded affected customers, and agreed to new rules for sales to elderly buyers.
Teresa also helped two other families I’d heard about through church, whose parents had similar stories with the same dealership. One was an eighty-two-year-old widower who went in for a tire rotation and came out with a seventy-thousand-dollar SUV. His deal was canceled too.
When it was all over, Grandma drove home in her Buick. I followed behind her. She drove exactly the speed limit, with both hands on the wheel, the way she’s driven for seventy years.
When I told Grandma that night, she cried a little. Then she called Mr. Haskins next door and told him the giant truck was gone for good. He said he’d been worried she’d back it through his fence.
She was so happy to see her Buick that she patted the hood.
PART 9 — MY CLASSROOM
The following Monday, I went back to my classroom and threw out my lesson plan.
I have about a hundred and forty students, mostly seniors. Most of them will buy their first car in the next few years. So I told them Grandma’s story. All of it. The oil change. The six hours. The forty-one pages. Page thirty-eight.
Then I handed out copies of a real car buyer’s order and retail installment contract, with all the names and numbers changed, and asked them to find everything that was wrong.
They found it all. The inflated income. The add-ons. The seven-year term. The interest rate. One girl in the back row raised her hand and said, “Ms. Dobbins, why would an eighty-eight-year-old need a seven-year loan?”
“That’s exactly the right question,” I said.
It was the best class I’ve ever taught. Several students went home that night and looked at their own parents’ car loans. Two of them found add-ons their parents didn’t know they’d paid for. One family got a refund on a warranty they never wanted.
At the end of the year, my students voted on the most useful thing they’d learned in my class. “Grandma’s truck” won by a landslide.
I told Grandma. She laughed so hard she had to put down her teacup.
“Well,” she said, “at least somebody learned something from that mess. I sure did.”
“What did you learn, Grandma?”
She thought about it. “Bring a sandwich,” she said. “And never let them keep your keys.”
Bring a sandwich. And never let them keep your keys.
PART 10 — WHAT EVERY FAMILY SHOULD KNOW
Here’s what I teach my students now, and what I want every family with older relatives to know.
In most states, there’s no cooling-off period for buying a car. Once you sign and drive away, it’s usually final. So don’t sign anything you haven’t read, and don’t sign anything the same day if you feel pressured.
Never let a dealer keep your keys. If you’re there for service and someone starts a sales pitch, you have the right to say no and leave. If they won’t return your keys, ask for the manager. You’re the customer.
Bring someone with you. Or call someone before you sign anything. If a salesperson says the deal will disappear if you take time to think, walk away. A good deal will still be there tomorrow.
Read the credit application. Make sure your income and other information are correct. If someone fills it in for you, check it before you sign. Never sign a form with information you didn’t provide.
Watch out for add-ons. Extended warranties, paint protection, window etching, and other extras are usually optional. Ask what each one costs and whether you can decline it.
Check the loan term and the interest rate. A longer loan means a lower monthly payment, but much more interest. For older buyers, a seven-year loan rarely makes sense.
And if something goes wrong, act quickly. Call the dealership’s general manager. File complaints with your state Attorney General and the CFPB. Talk to a consumer lawyer. You may have more options than you think.
Grandma still drives her Buick. She still gets her oil changed every three months. But now she goes to a small independent mechanic down the street from her house. He doesn’t sell cars.
And she always brings a sandwich.
Never sign a form with information you didn’t provide.