Dad went to a free steak dinner about protecting his savings, and a month later his whole $310,000 401(k) was in an annuity he could not touch without penalty until age 94. His doctor gives him maybe five years. The advisor made almost $22,000. I work in bank compliance, so I pulled his record and the forms. Someone had checked his health as excellent.
PART 1 — A FREE STEAK DINNER
My father, Walter Brooks, is eighty-four years old. He worked for thirty-eight years as an engineer at a paper mill in Green Bay, Wisconsin. He never made a lot of money, but he saved steadily, every paycheck, into his company’s 401(k) plan. By the time he retired, he had built up about three hundred and ten thousand dollars. It was his safety net, along with Social Security. It was supposed to last him the rest of his life.
Dad is a careful man. He reads the newspaper front to back every morning. He balances his checkbook. He doesn’t trust anything that sounds too good to be true. Or at least, he didn’t.
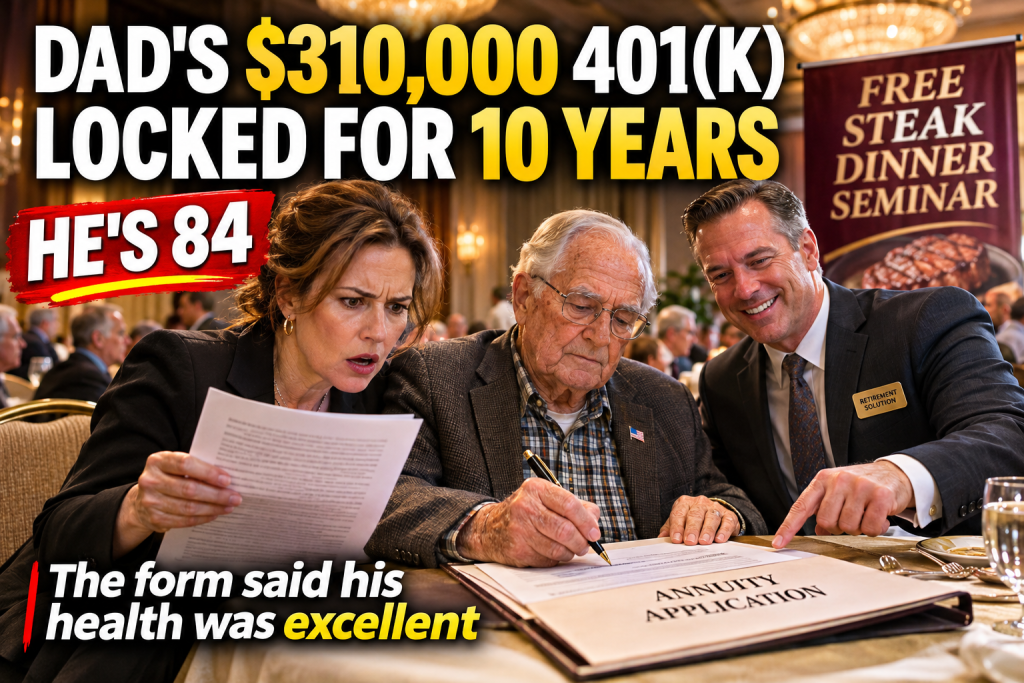
Last year, he got a glossy invitation in the mail. “You’re invited to a complimentary dinner seminar: Protecting Your Retirement in Uncertain Times.” It was at a nice hotel near his house. Filet mignon, the invitation said. No obligation.
Dad went with his friend Earl from church. They figured they’d get a good steak and a little free advice.
The speaker was a man in his forties named Bradley Kemper. He had a nice suit, a big smile, and a slideshow full of charts showing the stock market crashing. He talked about seniors losing half their savings in 2008. He talked about inflation and rising healthcare costs. He said that people Dad’s age couldn’t afford to take risks anymore. Then he said there was a product that guaranteed you’d never lose a penny.
An annuity.
He invited everyone to schedule a free one-on-one review of their retirement accounts. Dad signed up.
I’m his daughter, Nicole. I’m fifty-three. I live in Milwaukee, about two hours south. I work as a compliance officer at a regional bank. My job is to make sure our bank follows the laws and regulations that protect customers, including the rules about selling investment products to older people.
I didn’t know about the dinner until it was too late.
He said there was a product that guaranteed you’d never lose a penny.
PART 2 — THE MEETING
Dad met with Bradley Kemper twice in the following month, at a small office in a strip mall. Bradley was patient and friendly. He went through Dad’s 401(k) statements. He asked about Dad’s health. He asked about Mom, who died in 2016. He asked about me and my brother.
At the second meeting, Bradley recommended that Dad move his entire 401(k), all three hundred ten thousand dollars, into an annuity. He said it would grow safely and provide guaranteed income. He said Dad would never have to worry about the stock market again. He said it was “the safest place for your money at your age.”
Dad signed the paperwork that day.
He mentioned it to me on the phone a few weeks later, almost in passing. “I moved my retirement into one of those annuities,” he said. “Very safe. Guaranteed. The young man was very helpful.”
My stomach dropped. In my job, I see annuity complaints all the time. Annuities aren’t automatically bad. For some people, in some situations, they make sense. But they are complicated, often expensive, and they’re one of the most common products in complaints about unsuitable sales to older people.
I asked Dad to send me copies of everything he’d signed. He mailed me a thick envelope a week later. More than sixty pages.
I read them at my kitchen table on a Sunday afternoon. And I felt physically sick.
The annuity Dad bought was a type called a deferred indexed annuity. It had a ten-year surrender period. That means if Dad took out more than a small percentage of his money in any year before the ten years were up, he would pay a penalty. The penalty started at ten percent and went down slowly over a decade.
Dad was eighty-four. He wouldn’t be free of the penalty until he was ninety-four.
He said it was the safest place for your money at your age.
PART 3 — THE PROBLEM WITH TEN YEARS
Here’s what made it so much worse. My father has congestive heart failure. He was diagnosed three years ago. His cardiologist has been honest with him, and with us. With his condition, he might have three to five good years left. Maybe more, if he’s lucky. Maybe less.
He’s going to need money for his care. Home health aides. Maybe assisted living, which in Wisconsin can cost six thousand dollars a month or more. Medical bills that Medicare doesn’t cover. That’s exactly what his 401(k) was for.
Now almost every dollar of it was locked inside a product that would penalize him for using his own money when he needed it most.
I kept reading. On page twelve, I found the fees. There was an annual charge for an optional income rider. There were caps on how much the annuity could earn in a good year. By the time I added everything up, the “guaranteed growth” Bradley had promised was very modest.
Then I found the commission disclosure. Annuity salespeople are often paid a commission by the insurance company. For this product, the commission was about seven percent of the amount invested.
Seven percent of three hundred ten thousand dollars. Almost twenty-two thousand dollars.
Bradley Kemper earned twenty-two thousand dollars for two meetings with my father in a strip mall office.
I called Dad. I didn’t want to scare him, but I had to ask. “Dad, did he ask you about your health?”
“Oh, yes,” Dad said. “I told him all about my heart. He was very sympathetic. He said his own father had heart trouble.”
“Did he ask when you might need to use the money?”
“I told him I might need help at home someday. Or a place like your mother’s friend Margaret is in.” He paused. “He said not to worry. He said I could always get to my money in an emergency.”
Bradley Kemper earned twenty-two thousand dollars for two meetings with my father.
PART 4 — HIS RECORD
The next morning, I did what I would do for any customer complaint at work. I looked up Bradley Kemper’s professional record.
Anyone can do this. Insurance agents are licensed by the states, and most state insurance departments let you search for agents online. If an agent also sells securities, the Financial Industry Regulatory Authority, known as FINRA, has a free public tool called BrokerCheck.
Bradley Kemper was licensed to sell insurance in Wisconsin. I searched his name in the national insurance regulators’ database. And I found a sanction.
Five years earlier, the insurance department in another state had taken action against him. According to the public order, he had sold annuities with long surrender periods to elderly customers for whom the products were not suitable, including at least one customer in hospice care. He’d paid a fine and agreed to additional supervision. Then, apparently, he had moved to Wisconsin and started over.
For doing exactly the same thing.
I sat at my desk at work and stared at my screen. I’d seen dozens of cases like this in my career. But this was my father.
That evening, I called Dad again and asked him to look for one more document. There’s a form that agents are generally required to complete when they sell annuities. It’s often called a suitability form. It records the customer’s age, income, assets, financial goals, health, and need for access to their money. Its whole purpose is to make sure the product fits the customer.
Dad found it in his file. He read parts of it to me over the phone. His age. His income. His assets. His “objective”: “growth and safety.”
Then he got to the box about health and liquidity needs. He read it twice.
“Client’s health status: Excellent,” he read. “Anticipated need for funds within ten years: None.”
Client’s health status: Excellent. Anticipated need for funds within ten years: None.
PART 5 — EXCELLENT
“Dad,” I said carefully. “Did you tell him your health was excellent?”
“No,” Dad said. He sounded confused. “I told him I had heart failure. I told him about my pills. I told him I get winded walking to the mailbox.”
“Did you fill out this form, or did he?”
“He did,” Dad said. “He asked me questions and typed on his computer. Then he turned it around and showed me where to sign. There were a lot of pages. He said they were standard.”
I asked him to send me a photo of that page. It was a computer-printed form. The checkboxes were filled in electronically. “Health status: Excellent.” “Anticipated need for funds within ten years: None.” “Client has other liquid assets to cover emergencies: Yes.”
Dad had about eight thousand dollars in his checking account. That was all.
At the bottom of the page was Dad’s signature. And next to it, Bradley Kemper’s.
I’ve reviewed hundreds of these forms at work. I know what they’re for. If Dad’s real health and his real need for money had been written on that form, it would have been very hard for anyone to justify selling him a ten-year annuity with all of his savings. So someone had written down a different man. A healthy eighty-four-year-old with plenty of other money and no plans to touch his retirement for a decade.
That man didn’t exist.
I went to see Dad that weekend. I sat with him at his kitchen table and explained everything as gently as I could. He listened quietly. He’s an engineer. He understood numbers. When I showed him the surrender schedule and the commission, he took off his glasses and rubbed his eyes.
“I thought I was being careful,” he said. “I went to protect my money. I went because I was afraid of losing it.”
I went to protect my money. I went because I was afraid of losing it.
PART 6 — THE COMPLAINT
I know exactly how complaints like this are handled, because I handle them at my own bank. So I knew what to do, and in what order.
First, I helped Dad write a formal complaint letter to the insurance company that issued the annuity. Insurance companies are responsible for supervising the agents who sell their products, and many have rules requiring them to review whether annuity sales to older customers are suitable. We asked them to cancel the contract and return Dad’s full premium, without any surrender charge. We explained his heart failure, attached a letter from his cardiologist, and included the suitability form with “Excellent” checked.
Second, we filed a complaint with the Wisconsin Office of the Commissioner of Insurance, which licenses and regulates insurance agents in the state.
Third, I made a copy of everything for Dad’s files, because I’ve seen too many cases where the paperwork mysteriously disappears.
Then we waited.
The insurance company’s first response was a polite form letter. It said that Dad had signed the suitability form, had received a free-look period during which he could have canceled for free, and had acknowledged the surrender charges in writing. It said they were “unable to grant a refund at this time.”
The free-look period is real. In most states, annuity buyers have a short window after purchase, often ten to thirty days, to cancel for a full refund. But Dad didn’t know what he’d bought until I read the paperwork, months later. The window had long since closed.
I was not surprised by the form letter. I see form letters every day. I also know that the first answer isn’t always the final one.
So I sent a second letter. This one included the public sanction against Bradley Kemper from another state. It pointed out that Dad’s cardiologist had documented his heart failure for three years before the sale. And it asked a very specific question: who checked the “Excellent” box?
Who checked the excellent box?
PART 7 — THE OTHER CUSTOMERS
The Wisconsin insurance regulator took our complaint seriously. An investigator named Janet Rourke called Dad and spent an hour on the phone with him. She was kind and patient. She asked him to describe both meetings in detail. Dad, the engineer, had notes. He keeps notes on everything.
A few weeks later, she called me. She couldn’t tell me everything, but she told me enough.
“Your father’s complaint isn’t the only one,” she said. “And the free dinner seminars are a pattern.”
Over the next several months, her investigation found that Bradley Kemper had held more than twenty free dinner seminars in northeastern Wisconsin over two years. He had sold annuities with long surrender periods to dozens of attendees, most of them in their late seventies and eighties. Investigators reviewed their suitability forms. Many had been filled out the same way. Health: Excellent. Need for funds: None.
One of them was a man in his late eighties with Parkinson’s disease. Another was a widow with stage four cancer. Another was Dad’s friend Earl, who went to the same steak dinner.
When Dad found out about Earl, he got angrier than I’d ever seen him. Not for himself. For his friend.
“Earl can barely see,” Dad said. “He’s got macular degeneration. He can’t read a menu. And that man had him sign sixty pages of paperwork.”
That night, Dad called Earl. Then he called four other men from church who’d been to Bradley’s seminars. He helped every one of them pull out their paperwork and look at the health box. Three of them had “Excellent” checked. None of them were in excellent health.
My eighty-four-year-old father, with heart failure, spent the next week driving around Green Bay with a folder, helping his friends write complaint letters.
Earl can barely see. He can’t read a menu. And that man had him sign sixty pages of paperwork.
PART 8 — THE REFUND
The insurance company called Dad in the spring.
They had reviewed his case again, along with the regulator’s investigation and the complaints from other customers. They had also reviewed Bradley Kemper’s sales. A representative from their compliance department, someone in a job a lot like mine, told Dad that the company had concluded the sale was not suitable for him.
They agreed to rescind the annuity completely. Every penny of his three hundred ten thousand dollars would be returned, with no surrender charge, plus interest. They would also handle the paperwork to roll the money back into a retirement account so Dad wouldn’t face any unexpected taxes.
Dad called me after the call. His voice was shaking a little. “They’re giving it all back, Nicole,” he said. “All of it.”
I cried at my desk. Again.
The company made similar offers to Earl and to many of Bradley Kemper’s other customers. They also terminated their relationship with him. The Wisconsin insurance regulator later revoked his license. I learned that the regulator’s final order found that he had misrepresented customers’ health and financial information on suitability forms, and that he had made misleading statements about access to funds.
Bradley Kemper hasn’t sold an annuity since, at least not in Wisconsin. I check the database every few months. Old habits.
When Dad’s money was back in his account, he asked me to help him find someone trustworthy to manage it. We found a fee-only financial planner, a person who is paid a flat fee by the client and not by commissions from selling products. She sat down with Dad, his cardiologist’s letter, and his real numbers. She built a simple plan around what he’d actually need.
It wasn’t exciting. But it was honest.
They’re giving it all back, Nicole. All of it.
PART 9 — EARL
The best part of this story isn’t about the money. It’s about Earl.
After the refunds came through, Dad and Earl went back to the same hotel where they’d had the steak dinner. They sat at the bar. They each ordered a filet mignon. They paid for it themselves.
Then Dad pulled out a little stack of index cards. He’d made them on his kitchen table, in his careful engineer’s handwriting. On one side, it said: “Before you sign anything, call your kids.” On the other side, it listed a few questions. How long is my money locked up? How much is your commission? Can I take this home and have someone else read it?
That evening, there was another free dinner seminar in the hotel ballroom. A different company, a different speaker. Dad and Earl finished their steaks, walked into the ballroom, and stood quietly in the back.
When the speaker finished and the seniors in the audience started lining up to schedule their free one-on-one reviews, Dad and Earl walked around the room handing out index cards.
The hotel manager eventually asked them to leave. They had handed out sixty cards by then.
Dad told me about it on the phone the next day, laughing harder than I’d heard him laugh in years. “Your old man got thrown out of a hotel,” he said. “At eighty-four. Your mother would have been so proud.”
“Dad,” I said, “you’re going to get yourself sued.”
“For what?” he said. “Telling people to call their kids?”
Before you sign anything, call your kids.
PART 10 — WHAT I TELL PEOPLE NOW
I’ve worked in banking compliance for twenty years, and I thought I knew how to protect my own family. I didn’t. Here’s what I’d want every family to know.
Be wary of free meal seminars about retirement. Some are legitimate and educational. Many are sales events. The free dinner is part of the pitch.
Before any older relative buys an annuity or moves retirement savings, ask about the surrender period. Ask what happens if they need the money in an emergency. Ask exactly how much the seller earns from the sale. They should tell you.
Look up the salesperson. Check your state insurance department’s licensing database. If they sell securities, check FINRA’s BrokerCheck. It’s free and takes five minutes.
Read the suitability form. Make sure the information on it is true. Health. Income. Assets. Need for access to money. If it isn’t true, don’t sign it.
Remember the free-look period. Most annuities can be canceled for a full refund within a short window after purchase. If something feels wrong, have someone you trust read the contract immediately.
And talk to your parents about money. I know it’s awkward. I know they’re proud. But my father, who is one of the smartest and most careful people I know, nearly lost his life savings to a man with a slideshow and a steak.
Dad is eighty-five now. His heart is about the same. Some days are good, some days are hard. He has a home health aide three mornings a week, paid for out of the money he almost lost. He keeps a stack of index cards by his front door.
Every time a new seminar invitation arrives in his mailbox, he writes “CALL YOUR KIDS” across it in red marker and mails it to me.
I have fourteen of them on my refrigerator.
If the information on the form isn’t true, don’t sign it.