I named my son as the account owner because he said it would make college paperwork easier. Caleb, the first in our family accepted to college, called me crying in July because Purdue rejected his tuition payment. My son said the market crashed and it was just bad luck. Then the investment company mailed me two years of withdrawals, and the last one landed the week before he bought a boat.
PART 1 — ROUTE 14
For thirty-one years, I drove a yellow school bus in Lafayette, Indiana. Route 14. Forty-two stops, from the trailer park on the south side to the farms out past the county line.
I knew every child by name. I knew who forgot their lunch, who had a dog that chased the bus, and whose parents were going through a divorce. I kept a box of granola bars under my seat for the kids who didn’t get breakfast. I kept a roll of Band-Aids in the glove box and a joke ready for every rainy Monday.
My name is Darlene Hughes. I’m seventy-four now. I retired in 2014 with a small pension, a plaque from the school district, and a drawing from a second-grader that said “Mrs. Hughes is the best bus driver in the hole world.” I still have it framed in my kitchen.
I raised one son, Brian, mostly on my own after his father left when Brian was six. We didn’t have much. We lived in a little two-bedroom house with a leaky roof and a garden full of tomatoes. But Brian never went to bed hungry, and he never missed a day of school.
Nobody in my family ever went to college. Not my parents. Not me. Not Brian. My father worked in a grain elevator. My mother cleaned houses. I drove a bus. Brian works at a car parts warehouse.
When my grandson Caleb was born, I opened a college savings account for him. A 529 plan.
Caleb rode my bus too, for a few years, before I retired. I wasn’t allowed to play favorites, so I made him sit in the back like everybody else. But every afternoon, when he got off at his stop, he’d turn around on the bottom step and say, “Bye, Grandma!” loud enough for the whole bus to hear. The other kids teased him. He never stopped.
I remember holding Caleb in the hospital, all seven pounds of him, and whispering in his tiny ear, “You’re going to college, baby. Grandma’s going to make sure of it.”
PART 2 — $100 A MONTH
I’d read about 529 plans in a newspaper article. They’re special college savings accounts. The money grows over the years, and if it’s used for college, it can be withdrawn without paying taxes on the growth.
I went to a bank in Lafayette and sat down with a nice young woman who helped me set one up.
I put in $100 a month for eighteen years.
It wasn’t easy on a bus driver’s salary. Then on a bus driver’s pension. Some months, $100 was the difference between paying my electric bill on time and paying it late. But I never missed a month. Not once.
I skipped vacations. I wore the same winter coat for eleven years. I clipped coupons and bought day-old bread. When my friends went to Florida for the winter, I stayed home and shoveled my own driveway.
Every birthday, I added a little extra. Every Christmas, I put in another $100 instead of buying Caleb another toy he’d outgrow. When I got a small tax refund, it went in the account. When I sold my late mother’s old sewing machine, that went in too.
With birthday money and Christmas money, it grew to $71,000.
I’m seventy-four. I’m a retired school bus driver. That account was the proudest thing I ever did.
Every January, when the statement came in the mail, I sat at my kitchen table with a cup of coffee and read every line. I’d smile at the number. Then I’d put the statement in a folder labeled “CALEB COLLEGE” in my filing cabinet.
Caleb was a smart boy from the start. He took apart my toaster when he was seven, just to see how it worked, and then put it back together. It still works. When he was twelve, he built a little robot out of an old remote-control car. I knew then he was going to do something big.
When Caleb was little, I’d show him the statement. “See this number?” I’d say. “That’s your future. Don’t you dare waste it.”
PART 3 — THE ACCOUNT OWNER
When I first opened the account, I was the owner. Caleb was the beneficiary.
Then, about ten years ago, Brian came to me with a suggestion.
“Mom,” he said, “you should make me the account owner. That way, when Caleb goes to college, I can handle the paperwork with the school. You won’t have to deal with it. And if anything ever happens to you, the account won’t get tied up.”
It made sense. I was getting older. Brian was Caleb’s father. And I trusted my son.
I named my son, Caleb’s father, as the account owner, because he said it would be easier for “paperwork” when Caleb went to college.
I signed the form at the bank. The young woman at the desk asked me if I was sure. She said the account owner controls the money. They can make withdrawals. They can change the beneficiary.
“He’s my son,” I said. “Of course I’m sure.”
After that, the statements went to Brian’s address instead of mine. I asked him about it a few times over the years. He’d say, “It’s doing great, Mom. Growing like crazy.” Once, he showed me a statement on his phone. I saw the number and smiled.
I kept putting in my $100 a month. I’d hand Brian a check, or later, he set up an automatic transfer from my bank account into the 529.
Looking back, there were little signs. Brian always changed the subject when I asked for the statement. He said it was “all online now.” Once, when I asked to log in myself, he said the password was complicated and he’d set it up for me “sometime.” He never did.
I never thought to ask for my own copy of the statements. Why would I? It was my son. I’d raised him. I’d driven him to school in that yellow bus every morning for six years.
PART 4 — PURDUE
Caleb got into Purdue last spring. Engineering. First in our family to go to college.
I’ll never forget the day the email came. Caleb drove over to my house in his beat-up Honda and ran up my front steps two at a time. He held out his phone with shaking hands.
“Grandma,” he said. “I got in. I got into Purdue.”
I read the email three times. Then I threw my arms around him and cried into his shoulder like a baby.
Purdue University. Thirty minutes from my house. One of the best engineering schools in the country. My grandson, the son of a warehouse worker and the grandson of a school bus driver, was going to be an engineer.
That night, I took him to dinner at the steakhouse on the edge of town. The fancy one with cloth napkins. I’d never eaten there in my life. I ordered a steak and a glass of wine, and I made the waiter take our picture.
“Grandma,” Caleb said, “I couldn’t have done this without you. That college fund means I won’t have to take out huge loans like my friends.”
“That’s what it was for, baby,” I said. “Eighteen years of it.”
Caleb’s mother had moved to Texas when he was small, and Brian had raised him with my help. Some weeks, Caleb practically lived at my house. I helped him with his math homework until he got too smart for me, which happened around seventh grade.
Caleb hugged me in the parking lot. “I’m going to build bridges, Grandma,” he said. “Big ones. And I’m going to put your name on one of them.”
PART 5 — THE PHONE CALL
In July, he called me crying.
It was a Tuesday afternoon. I was in my garden picking tomatoes. Caleb was so upset I could barely understand him.
The university said his tuition payment had been rejected.
He’d gone online to pay his first semester bill using the 529 account. His dad had given him the account information. But the payment was rejected for insufficient funds.
The 529 account was empty.
“Grandma, I don’t understand,” he said. “Dad said it was all there. Seventy thousand dollars. Where did it go?”
My knees went weak. I sat down in the dirt between my tomato plants.
I called Brian right away.
He was quiet for a moment. Then he said, very calmly, “Mom, I’ve been meaning to tell you. The stock market crashed. We lost most of it.”
“Lost it?” I said. “All of it?”
“It was just bad luck, Mom,” he said. “The market went down. These things happen. I’m sorry.”
I didn’t know much about the stock market. But I knew something didn’t make sense. I’d seen the news. There had been ups and downs, sure. But the market hadn’t crashed to zero.
“Brian,” I said, “how could seventy-one thousand dollars become nothing?”
He said he didn’t want to talk about it anymore. He said I was upsetting him. Then he said he had to go, and he hung up on me.
PART 6 — THE ACCOUNT HISTORY
I sat at my kitchen table that night with my “CALEB COLLEGE” folder. Eighteen years of statements, up until the year Brian became the owner. Every one of them showing the number going up.
I didn’t sleep.
The next morning, I asked the investment company for the account history.
I called the company that managed the 529 plan. I explained that I was the grandmother who had funded the account for eighteen years, and that I was worried something had happened to it.
The woman on the phone was polite but careful. She said she could only discuss the account details with the account owner. That was Brian.
But she said something helpful. She said I could request copies of records showing my own contributions to the account, since many of the deposits had come from my bank account. And she suggested that Caleb, as the beneficiary, might be able to request certain information too.
So Caleb and I sat down together and filled out the paperwork. I also went to my own bank and printed eighteen years of records showing every $100 I’d sent.
Two weeks later, a thick envelope arrived.
The money hadn’t disappeared in a crash. It had been withdrawn.
In nine separate withdrawals, over two years. $5,000. $8,000. $10,000. $6,500. Each one marked as a “non-qualified distribution.” That means the money wasn’t used for school. It was taken out for something else.
Each withdrawal had been sent to a bank account in Brian’s name.
Caleb came over every evening that week. He didn’t say much. He just sat with me on the porch while the fireflies came out. One night he said, “Grandma, if it’s gone, I’ll take out loans. I’ll work. It’s okay.” I told him it was not okay. Not after eighteen years.
I laid the pages out across my kitchen table in a row, the same way I used to line up permission slips on my bus. Nine withdrawals. Two years. Seventy-one thousand dollars.
PART 7 — THE BASS BOAT
I sat there for a long time, staring at the last withdrawal.
$12,000. Taken out in April.
Then I remembered something.
The last withdrawal was the week before my son bought a brand-new bass boat.
He’d posted pictures on Facebook. A shiny red and silver bass boat with a big outboard motor and his name painted on the side. “Living the dream!” he’d written. People had commented with thumbs-up emojis and fish emojis.
I had commented too. I’d written, “So proud of you, son!”
I looked at the date of the Facebook post. I looked at the date of the last withdrawal. Six days apart.
I went back through Brian’s Facebook page. A new pickup truck the year before. A trip to Las Vegas with his buddies. A big flat-screen TV.
I matched the dates. The truck was bought two weeks after a $10,000 withdrawal. The Vegas trip happened right after an $8,000 withdrawal.
Every single withdrawal lined up with something Brian bought.
I had to go outside and sit on my back steps. I couldn’t breathe in the kitchen anymore.
My son. My only child. The boy I raised by myself, the boy I drove to school every morning in my yellow bus. He had taken his own son’s college money, the money his mother saved for eighteen years, and spent it on a boat.
I printed every Facebook photo and wrote the date of each withdrawal at the top in red pen, just like I used to mark tardy slips. Then I put them in order. Looking at them all together, there was no mistaking it. My son had treated his boy’s future like a checking account.
And he had lied to me. Looked me in the eye and lied. “Just bad luck, Mom.”
PART 8 — THE LAWYER
I didn’t know what to do. I didn’t want to call the police on my own son. But I couldn’t let Caleb lose his chance at Purdue.
My friend Marlene, a retired school secretary, told me about a lawyer who helped seniors with financial problems. His name was Mr. Thomas Alvarez. He had an office downtown above a bakery, and the whole stairway smelled like cinnamon rolls.
I brought my folder. Every statement. Every bank record. The withdrawal history. Screenshots of Brian’s Facebook posts.
Mr. Alvarez read through everything carefully. Then he leaned back in his chair.
“Mrs. Hughes,” he said, “legally, your son was the owner of the account. That gives him a lot of control. But this money came from you, and you gave it for a specific purpose. There may be ways to recover it, depending on what was promised and what you can prove.”
He explained that we could file a lawsuit asking the court to require Brian to repay the money, based on the purpose of the gifts and his promises to me. He also explained that non-qualified withdrawals from a 529 come with taxes and a penalty, which Brian might not have even known about.
“Your son may be facing an IRS problem too,” he said.
Then he looked at me over his glasses.
Mr. Alvarez didn’t charge me for that first visit. “Bus drivers got my kids to school safely for twelve years,” he said.
“But Mrs. Hughes,” he said, “before we go to court, I think someone should talk to your son. Sometimes the threat of court is enough to make a person do the right thing.”
PART 9 — BRIAN
I went to see Brian myself. I brought Caleb with me.
We drove to his house on a Saturday morning. The bass boat was sitting on a trailer in his driveway, gleaming in the sun.
Brian opened the door. He saw Caleb. He saw my folder. His face fell.
I didn’t yell. I’d spent thirty-one years keeping order on a bus full of screaming children. I know how to make my voice heard without raising it.
I laid the withdrawal history on his kitchen table. Then the Facebook screenshots. The boat. The truck. The Vegas trip.
“Nine withdrawals,” I said. “Seventy-one thousand dollars. Eighteen years of my life.”
Brian started to cry. He said he’d lost his overtime at work. He’d gotten behind on bills. He told himself he’d pay it back before Caleb needed it. Then he bought the truck, and the boat, and he told himself he’d pay it back later.
“I’m sorry, Mom,” he said. “I’m so sorry, Caleb.”
Caleb didn’t say anything at first. Then he stood up.
“Dad,” he said quietly, “Grandma drove a bus for thirty-one years. She wore the same coat for eleven winters. She saved that money for me. And you bought a boat.”
On the drive home, Caleb was quiet for a long time. Then he said, “Grandma, I’m not going to hate him. But I’m never going to forget this either.” I told him that was the wisest thing I’d heard all year.
Brian put his face in his hands. Then he said, “I’ll sell it. I’ll sell everything. I’ll make it right.”
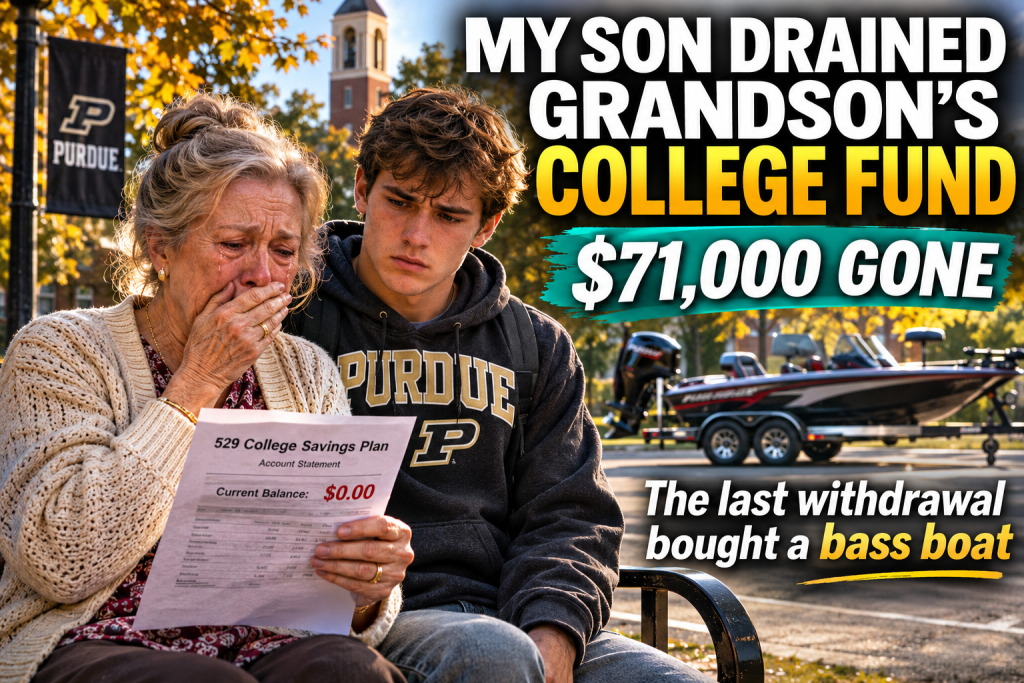
PART 10 — WHAT I WANT YOU TO KNOW
Brian sold the bass boat. He sold the truck. He took out a loan against his house. With Mr. Alvarez’s help, we signed a written agreement. Brian repaid the money into a new 529 account, and this time, I’m the owner. He also had to deal with the IRS over the taxes and penalties on his withdrawals.
Caleb started at Purdue in the spring semester, just one term late. He’s a sophomore now. He’s on the dean’s list. He calls me every Sunday night.
Brian and I are speaking again. It’s not the same. Maybe it never will be. But he comes to Sunday dinner, and last month he brought me a new winter coat.
I’m sharing this story because 529 plans and other college savings accounts can be misused when the wrong person controls them.
If you’re funding a 529 for a grandchild, think carefully about who should be the account owner. The owner controls the money.
Ask for your own copies of statements, or online access, so you can see the balance yourself.
If someone else is the owner, consider naming a successor owner you trust, and ask questions if anything changes.
If money disappears, request the account history right away, and talk to a lawyer.
And talk to your grandchildren about the money you save for them. Let them see the statements. It teaches them about money, and it gives you one more set of eyes.
I saved $100 a month for eighteen years so my grandson could be the first in our family to go to college. My son spent it on a boat and called it bad luck. The paperwork told the truth.
Last month, Caleb sent me a picture from his engineering class. He’s standing next to a small model bridge his team built.
On the side, in tiny letters, it says, “The Darlene Hughes Bridge.”