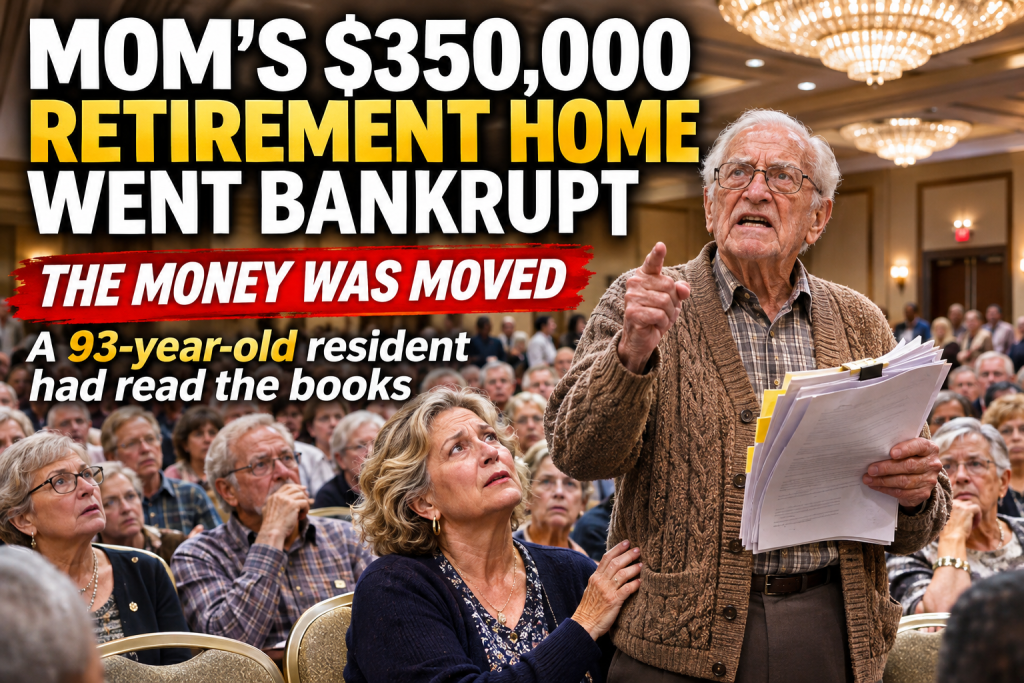
Mom and Dad sold their house and paid nearly everything they had for a lifetime of care, with ninety percent refundable if they left or died. Then the community filed for bankruptcy, and Mom, now eighty-nine, was told she might get nothing and feared being thrown out. At the first families’ meeting in a hotel ballroom, a ninety-three-year-old resident stood up holding a stack of papers.
PART 1 — FOR LIFE
In 2016, my parents, Robert and Jean Caldwell, made the biggest decision of their retirement. They sold the brick house in Greensboro, North Carolina, where they had lived for forty-one years, and moved into a beautiful retirement community in the rolling hills outside Raleigh.
It was called Heritage Oaks. It had everything. Cottages and apartments for independent living. An assisted living wing. A skilled nursing center. A dining room with white tablecloths, a heated indoor pool, a library, a woodshop for Dad, and a garden club for Mom. Walking trails along a little lake with ducks.
It was what’s called a continuing care retirement community. The idea is that you move in while you’re still healthy, and as you age and need more help, you move to assisted living or nursing care, right there on the same campus. Care for life. You never have to move again.
To live there, my parents paid an entrance fee of $350,000. On top of that, they paid a monthly fee for their cottage, meals, and services.
The entrance fee was nearly everything they had. It was the proceeds from selling their house plus most of their savings. But the contract promised that if they left or died, 90% of the fee would be refunded to them or their estate.
“It’s not like spending it,” Dad explained to me at their kitchen table, with the contract spread out in front of him. “It’s more like a deposit. We get security, and you kids get most of it back someday.”
Dad was a retired high school principal. Mom had been a church organist for thirty years. They were careful people. They read every page. They visited three times. They talked to residents. They said it was worth it for the security.
I’m Karen. I’m sixty-two, a nurse practitioner in Charlotte. My brother, Phil, lives in Virginia.
I remember the day they moved in. Dad stood on the porch of their little cottage overlooking the lake and said, “Well, Jeannie, this is the last address we’ll ever have.” Mom laughed and said, “Thank goodness. I’m too old to change my stationery again.”
PART 2 — THE GOOD YEARS
For five years, it was everything they hoped.
Dad joined the woodshop and built birdhouses for every grandchild. Mom played piano for the Sunday chapel service and started a garden club that won a ribbon at the state fair. They had friends for dinner every Friday night. They walked the lake trail every morning, holding hands.
When I visited, Mom would introduce me to everyone. “This is my daughter, the nurse practitioner,” she’d say, as if I’d won a Nobel Prize.
Then, in 2020, the pandemic came. The community locked down for months. No visitors. Meals delivered to the doors. Mom and Dad were lonely, but they were safe.
Dad died in 2021. Not from COVID. A heart attack, quietly, in his recliner, watching a basketball game. He was eighty-six.
After Dad died, Mom’s memory began to slip. Small things at first. Then bigger ones. In 2022, she moved into assisted living in the same community, just as the contract promised. She had her own apartment with a view of the lake. The staff knew her by name. She could still play the chapel piano on Sundays.
I told myself it was exactly what Dad wanted. Security. Care. No more moving.
I didn’t pay much attention to the business side of Heritage Oaks. Why would I? There were newsletters every month with pictures of the garden club and the Fourth of July picnic. The management sent cheerful letters about “exciting expansion plans,” including a new building with luxury apartments that was going up near the front gate.
I did notice a few things. The food got a little worse. The pool was closed for “repairs” for most of a year. Some of the longtime staff left, and the new aides didn’t stay long. Mom complained that her favorite nurse had quit.
I thought those were just pandemic problems. Everyone was short-staffed. Everyone was struggling. I had no idea Heritage Oaks was quietly coming apart.
PART 3 — THE LETTER
Last year, a letter arrived.
It came to me, because I had Mom’s power of attorney. A thick envelope from a law firm I’d never heard of.
The retirement community had filed for bankruptcy.
I read it three times sitting in my car in the hospital parking lot during my lunch break.
The letter explained that Heritage Oaks had filed for Chapter 11 bankruptcy protection. It said the community would continue operating during the bankruptcy process, and residents would continue to receive care. But it also listed the community’s debts. Banks. Bondholders. Contractors who built the new luxury building.
And residents.
The refund my parents were promised was now listed as an unsecured debt. Mom’s claim was listed at $315,000, the 90% refund. But unsecured creditors are near the bottom of the line in a bankruptcy. They get paid after secured lenders, if there’s anything left at all.
I called a bankruptcy lawyer that afternoon, a woman named Leslie Graham in Raleigh. She explained it to me plainly.
“Your mother is an unsecured creditor,” she said. “In many bankruptcies like this, unsecured creditors get a small percentage of what they’re owed. Pennies on the dollar. Sometimes nothing.”
“But she paid it as a deposit,” I said. “It was supposed to be refundable.”
“I know,” Leslie said gently. “Many families feel exactly that way. The contract says refundable. The bankruptcy code doesn’t always care.”
I sat in my car and cried. That $315,000 was everything Mom and Dad had saved in sixty years of marriage. It was what Dad meant when he said “you kids get most of it back someday.”
PART 4 — MOM
I drove to Heritage Oaks that weekend to tell Mom in person. I wasn’t sure how much she’d understand.
She understood more than I expected.
Mom is eighty-nine. Her memory comes and goes. But she knew the word bankruptcy. She’d lived through the Depression as a little girl in a mill town. Her father lost his job and their house in 1937.
“Bankrupt,” she said, gripping the arms of her chair. “Like the mill.”
“Not exactly like that, Mom,” I said. “They’re still open. You’re still here.”
“Will they throw me out?” she asked. “Where will I go? Your father isn’t here. I can’t live alone.”
“No one is throwing you out,” I said. I wasn’t actually sure that was true.
She cried for a week. The aides told me she stopped eating her meals. She stopped going to the chapel to play the piano. She kept asking the nurses whether she’d have to pack. Twice she was found at night in the hallway, in her robe, carrying a small suitcase. She said she was getting ready to leave before they made her.
She was terrified she’d be thrown out.
Phil drove down from Virginia. We sat together in Mom’s little apartment and tried to make a plan. If the worst happened, she could come live with me in Charlotte. But I work twelve-hour shifts. She needed round-the-clock care. Without the refund, we didn’t know how we’d afford a good assisted living somewhere else.
Phil was angry. “Somebody did something wrong,” he kept saying. “Places like this don’t just go broke. Somebody was taking money.”
“Maybe,” I said. “But how would we ever prove it?”
Then a notice came for the first meeting of residents and families with the bankruptcy attorneys. In a hotel ballroom in Raleigh. I almost didn’t go. I’m so glad I did.
PART 5 — THE BALLROOM
I’m 62. I went to the first meeting of residents’ families.
There were two hundred of us in a hotel ballroom near the Raleigh airport. Folding chairs in long rows. A podium at the front with two lawyers from the community’s bankruptcy firm and a man from the management company in a blue suit.
Some residents came too. Men with canes and walkers. Women in wheelchairs, pushed by their children. Everyone looked frightened and angry.
The man in the blue suit spoke first. He explained that the community had faced “unprecedented challenges.” The pandemic. Rising costs. Staffing shortages. Lower occupancy. The new luxury building had gone over budget. He said management had done everything it could. He said bankruptcy was the best way to keep the community open and protect the residents.
Then the lawyers explained the claims process. They said, carefully, that it was too early to know how much unsecured creditors like residents would receive.
A woman in the front row stood up and asked, through tears, whether her father would lose his room in the nursing center. The man in the blue suit said they were “committed to continuity of care.”
People started shouting. Someone yelled, “Where did the money go?”
Then an old man in the third row stood up.
He was tall and very thin, with white hair combed neatly back. He was 93, a resident, a retired accountant, wearing a cardigan and holding a stack of papers. He held onto the back of the chair in front of him to steady himself.
The room slowly got quiet.
His name, I learned later, was Mr. Walter Pierce. He had been a certified public accountant in Durham for forty-five years. He moved to Heritage Oaks in 2014 with his wife, who died in 2019.
He looked at the man in the blue suit for a long moment.
“I’ve read the books,” he said, in a clear, dry voice. “This community isn’t broke. The money’s been moved.“
PART 6 — MR. PIERCE
The ballroom went completely silent.
The man in the blue suit started to say something about “public financial statements.” Mr. Pierce held up his stack of papers.
“I have the public financial statements,” he said. “Every one since 2015. The community has to file them with the state of North Carolina every year, because it takes entrance fees. Anybody can request them. I did. I read them. All of them. Twice.”
He turned a page.
“In 2018, the community began paying a management fee to a company called Heritage Senior Management, LLC. That company is owned by the same people who own the community. The fee started at 4% of revenues. By 2022, it was 11%. Over five years, it totaled more than nineteen million dollars.”
He turned another page.
“In 2020 and 2021, while residents were locked in their apartments, the community made loans totaling eight million dollars to another company owned by the same people. A company building luxury apartments in South Carolina. Those loans have not been repaid. They are listed here as an asset, at full value, as if they will be.”
He looked up.
“And the reserve fund,” he said, “which the state requires to protect residents’ refunds, dropped from twenty-two million dollars in 2017 to under three million last year.”
He set the papers down.
“I have been an accountant for seventy years, counting the twenty I’ve been retired,” he said. “I know what it looks like when a business is failing. This one isn’t failing. It’s being emptied.”
Somebody in the back started clapping. Then somebody else. Then the whole ballroom, two hundred frightened families, stood up and applauded a ninety-three-year-old man in a cardigan.
PART 7 — THE RESIDENTS’ COMMITTEE
After the meeting, I found Mr. Pierce in the hotel lobby, sitting on a bench, catching his breath. His granddaughter was bringing the car around.
I introduced myself. I told him about Mom.
“Jean Caldwell,” he said. “The organist. She plays ‘Abide With Me’ every Sunday. My wife loved her playing.”
He handed me a business card. It was old and yellowed, from his accounting firm. On the back, he’d written a phone number in pen.
“There will be an official committee of unsecured creditors in this bankruptcy,” he said. “Residents are the biggest group of unsecured creditors. We need to be on that committee. And we need lawyers who work for us, not for management.”
In a Chapter 11 bankruptcy, a committee of unsecured creditors is often appointed. It has the power to investigate the debtor’s finances and hire its own lawyers and financial advisors, paid for by the bankruptcy estate.
Mr. Pierce asked to be appointed to the committee. So did I, on Mom’s behalf. So did a retired judge, a former bank examiner, and the daughter of a nursing home resident who happened to be a forensic accountant.
The committee hired its own attorneys and a financial advisory firm. Mr. Pierce gave them every page of his research. They told us later that his work had saved them months.
Their investigation confirmed what he had said. The management fees to the owners’ company. The unpaid loans to the owners’ other projects. The drained reserve fund.
The committee’s lawyers filed what’s called an adversary proceeding in the bankruptcy court, a lawsuit within the bankruptcy, asking the court to claw back the money that had been moved out of the community to the owners’ other companies.
Mr. Pierce attended every single hearing, in his cardigan, with his granddaughter pushing his wheelchair. The judge started greeting him by name.
PART 8 — THE STATE STEPS IN
The North Carolina Department of Insurance, which regulates continuing care retirement communities, opened its own investigation. Under state law, communities that take entrance fees must maintain certain reserves to protect residents.
The newspapers picked up the story. A local TV station interviewed Mr. Pierce in front of the lake. He said, “I’m not angry for myself. I’m ninety-three. I’m angry for the widows who sold their houses and handed over their life savings because someone promised them they’d never have to worry again.”
Families started calling their state legislators. I called mine three times.
The bankruptcy case took almost a year and a half.
In the end, under pressure from the committee’s lawsuit, the state investigation, and the bankruptcy judge, the owners agreed to a settlement. They returned a substantial portion of the money that had been moved out, including repaying much of the loans to their South Carolina company and giving up the management fees.
The community was sold to a large nonprofit senior living organization with a long, solid track record.
As part of the sale, the new operator agreed to honor all existing residents’ contracts for care. No one would be thrown out. Mom could stay in her apartment, with the same care, for the rest of her life.
And the refunds? Because of the clawbacks and the sale, the plan paid resident refund claims at about 78 cents on the dollar, with the new operator committing to pay the rest over time as apartments were resold.
Leslie Graham, my lawyer, called me the day the plan was approved.
“Karen, in twenty years of bankruptcy practice, I’ve never seen residents get anywhere near this much in a case like this,” she said. “That old man changed everything.”
PART 9 — TELLING MOM
I drove to Heritage Oaks the next morning to tell Mom.
She was in her apartment, sitting by the window, looking at the lake. I knelt beside her chair.
“Mom,” I said, “you’re not going anywhere. You’re staying right here. For good.”
She looked at me for a long time. I wasn’t sure she understood.
Then she said, “The suitcase. Can I unpack the suitcase?”
I hadn’t known she still had it packed. It was sitting in her closet, with three nightgowns, her Bible, Dad’s photo, and a little tin of peppermints inside. She’d kept it ready for a year and a half.
“Yes, Mom,” I said, my voice cracking. “You can unpack it.”
We unpacked it together. Nightgown by nightgown. She put Dad’s photo back on her nightstand, where it belonged.
The next Sunday, Mom played the piano at chapel for the first time in eighteen months. She played “Abide With Me.” Her hands were shaky, and she missed a few notes.
Mr. Pierce was in the front row in his wheelchair. When she finished, he applauded louder than anyone.
Afterward, I wheeled Mom over to meet him. She took his hand.
“You’re the man who read the books,” she said.
“And you’re the lady who plays the hymns,” he said. “My Margaret loved your playing. I think we’re even.”
Mom laughed. It was the first time I’d heard her laugh in a year and a half. Mr. Pierce laughed too. Two old people holding hands in a chapel, laughing.
PART 10 — WHAT I WANT YOU TO KNOW
Mr. Pierce died this spring, at ninety-five. His funeral was held in the chapel at Heritage Oaks. It was standing room only. Mom played “Abide With Me.” The new operator renamed the community library the Walter Pierce Library. His old stack of papers is in a glass case by the door.
Mom is ninety-one now. She still lives by the lake. She still plays the piano on Sundays, when her hands allow.
I’m sharing this story because many families are considering continuing care retirement communities, and many of them pay large entrance fees on the promise of a refund.
Read the contract carefully, and ask exactly how refunds are protected. Ask whether entrance fees are held in reserve, and how much.
Request the community’s annual financial disclosures. Many states require communities that take entrance fees to file them, and you may be able to get them from the state.
Watch for warning signs. Rising management fees paid to related companies. Big construction projects. Falling reserves. Cuts to staff and services.
And if a community you love files for bankruptcy, get involved. Go to the meetings. Ask about the creditors’ committee. Residents and families have more power together than they think.
My parents paid $350,000 for the promise that they’d never have to move again. When that promise nearly broke, it was a ninety-three-year-old man with a stack of papers who stood up and kept it for them.
The last time I visited, Mom pointed out the window at the ducks on the lake.
“Your father would like it here still,” she said. “This is our last address.”