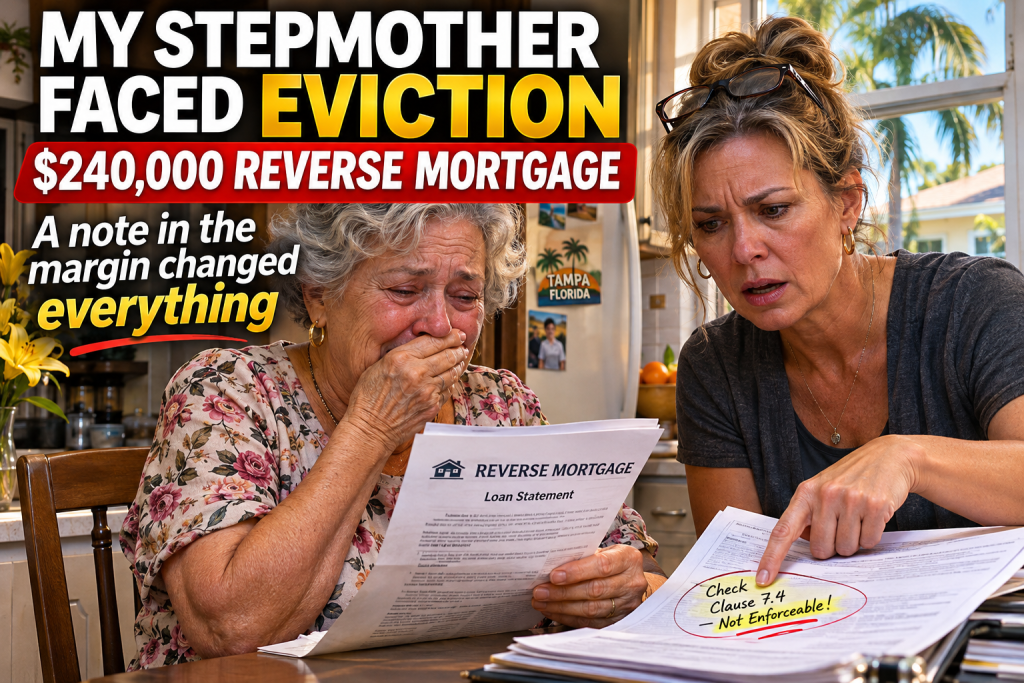
Some in our family always whispered that Gloria married Dad for his house. When he died, the reverse mortgage company told her to pay $240,000 in six months or get out, because her name was not on the loan. My brother said it wasn’t our problem. I drove to Tampa anyway, read every page at her kitchen table, and found a few words in pen in the margin that changed everything.
PART 1 — THE WOMAN DAD MARRIED
My mother died of breast cancer in 2008. My father, Frank Delgado, was sixty-nine. They had been married forty-one years, and for the first year after she died, I truly thought he might die too. He stopped eating. He stopped going to his Thursday night bowling league. He sat in his recliner in the dark.
Then, in 2009, he met Gloria at a grief support group at his church in Tampa.
She was a widow too, about eight years younger than Dad, a retired school cafeteria manager with a big laugh and a lot of opinions about baseball. Within six months, Dad was eating again. Within a year, he was bowling again. In 2010, when he was seventy, they got married in the church fellowship hall with a Cuban sandwich buffet and a three-piece band.
I’m Teresa. I’m fifty-seven, an accounts manager at a hospital in Atlanta. My brother, Mike, is sixty and lives in Charlotte. We were polite to Gloria from the start. We sent her birthday cards. We spent some Christmases in Tampa.
But we were never close. If I’m honest, I kept her at arm’s length.
Some people in our family thought she married Dad for his house. My aunt said it out loud at the wedding reception. Dad’s house was a three-bedroom ranch near Bayshore Boulevard that he and Mom had bought in 1974 for $38,000. By 2010, it was worth a great deal more.
“She’s sixty-two and broke,” my aunt whispered to me over the cake. “Your father’s lonely and has a paid-off house on the bay. You do the math.”
I didn’t argue. I didn’t agree, either. I just didn’t say anything. I’ve regretted that silence for a long time.
Gloria was always kind to me. I gave her politeness in return, which is not the same thing as kindness. I didn’t understand the difference until much later.
PART 2 — FIFTEEN YEARS
For fifteen years, Gloria took wonderful care of him.
She learned to make Mom’s black beans and rice because Dad missed them. She drove him to every doctor’s appointment. When he had his first heart attack in 2014, she slept in a chair beside his hospital bed for nine nights. When his eyesight started failing, she read him the sports page every morning.
When he was diagnosed with Parkinson’s disease in 2018, she became his full-time caregiver. She helped him dress. She helped him in the shower. She cut his food. She learned to manage eleven different medications.
Mike and I called every week. We visited twice a year. We sent flowers on Dad’s birthday. That was about all.
In 2017, Dad called me and told me he’d taken out a reverse mortgage on the house.
“It’s to help with Gloria’s medical bills,” he said. Gloria had had a knee replacement that year, and her insurance didn’t cover all of it. “The house is paid off. This way we can use some of what it’s worth while we’re still alive.”
I didn’t know much about reverse mortgages. I’d seen the TV commercials with the old actors. I asked him if he was sure.
“Teresa, I’m seventy-eight years old,” he said. “I’m sure.”
I let it go. I figured it was his house and his decision.
Mike was annoyed. “That’s our inheritance,” he said when I told him. “She’s spending our inheritance.”
“It’s Dad’s house, Mike.”
“For now,” he said.
I remember that conversation clearly. I remember thinking Mike was being petty. I also remember thinking, very quietly, that maybe our aunt had been right all along.
Dad lived nine more years after that. Gloria was beside him every single one of them.
PART 3 — THE LETTER
Dad died in January. He was eighty-six. He died at home, in the bed he’d shared with Gloria for fifteen years, with her holding his hand.
The funeral was at the same church where they met. Gloria sat in the front pew with Mike and me. She cried through the whole service. Mike sat stiffly, with his arms crossed.
Two months later, my phone rang on a Tuesday night. It was Gloria. She was sobbing so hard I couldn’t understand her at first.
“Teresa,” she finally said. “I got a letter. From the mortgage company. They say I have to leave the house.”
I asked her to read it to me.
The letter was from the company servicing the reverse mortgage. It said that because the borrower, Frank Delgado, had died, the loan was now due and payable. The balance was about $240,000. The estate or the heirs had six months to pay off the loan or sell the house. If not, the company would begin foreclosure.
And then the sentence that broke her heart. It said that Gloria was not a borrower on the loan and had no right to remain in the property.
Gloria was seventy-four. She lived on a small pension and Social Security. She had no other home. No children of her own. No savings to speak of, after years of caring for Dad.
“Where will I go, Teresa?” she said. “I lived in this house fifteen years. Your father died in this house.”
I didn’t know what to say. I told her I’d look into it.
After I hung up, I sat in my car in my driveway for a long time. I thought about all the years I’d been polite to her. I thought about the nine nights she slept in a hospital chair.
PART 4 — MY BROTHER
I called Mike the next morning.
“Gloria’s going to lose the house,” I said. “The reverse mortgage company says she has to leave.”
There was a pause.
“Well,” Mike said, “that’s not our problem.”
“Mike.”
“Teresa, think about it. If she leaves, and the house gets sold, whatever’s left after the loan comes to us. That’s what the will says. Dad left the house to us.”
That was true. Dad’s will, written before he married Gloria and never changed, left the house to Mike and me. He had left Gloria his life insurance and his car.
“She took care of him for fifteen years,” I said.
“And she got to live in a paid-off house on the bay for fifteen years,” Mike said. “Rent-free. That’s a pretty good deal.”
“Mike, she’s seventy-four. She has nowhere to go.”
“She can rent an apartment. Plenty of people do.” He sighed. “Look, I’m not trying to be cruel. But Aunt Lucy was right about her from the beginning, and you know it. Dad took out that reverse mortgage to pay her bills. Now she wants to keep living there on top of it? No.”
I hung up angry. Angry at Mike. Angry at myself, because a week earlier, I might have said the same thing.
That night, I booked a flight to Tampa.
I didn’t fully know why I was going. I think part of me wanted to prove Mike right, so I could stop feeling guilty. And part of me wanted to prove him wrong.
PART 5 — THE KITCHEN TABLE
Gloria met me at the airport. She looked smaller than I remembered. Older. She hugged me for a long time in the arrivals area.
At the house, everything was exactly as it had been when Dad was alive. His reading glasses on the side table. His bowling trophies on the shelf. Mom’s old wedding photo still on the hallway wall, right beside the photo of Dad and Gloria’s wedding. Gloria had never taken Mom’s picture down.
That surprised me. I don’t know why.
“Your father loved her very much,” Gloria said, when she saw me looking. “I never wanted to pretend she wasn’t here first.”
She made me café con leche and set a thick folder on the kitchen table. Her hands were shaking.
“This is everything,” she said. “All the papers from the reverse mortgage. Your father kept them in the desk. I don’t understand any of it.”
I’m an accounts manager. I read financial documents for a living. I sat down at that kitchen table and read the loan documents from beginning to end. Then I read them again.
The loan was a type called a Home Equity Conversion Mortgage, which is insured by the federal government. Dad had taken it out in 2017. Gloria was not listed as a borrower, which is why the servicer said she had no right to stay.
But on the application, under marital status, Dad had checked “married.” He had listed Gloria’s full name and her date of birth. She was sixty-six at the time.
And then, on the page where the loan officer had reviewed the household, someone had written something in the margin, in blue pen.
I read it once. Then I put my finger on it and read it again, slowly, word by word. Then I looked up at Gloria, who was watching me from across the table, terrified.
> “Gloria,” I said, “I think you’re going to be all right.”
PART 6 — THE NOTE IN THE MARGIN
The handwritten note in the margin said:
“Spouse G. Delgado, age 66, does not wish to be co-borrower. Eligible Non-Borrowing Spouse. Certification signed and attached. Deferral explained to both.”
Below it was the loan officer’s initials and a date.
I flipped through the folder. And there it was, two pages later. A separate form, signed by both Dad and Gloria, called a non-borrowing spouse certification.
I had heard of this. Years ago, some surviving spouses who were not on reverse mortgages lost their homes when the borrower died, just like Gloria was about to. It became a national scandal. Federal rules changed in 2014. Under the newer rules, for these government-insured reverse mortgages, a spouse who was married to the borrower when the loan was made, and was properly identified at closing, can be what’s called an eligible non-borrowing spouse.
That means, if certain conditions are met, the spouse can keep living in the home after the borrower dies, as long as it remains their principal residence and they keep paying property taxes and insurance and maintaining the house. The loan’s repayment is deferred. They don’t have to leave.
Dad had done it. He’d made sure Gloria was protected. And the loan officer had written it right there in the margin so nobody could miss it.
Except somebody had missed it. The servicer’s letter treated Gloria as if she had no rights at all.
Gloria didn’t understand at first. I explained it three times, slowly.
When she finally understood, she put both hands over her mouth.
“Frank did that?” she whispered. “For me?”
“He did,” I said. “He made sure you’d never have to leave.”
She started to cry. Not the frightened crying from the phone call. A different kind. She cried the way you cry when somebody you’ve lost reaches back and holds your hand one more time.
PART 7 — FIGHTING THE SERVICER
The next morning, I called the reverse mortgage servicer. I explained the situation, read them the margin note, and told them we had a signed non-borrowing spouse certification.
The representative said she would “make a note” and someone would call us back.
Nobody called back.
I flew home to Atlanta, but I didn’t let it go. I found a nonprofit legal aid office in Tampa that helps seniors with housing problems. A young attorney there named Jasmine Rivera took Gloria’s case for free.
Jasmine was sharp and angry in the best way. “This happens more than you’d think,” she said. “Servicers send out the standard due-and-payable letter and don’t check whether there’s an eligible non-borrowing spouse in the file. Sometimes it gets fixed. Sometimes widows get scared and just leave. Your stepmother almost did.”
She sent the servicer a formal written notice with copies of the certification, the loan application, Dad’s death certificate, and proof that Gloria still lived in the house as her primary residence. She also contacted the federal housing agency that insures these loans.
Meanwhile, Gloria had to do her part. As an eligible non-borrowing spouse, she needed to keep paying the property taxes and homeowner’s insurance, and keep the house in good repair. Those had always been paid from Dad’s accounts.
“I don’t know if I can afford the taxes on my own,” Gloria told me on the phone. “They’re almost four thousand dollars a year.”
I was quiet for a moment. Then I said something I never expected to say. “Don’t worry about the taxes, Gloria. I’ll take care of them.”
PART 8 — TELLING MIKE
I had to tell Mike. I called him on a Sunday.
“Gloria’s staying in the house,” I said. “Dad set it up when he took out the reverse mortgage. She’s an eligible non-borrowing spouse. She can live there for the rest of her life, as long as she pays the taxes and insurance.”
There was a long silence.
“So we don’t get the house,” Mike said.
“Not until Gloria’s gone. Then it’ll be handled like any reverse mortgage. Whatever equity’s left goes to the estate. To us.”
“There won’t be any equity left by then,” he said. “The loan just keeps growing.”
“Maybe not,” I said. “Mike, Dad wanted her protected. He signed a form that says so. He made sure of it. That was his choice.”
Mike didn’t say anything for a long time.
“Did you know Dad called me in 2017?” he finally said. “Right after he took out the loan. He told me he’d made sure Gloria could stay in the house if anything happened to him. He told me to look out for her.”
I was stunned. “You knew?”
“I didn’t understand it,” Mike said. “I figured he meant we should let her stay a few months. I didn’t know it was a legal thing.” He paused. “I was so sure Aunt Lucy was right about her. I never gave her a chance.”
“Neither did I,” I said.
Then my brother, who is sixty years old and has never once in his life apologized first, said quietly, “I owe her an apology, don’t I?”
> “We both do,” I said.
PART 9 — THE NEW LETTER
Two months later, Gloria called me. She was laughing and crying at the same time.
“Teresa, I got another letter from the mortgage company,” she said. “They say they made an error. They say I’m an eligible non-borrowing spouse and the deferral period applies. They say I can stay.”
Jasmine had done it. The servicer had reviewed the file, found the certification, and corrected its records. The foreclosure threat was withdrawn. As long as Gloria lived there as her home and kept up the taxes, insurance, and maintenance, the loan would not be due during her lifetime.
Mike and I split the property taxes and insurance now. It comes to about three hundred and fifty dollars a month between us. It’s the best money I’ve ever spent.
Mike flew to Tampa in June. He’d never been there without me. He took Gloria to the Rays game and bought her a hot dog and apologized in the eighth inning, right after a home run, when everybody was standing and cheering and nobody could see him tear up except her.
She told me about it later. “Your brother is a sweet man,” she said. “He just hides it under all that grumbling. Like your father.”
I laughed. “That’s exactly right.”
I asked Gloria once whether she was angry at us. For all the years of keeping her at arm’s length. For Mike saying it wasn’t our problem.
> She thought about it. “No,” she said. “Your father always told me you’d come around. He said the Delgados are slow but they get there.”
That same summer, Gloria asked if I would help her go through Dad’s desk. In the bottom drawer, under his old bowling scorecards, we found a copy of the non-borrowing spouse certification with a yellow sticky note on it in Dad’s shaky handwriting. It said: “Glo, if they ever try to make you leave, show them this. You stay. That’s an order. Love, Frank.”
Gloria laughed so hard she had to sit down on the floor. “He never gave me an order in fifteen years,” she said, wiping her eyes. “Not one. He saved it for the end.”
She keeps that sticky note on her refrigerator now, right next to the calendar.
PART 10 — WHAT DAD KNEW
It’s been a year since the second letter.
Gloria still lives in the house on Bayshore. She plays bingo at church on Tuesdays and still reads the sports page out loud every morning, even though there’s nobody to read it to. She says it keeps Dad company.
I visit every few months now. Not twice a year. Every few months. Gloria taught me how to make Mom’s black beans and rice the way Dad liked them, which is funny, because Mom never taught me. Gloria learned it from a recipe card Dad dug out of a drawer in 2010.
I’m sharing this story because I know there are many widows and widowers living in homes with reverse mortgages, and some of them may receive the same frightening letter Gloria did.
If you are married and taking out a reverse mortgage, make sure your spouse is either a co-borrower or properly listed and certified as an eligible non-borrowing spouse. Read every page. Keep copies of everything.
If you receive a due-and-payable letter after a spouse dies, don’t panic and don’t move out. Find the loan file and talk to a housing counselor or legal aid attorney. You may have more rights than the letter says.
Keep paying property taxes and insurance. Those are conditions for staying.
And give the people your parents love a fair chance. I spent fifteen years being polite to a woman who loved my father with everything she had. I almost let her lose her home because of a rumor at a wedding.
My father couldn’t take Gloria with him. So he did the next best thing. He made sure she could stay right where he left her.
Last month, Gloria sent me a photo. Her and Mike, at a Rays game, wearing matching caps, both of them grinning.
On the back, she’d written: “Your father would be laughing at us right now.”