Kyle wanted a thirty-eight-thousand-dollar pickup, and his mother wanted him to save for it first. He stopped speaking to her over that one word, no. Then his wife called sobbing in the middle of the night, and Brenda found her son on the curb while an officer held loan papers bearing her name, her Social Security number and a signature written in a hand she knew from twenty Christmas cards.
PART 1 — TOO OLD-FASHIONED
My son asked me to co-sign a thirty-eight-thousand-dollar truck loan two weeks after telling me I was “too old-fashioned” to give him financial advice.
I want to start there, because it matters.
My name is Brenda Harper. I am sixty-three years old. I worked as a bookkeeper for a plumbing supply company in Springfield, Missouri, for thirty-one years. I raised my son, Kyle, by myself after his father left when Kyle was four. I balanced my checkbook every Sunday night with a pencil and a calculator. I paid off my house in 2019. I have never carried a credit card balance in my life.
Kyle is thirty-two. He is a good boy, mostly. A hard worker. He drives a delivery route for a beverage company. He married a sweet girl named Kayla six years ago, and they have two little ones, Mason and Lily.
But Kyle has never been good with money. I tried to teach him. He never wanted to learn.
At Easter dinner, I mentioned that he might want to start a savings account for the kids. He laughed and said, “Mom, nobody does it your way anymore. You’re too old-fashioned.”
Two weeks later, he came to my house with a folder.
He had found a truck. A black pickup, three years old, with leather seats and a towing package. Thirty-eight thousand dollars. His credit was not good enough to get the loan on his own. The dealership said he needed a co-signer.
“Mom, please,” he said. “It’s a great deal. Kayla’s dad found it for me. He knows the finance manager.”
Kayla’s father, Ron Pruitt, sold used cars for twenty years before opening his own small lot outside Nixa. He is a big, friendly man who sends Christmas cards every year with handwritten notes.
I looked at the numbers. Then I looked at my son. “No, Kyle,” I said gently. “I’m sorry. I can’t do that.”
PART 2 — THE SILENCE
I explained why. I always do.
His payment would be almost nine hundred dollars a month. He already had a car payment on Kayla’s minivan, credit card debt and a mortgage. I had seen the numbers. He could not afford it. And if he could not pay, the bank would come after me. I was retired. I had my house and my savings and that was all.
“Save for a year,” I said. “Pay down the credit cards. Buy something cheaper. I’ll help you look.”
Kyle’s face turned red.
“This is exactly what I meant,” he said. “You always think I’m going to fail.”
“I don’t think that, honey.”
“Yes, you do.” He grabbed the folder off my kitchen table. “Forget it. I’ll figure it out myself.”
He did not speak to me for a month.
He did not answer my calls. He did not come for Sunday dinner. When I drove over with a birthday present for Mason, Kayla met me at the door, looking embarrassed, and said Kyle was at work.
I told myself he would get over it. Boys do. He had stopped speaking to me before, when he was nineteen and wanted to drop out of community college. That lasted three weeks.
I spent those weeks cleaning closets that did not need cleaning and baking cookies nobody was there to eat. My friend Doris from church told me to give him time. I gave him time. Every day felt longer than the last.
But this time felt different. This time, I worried.
The only thing I did, during that month, was something I had read about in the newspaper. I placed a freeze on my credit at all three bureaus. A friend from church had her identity stolen the year before, and it took her two years to fix it. I figured it could not hurt.
I had no idea that one small, old-fashioned precaution would turn out to be the most important thing I ever did.
PART 3 — 1:12 A.M.
At 1:12 in the morning on a Tuesday in June, my phone rang.
It was Kayla. She was crying so hard I could barely understand her.
“Brenda, please come,” she sobbed. “Please come get the kids. The police are here. They’re talking to Kyle. Please.”
I did not ask questions. I put on my robe, stuck my feet in my slippers and grabbed my car keys.
I do not remember locking my front door. I do not remember the first ten miles.
I drove forty minutes through the dark, with my heart pounding, to Kyle and Kayla’s little house in Ozark.
When I turned onto their street, I saw the lights first. Red and blue, flashing against the houses. Two police cars parked at angles in front of their driveway.
And there, in the driveway, sat a shiny black pickup truck. Three years old. With a towing package.
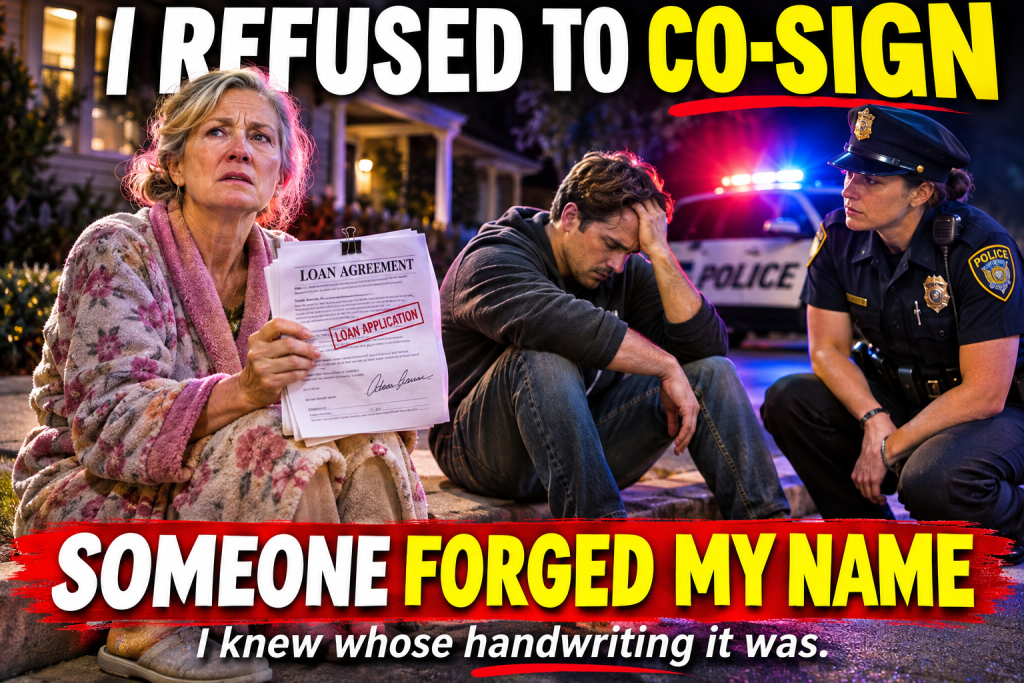
My son was sitting on the curb in his work uniform, his elbows on his knees, furious. An officer stood beside him holding a folder of papers.
Kyle saw my car and stood up.
“Mom!” he yelled across the yard. “Tell them I didn’t do this! Tell them!”
I got out of the car in my robe and slippers. A young female officer came over to meet me.
“Ma’am, are you Brenda Harper?”
“Yes.”
“I’m Officer Delgado. I’m sorry to call you out this late. We need to ask you a few questions about this vehicle.”
She held up the folder.
“Did you co-sign a loan for this truck, Mrs. Harper?” she asked. I stared at the truck in my son’s driveway. “No,” I said. “I did not.”
PART 4 — THE SIGNATURE PAGE
Officer Delgado opened the folder and showed me the loan paperwork under the light of her flashlight.
There was the truck. Thirty-eight thousand dollars. Seventy-two months.
There was Kyle’s name as the borrower.
And there was my name as the co-signer. My full name. My address. My date of birth. And my Social Security number.
Then she turned to the signature page.
My name was signed at the bottom. In blue ink. Brenda L. Harper. It looked a little like my signature. But it was not mine.
“Mrs. Harper,” Officer Delgado said, “the lender’s fraud department flagged this loan three days ago. When they tried to finalize it, your credit report came back frozen. You had a fraud alert on file. The lender contacted us. We were trying to reach the borrower, and tonight a patrol officer recognized the vehicle on the highway and followed it home.”
My credit freeze. My old-fashioned, worried little credit freeze.
“I didn’t do this!” Kyle shouted from the curb. “I swear, Mom. I didn’t sign your name. I would never do that.”
I looked at my son. He was crying now. Angry, frightened tears.
“Then who did?” I asked him quietly.
“I don’t know! Ron handled the paperwork. He said you changed your mind. He said you called him and agreed to co-sign as long as I didn’t tell you I knew. He said you were too proud to admit it.”
I looked down at the signature page again. At the loops on the B and the H. At the slant of the letters.
I had seen that handwriting before. Every Christmas for six years. On a card with a picture of a Labrador wearing a Santa hat.
PART 5 — RON
“Kyle,” I said slowly. “Where is Ron right now?”
Kyle stared at me. “What? Why?”
“Because that’s his handwriting,” I said.
Officer Delgado looked up sharply.
Kayla, standing on the front porch holding her sleeping daughter, made a small sound.
“Mom, that’s crazy,” Kyle said. “Ron’s family.”
“Ron’s been signing Christmas cards to me for six years,” I said. “He makes his B exactly like that. With the little curl at the top. He signs his name Ron Pruitt in blue ink with the same slant. I’d know it anywhere.”
Kayla came down the porch steps, carrying Lily, her face white.
“Dad called me last month,” she whispered. “He asked for Brenda’s birthday. He said he wanted to send her a card. And her address. I didn’t think anything of it.”
“And her Social Security number?” Officer Delgado asked gently.
Kayla shook her head. Then she stopped.
“Kyle had it,” she said slowly. “From when Brenda helped us with the mortgage application. It was in a folder in our desk. Dad was here last month. He used the desk to fill out some forms for the truck.”
Kyle sat down hard on the curb again. He looked like he had been punched.
“He told me you agreed,” he said. “He said you’d come around but didn’t want to admit it. He said to just sign my part and he’d handle yours.”
Officer Delgado closed the folder.
“Mrs. Harper,” she said, “would you be willing to come to the station tomorrow and give a statement?”
I looked at my son on the curb, and my daughter-in-law holding my granddaughter, and the shiny black truck in the driveway. “Yes,” I said. “I will.”
PART 6 — WHY RON DID IT
I gave my statement at the police station the next morning, still shaky from no sleep. Officer Delgado brought me a cup of coffee and let me take my time. I brought one of Ron’s Christmas cards from my drawer at home. She compared it to the loan papers and nodded slowly.
It took two weeks for the whole story to come out.
Ron Pruitt was in trouble. His used car lot outside Nixa had been losing money for two years. He owed back taxes. He had borrowed against his house. He was desperate.
The finance manager at the dealership where Kyle bought the truck was an old friend. For every loan Ron brought in, the dealership paid him a referral fee. Fifteen hundred dollars for a deal like Kyle’s.
But Kyle could not get approved without a co-signer. I said no. So Ron decided to sign for me.
He assumed I would never find out. He assumed Kyle would make the payments, and nobody would ever look at the signature page again.
What he did not know was that I had frozen my credit. When the lender ran my report to finalize the loan, it came back locked, with a fraud alert attached. The lender called my phone number on file. Not Kyle’s. Not Ron’s. Mine.
I had missed the call. It went to voicemail while I was at church. I did not recognize the number and never listened to it.
So the lender’s fraud department called the police.
Ron was arrested the following week. He was charged with forgery and identity theft. The finance manager at the dealership was fired after an internal investigation found he had helped Ron with the paperwork on at least four other loans.
The truck was returned to the dealership. The loan was cancelled. Kyle owed nothing, because the loan was fraudulent from the start. But he lost his down payment of two thousand dollars.
It was the most expensive lesson my son ever learned. But I think he would tell you it was worth it.
PART 7 — MY SON
Kyle came to my house the Sunday after Ron was arrested. Alone. For the first time in six weeks.
He sat at my kitchen table, the same table where he had grabbed his folder and stormed out. I made coffee. I set out a plate of the lemon cookies he loved as a little boy.
He did not touch them. He just turned his coffee cup around and around on the table, the way his father used to.
“I’m sorry, Mom,” he said. “For everything. For not talking to you. For calling you old-fashioned. For believing Ron when he said you’d changed your mind.”
“You wanted to believe him,” I said gently. “You wanted the truck.”
He nodded.
“If you hadn’t frozen your credit,” he said, “the loan would have gone through. Your name would be on it. If I’d missed payments, they would have come after you. Your house. Your savings. Everything you worked for.”
“I know.”
“And I’d never have known it wasn’t you who signed.”
He put his face in his hands.
“I kept thinking about it in the police car,” he said. “You came out at one in the morning in your bathrobe. You didn’t even ask what happened. You just came.”
“You’re my son,” I said. “Where else would I be?”
He started to cry. My grown son, thirty-two years old, with two children of his own, crying at my kitchen table like he did when he was six and fell off his bicycle.
I came around the table and put my arms around him.
“Mom,” he said into my shoulder, “will you teach me? The checkbook thing. The budget. All the old-fashioned stuff. I want to learn. For Mason and Lily.”
PART 8 — KAYLA
Kayla had the hardest time of all.
Her father was in jail. Her mother was furious and embarrassed. Her family was split down the middle. Some of them blamed me for going to the police.
She came to see me a month after the arrest. She brought the kids. We sat on my back porch while Mason and Lily played in the sprinkler.
“I’m so sorry, Brenda,” she said. “I gave him your birthday. I left the folder in the desk. I should have known.”
“Honey,” I said, “your father lied to you too. You trusted him. That’s not something to be sorry for.”
She cried quietly for a long time.
“I keep thinking,” she said, “what if it had worked? What if your credit hadn’t been frozen? You’d have lost everything because of my family.”
“But it didn’t work,” I said. “And now we know.”
She told me her father had written her a letter from jail. He said he was sorry. He said he never meant to hurt anyone. He said he had been sure Kyle would make the payments and nobody would ever know.
“He said you were the most careful person he’d ever met,” Kayla said. “He said he should have known better than to forge the signature of a woman who balances her checkbook with a pencil.”
Despite everything, I laughed.
Ron pleaded guilty that winter. He received probation, community service and an order to repay the dealership and the lender. He lost his car lot.
Kayla visits him once a month. She says he is a different man now. Quieter. She is working on forgiving him. I told her that is her choice to make, in her own time.
PART 9 — SUNDAY NIGHTS
Kyle and I started meeting every Sunday night.
He comes over after the kids are in bed. Kayla comes too, sometimes. We sit at my kitchen table with a pencil, a calculator and a spiral notebook, and we go through their bills.
The first few weeks were hard. They had more debt than I realized. Credit cards. A personal loan. Late fees on almost everything.
But we made a plan. Kyle took on extra routes on Saturdays. Kayla started selling handmade baby blankets online. They cancelled three streaming services and a gym membership neither of them used. They paid off the smallest debt first, then the next one, then the next.
Every time they paid something off, Kyle drew a big red line through it in the notebook and wrote the date. By Christmas, there were six red lines.
He froze his own credit, and Kayla’s. He set up a savings account for each of the kids, with twenty-five dollars going in automatically every payday.
“Twenty-five dollars,” he said, a little embarrassed. “It’s not much.”
“It’s a beginning,” I said. “That’s how everything starts.”
Kayla’s blanket business grew faster than any of us expected. By spring she had orders from three states. She opened a separate account for it and showed me the ledger proudly every Sunday.
Last month, he bought a truck.
A used one. Eight years old, silver, with a hundred and ten thousand miles and a dent in the tailgate. He paid six thousand dollars for it in cash. Money he had saved over a year.
He drove it to my house to show me. He was grinning like a little boy on Christmas morning.
“No co-signer,” he said. “No loan. No forged signatures. Just old-fashioned cash.” I laughed so hard I had to sit down on the porch step.
PART 10 — WHAT I KNOW NOW
My son told me I was too old-fashioned to give advice.
He was right, in a way. I am old-fashioned. I balance my checkbook with a pencil. I read every line of every statement. I froze my credit because a friend from church told me to, even though I did not fully understand how it worked.
That old-fashioned habit saved my house. It saved my savings. And it saved my son from a debt that would have followed him for six years.
People ask me if I was angry at Kyle. Honestly, for a while, I was. Not because he wanted the truck. Because he believed someone else instead of me.
But I understand now. When you are young, you think the people who say yes to you are the ones who love you most. It takes a long time to learn that sometimes the people who love you most are the ones who say no.
If you are a parent, and your grown child asks you to co-sign something you do not believe they can afford, it is all right to say no. Say it gently. Explain why. And then protect yourself. Freeze your credit. It costs nothing and takes ten minutes.
And if you are the grown child, please listen to your mother. Even when she is old-fashioned. Especially then.
Kyle and Kayla now come to Sunday dinner every week. After dinner, we sit at the kitchen table with the spiral notebook. Mason, who is eight now, has started joining us. He has his own little notebook, for his allowance.
Last Sunday, he drew a red line through his first goal. A ten-dollar toy truck, paid for in cash. He looked up at me and grinned. “Grandma,” he said, “is this how you do it?” Yes, sweetheart. This is exactly how you do it.