Claire Bennett now spends her days teaching computers to recognize financial fraud before it reaches ordinary families. Her father never asked what she did after he showed her the door. So when he raised a glass over a deal that seemed too generous to question, nobody at the table noticed the small detail that made Claire put down her fork. Nobody except the daughter he had cut off.
PART 1 — THE PEAR
My family thought they had just made forty-eight million dollars. They were celebrating money they did not actually own.
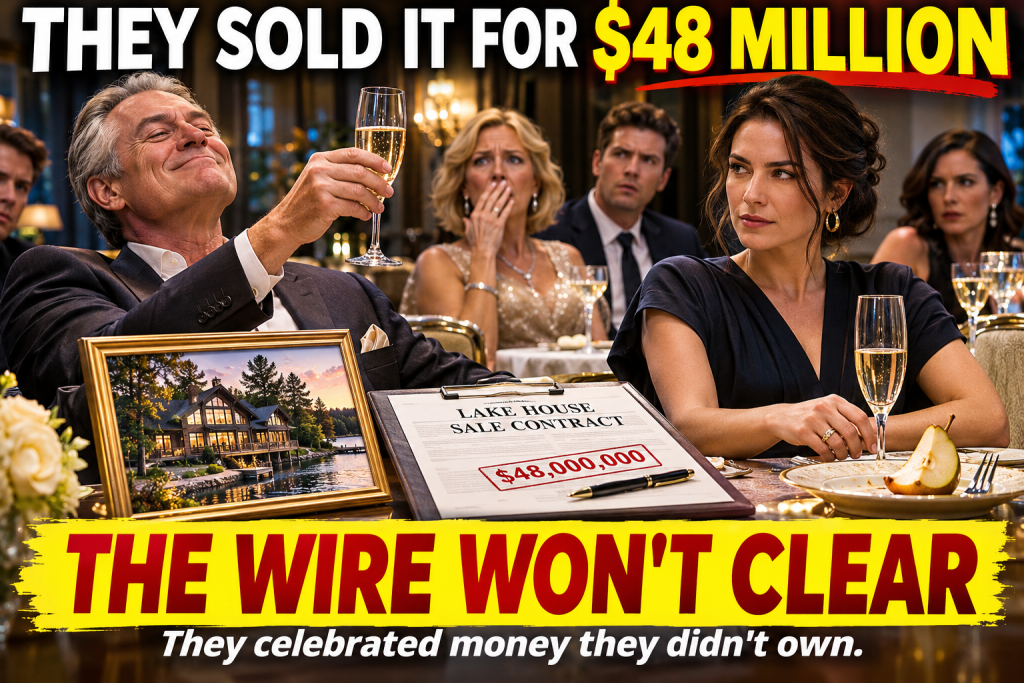
We were at my father’s house in Lake Forest, Illinois, for the first family dinner I had been invited to in six years. Long mahogany table. Crystal glasses. A catered dinner of roast lamb and asparagus. My father at the head of the table. My younger brother, Caleb, at his right hand, where I used to sit.
Dessert was a bowl of fruit and a cheese plate. I had taken a pear.
My father stood and tapped his glass.
“I have wonderful news,” he announced. “The lake house in Wisconsin has sold. Forty-eight million dollars. Cash. The deal closes on February third.”
Caleb laughed and clapped. “Dad, you pulled off a miracle!” he said.
My stepmother, Diane, gasped and put her hand over her heart. My aunt and uncle raised their glasses. Caleb’s wife, Tiffany, squealed and hugged him.
I had almost not come. Diane, my stepmother, had called a week earlier and said my father wanted the whole family together for “a special announcement.” She said he had asked for me specifically. I wondered whether he wanted me there to make peace, or to watch.
I quietly ate my pear and listened to them celebrate.
The lake house is a lovely old stone place on Geneva Lake that my great-grandfather built in 1931. Eleven bedrooms. A boathouse. Two acres of lawn running down to the water. It is a beautiful property. I spent every summer of my childhood there.
It is worth, at the very most, nine million dollars. I know, because I looked at every comparable sale on that lake the week my father listed it.
They had no idea why I was so calm.
When the toasting finally died down, I set down my fork and looked directly at my father.
“The forty-eight million dollar wire won’t clear on February third,” I said.
PART 2 — SIX YEARS EARLIER
Everyone froze. My father stared at me.
To understand that moment, you need to understand what happened six years earlier.
My father, Robert Bennett, runs Bennett Capital, a wealth management firm in Chicago that his grandfather founded. I worked there for nine years after college. I was the only person in the family who could code.
In my spare time, on nights and weekends, I built a piece of software. It analyzed financial transactions and flagged patterns that suggested fraud. Fake invoices. Impersonation scams. Suspicious wire transfers. I built it on my own laptop, on my own time, using what I had learned at night school in machine learning.
When I showed it to my father, he was impressed. Then he asked me to sign it over to Bennett Capital.
“It’s family property,” he said. “You built it while you worked here.”
“I built it on my own time,” I said. “On my own computer. I’d be happy to license it to the firm. But I want to own it.”
He gave me one week to change my mind. When I did not, he called me into his office and fired me. Then he called the family trust’s attorney and had me removed as a beneficiary.
“You’ve chosen your path,” he said. “Don’t expect the family to follow you down it.”
Caleb took my office the following Monday. Caleb, who had never written a line of code in his life.
I remember driving home that night with a cardboard box on the passenger seat and my laptop on my knees at every red light, as if someone might take that from me too.
I left. I founded my own company, Clearline Analytics, in a rented room above a coffee shop in Evanston. I licensed my software to banks and title companies. It grew. Today, Clearline’s fraud detection systems review wire transfers for more than three hundred banks and escrow companies across the country.
My father never once asked what I did after I left. And so he had no idea that I spend every working day looking at deals exactly like his.
PART 3 — WHY NOT
“What are you talking about?” my father finally said.
“Who is the buyer, Dad?”
He frowned. “A company called Ridgeway Lakeshore Holdings. Very serious people. Overseas investors. They want the property for a private retreat.”
“Did you meet them?”
“Their agent. Over video. A very professional man. They sent proof of funds. A letter from a bank in Zurich.”
“Did they ask for an inspection?”
He hesitated. “No. They said they’d seen enough photos. They’re paying cash. They don’t need an inspection.”
“Did they ask you to pay anything up front?”
Caleb jumped in, irritated. “Claire, come on. Why are you trying to ruin this?”
I kept my eyes on my father.
“Did they ask you to pay anything up front, Dad?”
He was quiet for a long moment.
“There’s an international transfer fee,” he said finally. “And an escrow insurance premium. Because the funds are coming from overseas. It’s standard. One point two million. Their agent explained everything.”
“Have you sent it?”
“It goes out tomorrow morning,” Caleb said. “Before closing. To their escrow agent in Toronto. Dad already signed the wire authorization.”
Diane’s smile had faded. My aunt set her glass down.
My uncle cleared his throat and said nothing. Tiffany reached for Caleb’s arm.
I folded my napkin and placed it beside my plate.
“Dad,” I said, “please don’t send that money.”
“Why not?” my father demanded. I smiled, not unkindly, and said, “Because the buyer doesn’t exist.”
PART 4 — THE PATTERN
There was a long silence around that table.
“That’s ridiculous,” Caleb said.
“Is it?” I said. “A nine-million-dollar house selling for forty-eight million. Cash. No inspection. Overseas buyer you’ve never met in person. Proof of funds from a foreign bank. And an upfront fee, to be wired to a third party in another country, before the closing.”
I looked around the table.
“That is not a lucky deal. That is a textbook advance-fee scam. My company sees a version of it every single week.”
“You don’t know that,” my father said. But his voice had changed.
“I know Ridgeway Lakeshore Holdings was registered in Delaware forty-one days ago,” I said. “I looked it up on my phone during the toast. I know the agent’s email domain was created six weeks ago. And I’d bet my company that the Zurich bank letter is a forgery.”
“How could you possibly…”
“Because I built the software that catches these, Dad,” I said quietly. “The software you fired me for.”
My father sat down slowly.
Caleb was staring at me. Tiffany had stopped smiling. Diane had both hands flat on the tablecloth.
“Their agent is going to send you a final closing date,” I said. “Maybe February third. Then something will go wrong. The overseas funds will be delayed. They’ll need another fee to release them. Then another. They’ll keep asking until you stop paying. And on February third, no forty-eight million dollars will ever arrive. Because it never existed.”
“The only real money in this deal,” I said, “is the one point two million dollars you’re about to send them.”
PART 5 — THE CALL
My father did not believe me at first. Or he did not want to.
He went to his study and called the agent. Caleb went with him. I could hear raised voices through the door. Diane sat across from me, pale and silent, twisting her napkin.
After twenty minutes, my father came back to the dining room. He looked ten years older.
“He says the buyer is very upset that we’re questioning their integrity,” my father said. “He says if we don’t send the fee by ten o’clock tomorrow, they’ll walk away and buy another property.”
“Of course he does,” I said gently. “That’s the pressure. They always set a deadline.”
“Claire,” my father said, and it was the first time in six years I had heard him say my name without anger, “what do I do?”
I took out my phone.
“First, you call your bank tonight and cancel that wire authorization,” I said. “Then you call the FBI’s internet crime unit and file a report. I’ll help you. And then you call your real estate attorney and have him send a letter to the title company terminating the contract for failure to provide verified funds.”
“And if you’re wrong?”
“If I’m wrong,” I said, “and Ridgeway Lakeshore Holdings is real, they will send forty-eight million dollars to a licensed U.S. escrow company like any legitimate buyer. And you’ll have lost nothing. But if I’m right, you’ll have saved one point two million dollars.”
Outside, snow had begun to fall on the lawn. Somewhere in the house, a clock chimed ten. Nobody had touched dessert since my father stood up for his toast.
He looked at Caleb. Caleb looked at the floor.
My father picked up his phone and called his bank’s fraud line. I sat beside him while he did it.
PART 6 — WHAT WE FOUND
My father’s bank cancelled the wire that night. The next morning, he filed a report with federal investigators. I sat with him in his study and helped him fill it out.
Then, with his permission, I ran every document the buyer had sent through Clearline’s verification tools.
The Zurich bank letter was a forgery. The bank existed, but the letterhead was copied from an old public filing, the account number did not exist and the signature belonged to an executive who had retired four years earlier.
The agent’s video calls had been made through an internet service registered in Eastern Europe. The escrow company in Toronto did not appear in any Canadian registry. Ridgeway Lakeshore Holdings had no officers, no address and no history.
And the email chain showed something even worse. Three weeks earlier, the agent had asked my father for a scan of his passport and driver’s license, “for international compliance.” My father had sent them.
“Dad,” I said, “you need to freeze your credit. Today. All three bureaus. And change every password you have.”
He did. I helped him.
It took us most of the morning. My father sat beside me at his own desk, watching me work, asking questions. Real questions. How did I know the letterhead was copied? What made an email domain suspicious? How many people fall for this? I answered every one.
Later that week, an investigator called to tell my father that the same group had tried the same scheme on at least eleven other luxury property owners around the country. Two of them had already sent the upfront fees. One had lost almost two million dollars.
The investigator also mentioned, almost casually, that the scheme had been first flagged by an automated fraud detection system used by a regional title company in Florida.
“Do you know which system?” my father asked.
“Clearline Analytics,” the investigator said. “Out of Evanston. Their software caught it.”
PART 7 — MY FATHER
My father did not say anything after he hung up. He just sat in his leather chair, in the study where he fired me six years earlier, and stared at the window.
“Your software,” he said finally.
“Yes.”
“The one I fired you for.”
“Yes, Dad.”
He was quiet for a very long time.
“I was wrong,” he said. “I told myself you were being selfish. I told myself you owed it to the family. The truth is, I was angry that you built something I didn’t understand. Something that wasn’t mine.”
“I didn’t do it to hurt you,” I said. “I did it because I wanted to protect people. People like you.”
“I know that now.”
He looked at me with wet eyes.
“I cut you out of the trust,” he said. “I gave your office to your brother. I didn’t call you for six years. And the first time you come back to this house, you stop me from losing more than a million dollars.”
“You would have lost more than that,” I said gently. “With your passport and license, they could have opened accounts in your name. Borrowed against your other properties. It could have been much worse.”
He put his face in his hands.
My father, who had never apologized for anything in my entire life, said, “I’m sorry, Claire. For all of it.”
I did not answer right away. Six years of silence do not disappear in one sentence. But I could see he meant it.
I put my hand on his shoulder. It was the first time I had touched my father in six years. He reached up and held my hand there, hard.
PART 8 — CALEB
Caleb came to see me two weeks later at my office in Evanston. He had never been there. He stood in the lobby looking at the wall of screens where my analysts monitor flagged transactions around the country.
“So this is what you do,” he said.
“This is what I do.”
He sat down in my office. He did not look like the smug younger brother who took my desk six years ago. He looked tired.
“Dad’s thinking about retiring,” he said. “He’s shaken. He keeps saying he almost lost everything because he was too proud to listen to you.”
“He’s not wrong.”
“I’m the one who pushed the deal,” Caleb said quietly. “The agent contacted me first, on a networking site. I brought it to Dad. I thought if I closed a forty-eight-million-dollar sale, he’d finally see me as more than the son who got your job.”
I had not known that.
“I’m sorry, Claire,” he said. “For all of it. For taking your office. For laughing when he cut you out. I didn’t know how to compete with you, so I just stood next to Dad and agreed with him.”
I looked at my little brother for a long moment. He was thirty-four years old, and for the first time I could remember, he was being honest with me.
“You don’t have to compete with me, Caleb,” I said. “You never did.”
He looked at the screens through my glass office wall, at the young analysts in hoodies and headphones, at the coffee cups and whiteboards covered in diagrams.
He laughed, a little shakily. “That’s easy for the genius to say.”
“I’m not a genius,” I said. “I just pay attention. You can learn that.”
Then I offered him something I never expected to offer. A three-month position at Clearline, learning how fraud actually works.
PART 9 — THE LAKE HOUSE
My father did not sell the lake house.
After everything that happened, he decided he did not want to. He told the family at Easter that he had spent so long thinking about what the house was worth that he had forgotten what it meant.
Instead, he did something none of us expected.
He called the family trust’s attorney, the same man who had removed me six years earlier, and had me restored as a beneficiary. Then he asked me to become a co-trustee, alongside him and Caleb.
“Somebody in this family needs to read the fine print,” he said. “I’d like it to be you.”
He also offered to license Clearline’s software for Bennett Capital. Properly. At full price. I gave him the standard rate, no discount. He said that was exactly as it should be.
When the papers were signed, he took me to lunch at the steakhouse where he used to take clients. He ordered for both of us, out of habit, then caught himself and apologized and let me order my own. It was a small thing. It meant more than he knew.
Caleb finished his three months at Clearline. He was not a natural with data. But he was very good with people, and he discovered he liked explaining scams to older clients so they could protect themselves. He now runs a free fraud education program at Bennett Capital for retirees. He says it’s the first job he has ever been proud of.
That summer, the whole family went to the lake house for the Fourth of July. The first time in six years I had been there.
I sat on the old stone porch at sunset with my father, watching the boats on the water.
“Forty-eight million dollars,” he said, shaking his head. “I really believed it.”
“Everybody wants to believe a deal like that, Dad,” I said. “That’s why it works.”
PART 10 — WHAT I KNOW NOW
My father is retired now. He spends most of the summer at the lake house, fishing off the old dock with his grandchildren. He calls me every Sunday. He asks about my work, really asks, and listens to the answers.
Last Christmas, he gave a short toast at dinner. The same mahogany table. The same crystal glasses.
“To Claire,” he said. “Who taught me that the most valuable thing in this family was never a house. It was a daughter who was willing to tell me the truth when I didn’t want to hear it.”
Everyone raised their glasses. Caleb winked at me.
I took a pear from the fruit bowl, the way I had that night, and ate it slowly while everyone laughed and talked around me. My father noticed and smiled.
At Clearline, we tell the story to every new employee. Not with names. Just the pattern. A buyer nobody has met. A price too good to be true. A deadline. An upfront fee. The pressure to act before you think.
And we tell them that the most important tool in fraud prevention is not software. It is a person calm enough to ask one more question.
If anyone ever offers you far more than something is worth, especially if they want you to send money first, slow down. Ask who they are. Ask where the money comes from. Ask someone you trust to look at it with fresh eyes.
And if someone you pushed away tries to warn you, swallow your pride and listen. The person you cut out of your life may be the very one who knows exactly how to keep you safe.