Laura Brennan is a retired paralegal who reconciles her bank statements every Sunday with a pencil and a cup of tea. So a small city charge that should not exist was not something she could ignore. One phone call became a camera photograph, then a car title, then an insurance notice addressed to her seventy-nine-year-old mother, who gave up her driver’s license years ago.
PART 1 — SIX HUNDRED AND FORTY DOLLARS
I sold my Honda in the spring of 2024. I want to say that clearly at the start, because for a few weeks this year I began to wonder whether I had imagined it.
It was a 2013 Honda Accord, silver, with a dent in the rear bumper from a shopping cart and two hundred and ten thousand miles on it. I had driven it for eleven years. When my knees made it hard to get in and out of a low sedan, I bought a small used SUV and traded the Honda in at a dealership on the east side of Milwaukee. I signed the title over. I took my plates off and returned them to the DMV. I have the receipt in a folder.
I am sixty-six, a retired paralegal. I reconcile my bank statements every Sunday afternoon at my kitchen table with a pencil and a cup of tea. My late husband used to tease me about it. He said I could find a missing penny in a snowbank.
So in February of this year, when I saw a charge for six hundred and forty dollars from the City of Milwaukee Parking Services on my credit card, I put my pencil down and stared at it.
For eleven years, I had paid for an annual permit to park my Honda in a city lot near my old office. I had cancelled it when I retired. Or I thought I had.
I called the city the next morning.
A patient young man named Andre looked up my account. “Yes, ma’am,” he said. “The permit auto-renewed on February first. It’s attached to your account and your card on file.”
“But I sold that car two years ago. I returned the plates.”
There was a pause while he typed.
“The vehicle on the permit isn’t showing your old plate,” he said slowly. “The plate was updated online in March of last year. A new plate number was entered for the same car. Same make, model, color and vehicle identification number.”
“Who updated it?” I asked. “Your account,” he said. “Somebody logged in with your password.”
PART 2 — THE CAMERA PHOTO
I asked Andre whether he could tell me anything about the new plate. He said he could not share who it was registered to. But he could tell me the vehicle was actively using the permit.
“How do you know?”
“Our lots have plate-reading cameras,” he said. “It’s been in the space almost every weekday. I can mail you a copy of the most recent camera image so you can dispute the charge.”
The envelope arrived four days later.
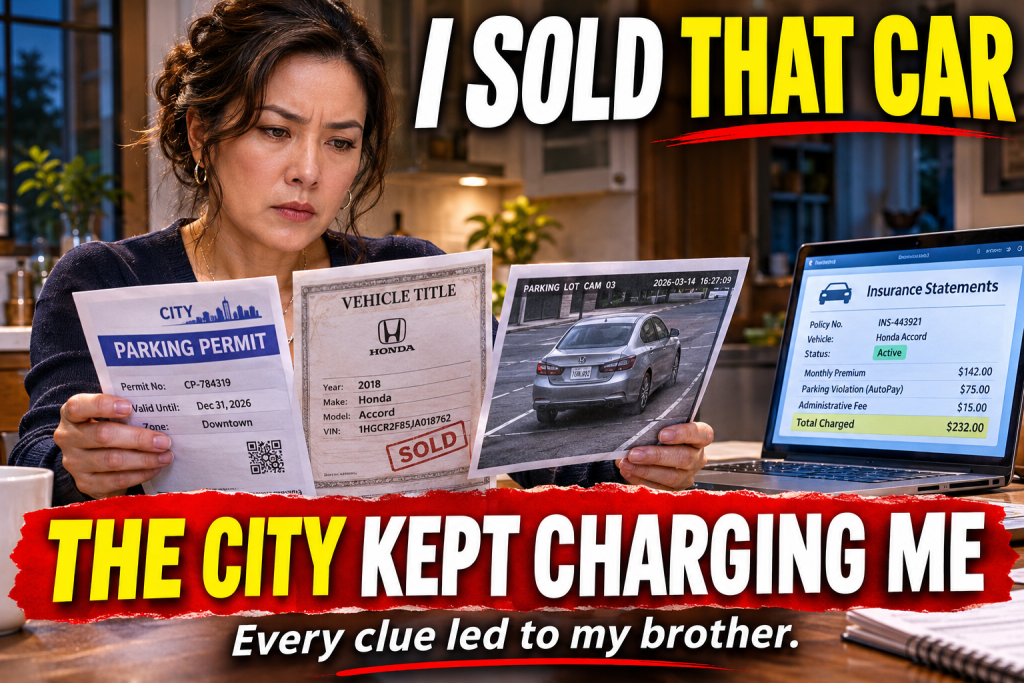
It was a grainy black-and-white printout. A parking space. A row of cars. And in the middle, unmistakable, was my old silver Honda Accord. I would know it anywhere. There was the dent in the rear bumper. There was the faded parking sticker in the corner of the back window from my old office.
But the plate was different.
I sat at my kitchen table and looked at that photo for a long time. Then I did what any retired paralegal does. I started pulling records.
In Wisconsin, you can look up basic title information if you have the vehicle identification number. I had the VIN in my folder, from the trade-in paperwork.
The title search came back the next week.
The Honda had been sold by the dealership in May of 2024, a month after I traded it in. The new registered owner was listed by name.
Margaret Brennan.
My mother.
My mother is seventy-nine years old. She gave up her driver’s license in 2020 after a mild stroke left her with blurry vision in one eye. She lives in a small ranch house in West Allis, three miles from me. She has not driven a car in five years.
I called her immediately. “Mom,” I said, “did you buy my old Honda?” There was a long silence. “What Honda, Laurie?” she said.
PART 3 — MY MOTHER’S MAIL
I drove over to my mother’s house that afternoon.
She was sitting in her recliner by the window with a crossword puzzle, the radio playing old standards. She was delighted to see me. She asked if I wanted tea. She did not seem worried at all.
“Mom,” I said gently, sitting down beside her, “has anybody asked you to sign anything about a car?”
She thought about it. “Kevin brought some papers a while ago,” she said. “Last spring, maybe. He said it was for my insurance. He said it would save me money. I signed where he showed me.”
Kevin is my younger brother. He is fifty-eight. He lives across town with his girlfriend, Tasha, who is twenty-nine, and her teenage son. Kevin has been between jobs for about four years. He has always been charming, always had a plan, always needed a little help.
He also visits our mother every Tuesday, picks up her mail and “handles her bills.” He set that up after her stroke. I was relieved at the time. I was working full time then, and I thought it was kind of him.
“Mom,” I asked, “can I look at your mail?”
She waved toward a basket on the counter. “Kevin takes most of it. But there’s some in there.”
Inside the basket, under church bulletins and grocery flyers, I found an envelope from an auto finance company. It was addressed to Margaret Brennan. It was marked “Important: Insurance Notice.”
I opened it with my mother’s permission.
It was a notice that the insurance on the financed vehicle, a 2013 Honda Accord, had lapsed. The lender had therefore purchased “force-placed collateral protection insurance” and added the premium to the loan balance. The monthly payment had increased to four hundred and twelve dollars.
At the bottom of the page was a line I read three times: “Additional driver on prior policy: Tasha R. Williams, age 29,” at my brother’s address.
PART 4 — EVERY THREAD
I did not confront my brother that day. I have seen too many cases fall apart because someone got angry too soon.
Instead, I asked my mother if I could help her with her paperwork, the way I used to help my old boss’s clients. She was happy to let me. She has always trusted me with forms.
With her sitting beside me, I called the auto finance company. My mother gave them permission to speak with me. The representative was polite and very careful.
The loan had been opened in May of 2024. Twelve thousand eight hundred dollars, to buy the Honda from the dealership. Margaret Brennan was the sole borrower. There was a co-signer line on the application, and it was blank. The payments came from a checking account in my mother’s name.
My mother’s checking account was at her credit union. I knew because I had set it up for her twenty years ago.
“Mom,” I said, “can we look at your bank statements together?”
We logged in on my laptop. My mother squinted at the screen.
The car loan payment came out every month. So did a payment to a phone company for a phone plan with three lines. So did the city parking permit, until Kevin had apparently decided to use my card instead when my mother’s account ran low. So did several cash withdrawals at an ATM near Kevin’s apartment, two or three hundred dollars at a time.
And in October of the previous year, there was a deposit of eight thousand dollars, followed the same week by an eight-thousand-dollar transfer to an account I did not recognize.
“Mom, what was this deposit?”
She frowned. “I don’t know, honey.”
I called the credit union the next morning. The eight thousand dollars was a personal loan. In my mother’s name. Applied for online.
PART 5 — THE NUMBERS
It took me two weeks to put it all together. I made a spreadsheet, the way I used to for my attorney when he was building a case.
Over about eighteen months, my brother had used our mother’s name and accounts to do the following.
Take out a car loan for my old Honda, for Tasha to drive, because Tasha’s own credit was poor and Kevin’s license had been suspended for unpaid tickets.
Register the car in our mother’s name, so he could keep using her address and insurance history.
Let the insurance lapse when he stopped paying the premium, which caused the lender to add an expensive force-placed policy to the loan.
Take out an eight-thousand-dollar personal loan in her name and move the money to his own account.
Add his and Tasha’s phones to her phone plan.
And, when my mother’s account started running short, log into my old city parking account, which he had helped me set up years earlier and still had the password for, and move the permit to the Honda’s new plate so the city would keep billing my credit card.
Altogether, the total was a little over twenty-six thousand dollars. My mother lives on Social Security and a small pension from her years as a school cafeteria manager.
Her savings, which had been eleven thousand dollars when my father died, were down to nine hundred.
I sat at my kitchen table with that spreadsheet in front of me and cried. Not because of the money. Because of every Tuesday he had sat in her living room, eating her cookies, picking up her mail, telling me how hard it was taking care of Mom.
I had been grateful to him. I had sent him a thank-you card on Mother’s Day for being such a good son.
PART 6 — THE TUESDAY VISIT
I waited until the next Tuesday. I asked my mother if I could be there when Kevin came by. I did not tell her why, only that I wanted to talk to him about her bills.
Kevin arrived at eleven, as always, with a box of donuts. He seemed surprised to see me but covered it quickly.
“Laurie! Look at you. Taking a day off?”
“I’m retired, Kevin,” I said. “Every day is a day off. Sit down. I want to show you something.”
I had printed everything and put it in a binder. The camera photo. The title search. The auto loan application. The force-placed insurance notice. The personal loan. The bank statements with every transaction highlighted. The city account history showing the plate change.
I set it on the kitchen table in front of him.
He looked at the cover page for a long time. Then he looked at our mother, sitting in her recliner, smiling at both of us, not understanding what was happening.
“It’s not what it looks like,” he said finally.
“Then tell me what it is, Kevin.”
He started talking fast, the way he always did when he was cornered. Tasha needed a car for her job. Her son needed rides to school. His license situation was temporary. He was going to pay everything back. Mom had agreed to help. Mom wanted to help.
“Did you tell Mom you were taking a loan out in her name?” I asked. “Did you tell her the eight thousand dollars went to your account? Did you tell her the insurance lapsed and the lender charged her for a new policy?”
He did not answer.
“Mom,” I said, turning to her, “did you know any of this?” My mother looked from me to Kevin and back again. Then her face slowly crumpled.
PART 7 — WHAT MY MOTHER SAID
“I thought you were taking care of me,” my mother said to my brother. Her voice was very small.
Kevin knelt beside her chair. “I am, Mom. I am taking care of you.”
“You told me those papers would save me money.”
“I was going to pay it back.”
“Kevin.” She looked at him with her one clear eye. “When your father died, I gave you two thousand dollars to fix your truck. You never paid that back either. I didn’t care. I told myself it was what mothers do.”
He bowed his head.
“But this is not what sons do,” she said. “Sons don’t pretend to be helping their mother while they empty her purse.”
I had never in my life heard my mother say anything that sharp to Kevin. She had always made excuses for him. Boys will be boys. He is going through a hard time. He means well.
Kevin started to cry. Real tears, I think, though with Kevin it is hard to tell.
“What do you want me to do?” he asked me.
“I want you to give me every password you have for anything in Mom’s name,” I said. “Right now. I want you to give me her mail key. I want the car returned to the lender or refinanced in Tasha’s own name within thirty days. And I want a written agreement to repay every dollar.”
“And if I don’t?”
“Then I file a report with the police and the Federal Trade Commission,” I said. “Mom will have to file one anyway to fix her credit. Whether your name goes in it as a family member who is repaying, or as someone who refused, is up to you.”
He looked at me for a long moment. Then he took out his phone and started writing down passwords.
PART 8 — UNTANGLING IT
The next two months were among the busiest of my retirement.
My mother signed a power of attorney naming me as her agent for financial matters. We filed an identity theft report so her credit union and the lenders would treat the accounts properly. I froze her credit at all three bureaus. I set up alerts on her checking account that sent a text to my phone for every transaction over twenty dollars.
The auto finance company was surprisingly helpful once they understood what had happened. Kevin and Tasha came in together and refinanced the Honda in Tasha’s name, with her mother as co-signer. The force-placed insurance was cancelled and partly refunded once Tasha bought her own policy.
The credit union worked with us on the personal loan. Because Kevin admitted in writing that he had applied for it, and because he agreed to a repayment plan, the credit union transferred the debt to him.
The city refunded my six hundred and forty dollars after I mailed them the title transfer, the camera photo and a copy of the identity theft report. Andre, the young man at Parking Services, called me personally to tell me. “That’s the most organized dispute file I’ve ever seen,” he said.
I changed every password in my own life too. Every one. The parking account had been the smallest of threads, but it had led to everything.
Kevin’s repayment plan was simple. Three hundred dollars a month, to our mother, through me. Thirty-two months.
He was late on the first payment. He was on time for the second. And the third. And the fourth.
I do not know whether he was truly sorry or simply afraid. I suspect, honestly, a little of both. Either way, the checks kept coming.
PART 9 — TASHA
I want to say something about Tasha, because I misjudged her.
When I first saw her name on the insurance notice, I assumed she was part of it. A younger girlfriend, using an older man’s elderly mother to get a car. I was ready to dislike her.
She called me two weeks after the Tuesday visit. She asked if she could come by.
She sat on my couch and cried for twenty minutes. She said Kevin had told her the car was a gift from his mother, who wanted to help because Tasha’s son needed rides to school. She said she had wanted to send Margaret a thank-you note, and Kevin had told her not to bother, that his mother hated getting mail.
“I didn’t know,” she said. “I swear I didn’t know any of it. I would never take money from someone’s grandmother.”
I believed her. I am not always right about people, but I believed her.
She went to see my mother the following week, with her fifteen-year-old son, Jalen. They brought flowers and a card that Jalen had written himself. My mother was charmed. Jalen now mows her lawn every other Saturday in summer and shovels her walk in winter, and she pays him in cash and cookies.
Tasha left Kevin that spring. She says she is not angry at him anymore. She just could not live with someone who lied that easily.
She still drives my old Honda. She sent me a photo of it in her new apartment’s parking lot, with a brand-new parking permit in the window, in her own name, paid with her own card.
Underneath she had written: “All legal now. Thank you for not giving up on figuring it out.”
PART 10 — WHAT I KNOW NOW
My mother is eighty-one now. She is still sharp, still doing the crossword every morning, still telling me I worry too much. Her savings are slowly coming back. Kevin finished paying her this fall. Every dollar.
He and I are not close. We see each other at holidays. We are polite. He takes Mom to lunch sometimes now, and he pays for it with his own money. He found a steady job at a warehouse and got his license back. Last Christmas he gave me a small gift, a framed photo of our parents on their wedding day, and a note that said only, “Thank you for watching out for her when I didn’t.”
I keep the camera photo of my old Honda on my refrigerator. People think it is a strange thing to display. I tell them it is the most important picture I own.
It reminds me that a small charge on a bank statement, the kind most people would shrug off, can be the end of a thread. And if you pull it patiently, it can lead you to a truth that protects someone you love.
If you have an elderly parent, please do this one thing: look at their accounts with them. Not to accuse anyone. Just to look. Ask who picks up their mail. Ask who has their passwords. Ask what papers they have signed lately.
And check your own statements too. Every line. Every small charge that does not make sense.
Sometimes the person draining your family is not a stranger on the internet. Sometimes it is the one who brings the donuts on Tuesday. The only way to know is to sit down at the kitchen table, pick up your pencil and follow the money all the way to the end.